Anatomy of a Bad Trading Day
I entered the day long and leveraged long. The morning was a churn and then we broke lower. I will explain what I did right and wrong and perhaps help some of you retards who trade much more poorly than I do.
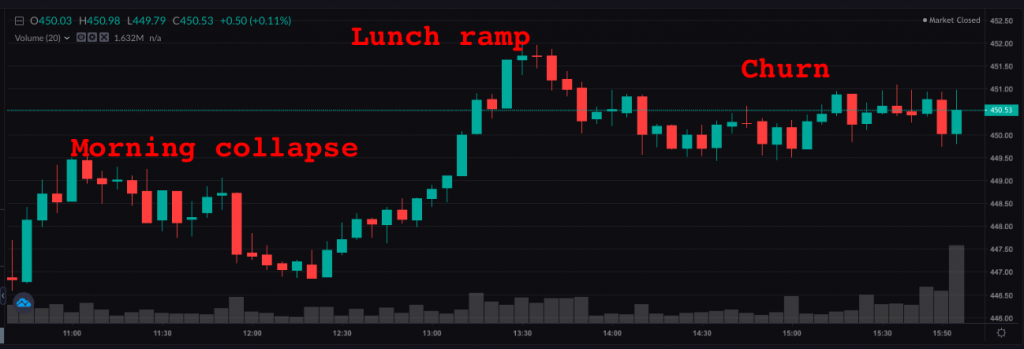
So I entered the day 102% long. When the markets started to taper off I cut loose my leverage and waited to see if the market might respond with some upticks.
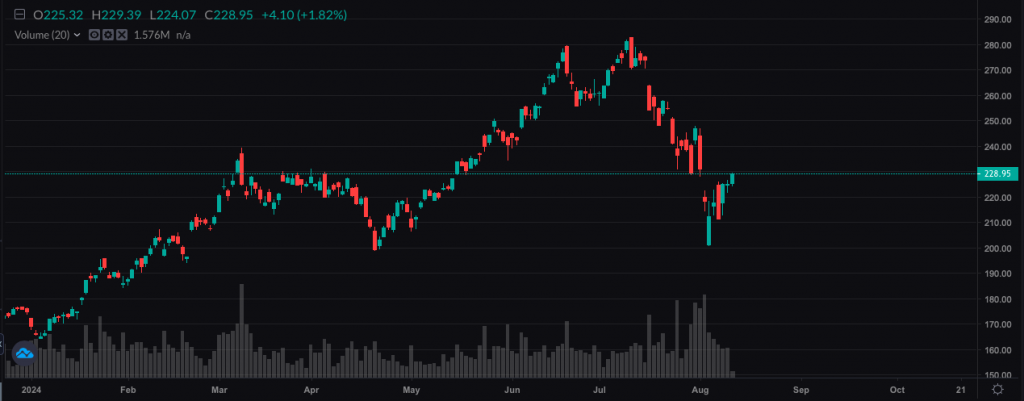
It’s important to not jump to conclusions when day trading. So, I started to buy some inverse ETFs: 12% $SOXS and then 3% $UVIX. I made some coin almost immediately on the $SOXS and thought to myself “I should extricate myself from the trade” in exchange for a lesser negative beta instrument like $SQQQ. To briefly explain, the downside has been led by the semis. On paper, the beta for the $SOXS is about negative 3.75, but I believe it’s more like negative 5 or 6. What that means, basically, is a position on your books can dominate your unbooked PNL providing your other positions are having a slow day, which seemed to be my case today.
I had gains of about 1.5% on $SOXS and was about to pull the trigger but decided to wait, since markets looks really weak. Even though I had both $UVIX and $SOXS, it wasn’t entirely hedging my portfolio and I was losing about 5bps per 10mins, so I added some short biotech $LABD to the mix. It’s worth noting that as markets drifted lower, the $UVIX was not budging, which is always a bad sign.
Around noon we started to leg up and all of my gains quickly became losses. It wasn’t long before that really small $UVIX became an albatross, so I sold it for an inexcusable 8% loss. As markets lifted, I added some longs to offset the losses being absorbed in my inverses, at which point my other 38 stock positions were barely moving the needle. I ended up paring down the short exposure by selling both $LABD and $SQQQ for 2.5% losses and then sat and looked at $SOXS as markets crested into the lunch ramp. Overall, I was down about 70bps and thought to myself “if I sold it here and markets reversed, I’d be fucked completely.” A 12% position will not eliminate losses, but it will hedge them by around 50% in a portfolio beta of 1.
I then added to the position in an average down gambit to 15% and traded long for the duration of the session, booking around $4k in profits in ordinary stocks to somewhat offset the $15k in losses taken in the inverses. By the end of the day, my instincts were proven correct, as markets churned and went nowhere into the close, but with the semis coming in to the point where my 4% loss is now about 1%.
All in all, I shed 0.63% for the session, but feel good about averting calamity and like my position into Monday, which is really net long with some $BITX, $SNOW and $META on margin adding to an already long book. The way I figure, the $SOXS position at 15% will offset my losses or gains by about 40%, which is fine. Perhaps I will get lucky and get to sell a gap down and go. Either way, I did good for the week, +266bps in what could be considered a truly deleterious week of trading.
HAGW
Comments »