
Markets are pricing in a definite rate cut in September, buttressed by today’s weak NFP numbers.
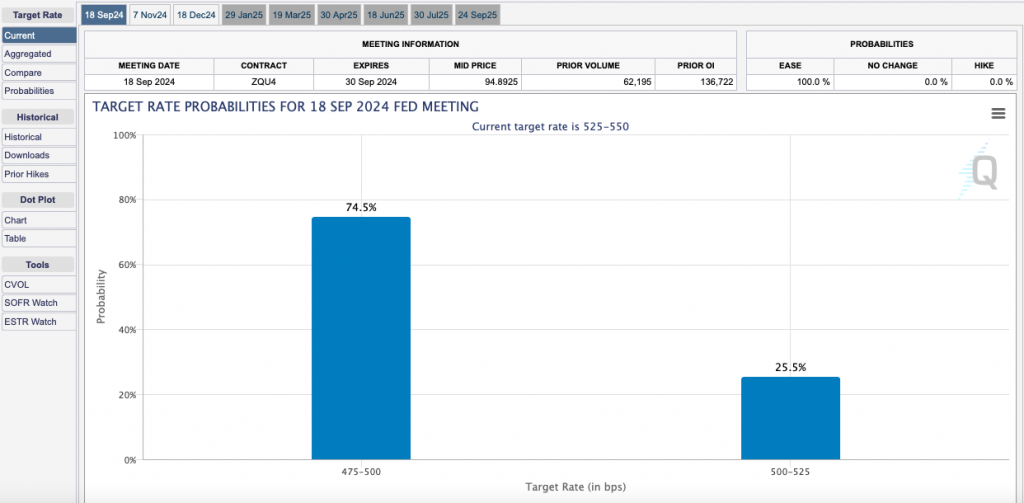
And we are beginning to price in nearly 6 rate cuts from now until March of 2025.
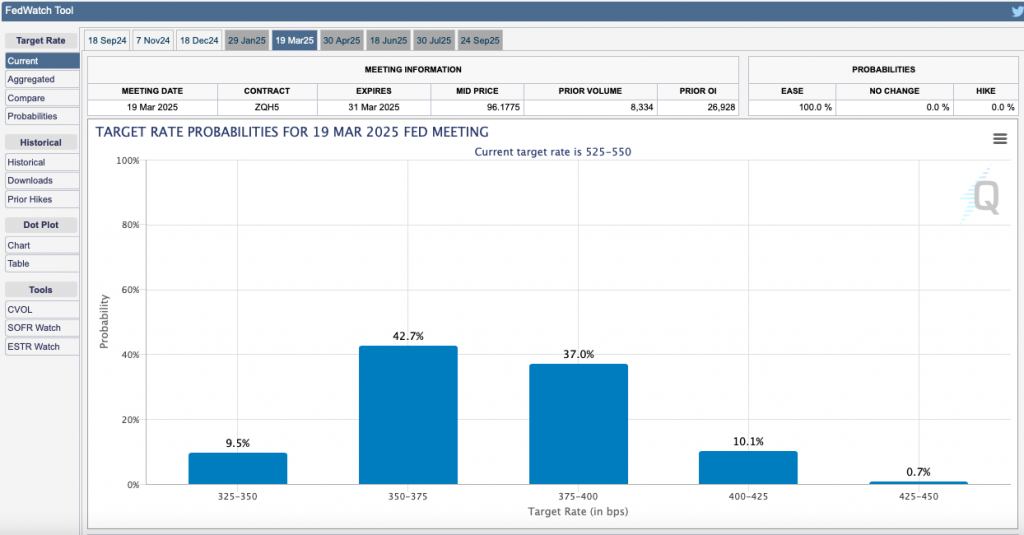
Either way, we are pricing in significant Fed rate cuts and that’s interesting because the only reason we’d do that is if the Fed thought we were heading for recession. Look at the banks, hammered down 10% in the past week, which should not happen as their treasury holdings rise and the economic environ, based on recent data, is fine.
Heading into the weekend, we venture into the specter of a war between Iran and Israel, which is not being reflected in the oil markets. We have seen a massive rise in the VIX index, up as much as 60% earlier today, suggestive of a panic into puts as asset managers scramble to hedge. Intraday, markets looked like it wanted to bottom and then traders remember today is Friday and markets don’t bottom on Friday and black Monday can in fact loom.
Thus far, we have massive damage in various industries OFF THE HIGHS and the technicals are very weak. Our mean reversion algorithms in Stocklabs are now “clustering” indicative of a momentous change in the candor of the tape. If forced to bet, I’d venture we have some more downside left. Bear in mind, the valuations in the semis were extremely overvalued but now they’ve moderated to the point that they are cheaper than last year.
Look at the losses.
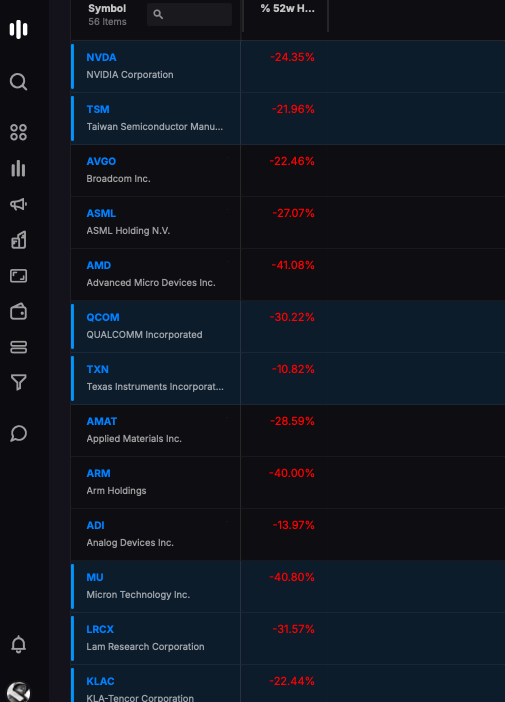
Off from 52 week highs:
$SMH down 24%
$KWEB down 21%
$JETS down 20%
$IBIT down 19%
$XME down 11%
$QQQ down 11%
$KRE down 10%
$IWM down 8.5%
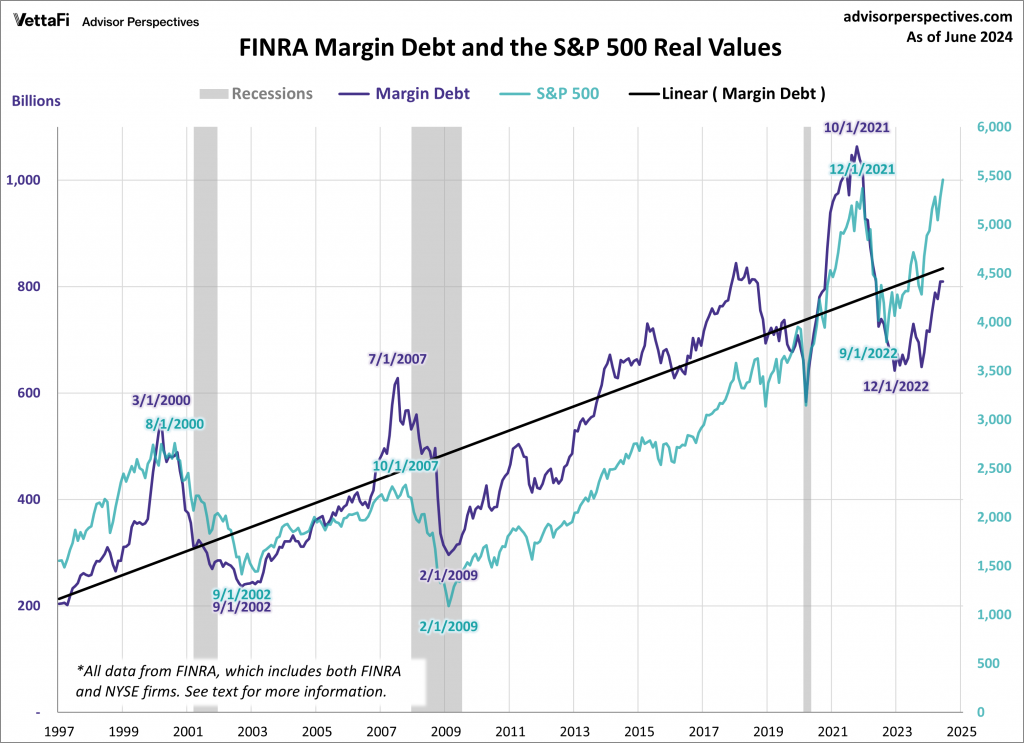
If you are buying here you’re assuming the economy is not heading into a recession and that the margin call infused selling will exhaust itself and we’ll quickly ramp higher. If you’re selling here, you’re thinking where there is smoke there is fire and the reason why all of this is happening is because the economy is much weaker than the umbers suggest, akin to what the CEO of $W said yesterday during his call, comparing the present credit environ in home good buying to the financial crisis of 2008.
Comments »