iBankCoin
Home / Dr. Fly (page 1082)

Dr. Fly

18 years in Wall Street, left after finding out it was all horseshit. Founder/ Master and Commander: iBankCoin, finance news and commentary from the future.

Stocks Fade into the Close; I Might Have a New Core Thesis Trade

Those of you partaking in the After Hours with Option Addict free trials were entreated to life changing events, as energy stocks spiraled higher these past two days. However, as the very basic of laws presiding over life dictate, all good things must come to an end. Stocks crested mid-day, as the presumptive Presidential nominee, Hillary Clinton, made HERstory today–locking in the democratic nomination over the old seahag, Bernard Sanders.

Whether stocks topped today, or will continue to run for the next 10,000 years, is irrelevant to me. Viewing the landscape from a very high perch, I find it very notable that the BOJ are moving towards tossing out helicopter money onto its robot loving citizens. Bear in mind, their companies are now able to borrow, seemingly, unlimited amounts of money for nothing at all. If we are to assume central banks will continue the path to undermine their own currencies, we must assume alternative currencies, like gold and silver and maybe Bitcoins, will continue to attract asset allocators.

This isn’t even about being bullish on gold or bitcoins. It’s about trying to determine where money managers will place money, in light of these new developments.

As such, I am exploring the idea of adding gold and gold stocks to my core holdings, which, at the moment, holds nothing but TLT and cash. If and when I decide to build a portfolio of gold stocks, I will do so in Exodus first.

Comments »
$FFIV Explodes Higher on Takeover Reports (Reuters)

According to Reuters, ‘people familiar with the matter’ (fucking rats) said the company hired Goldman Ball Sachs to explore a sale of the company. The stock had been halted on upside volume, as fiends with cocaine on the brain bid up the stock. The stock reopened and is higher by more than 12%.

The only other networking stock responding is ACIA, higher by 4.7%.

Comments »

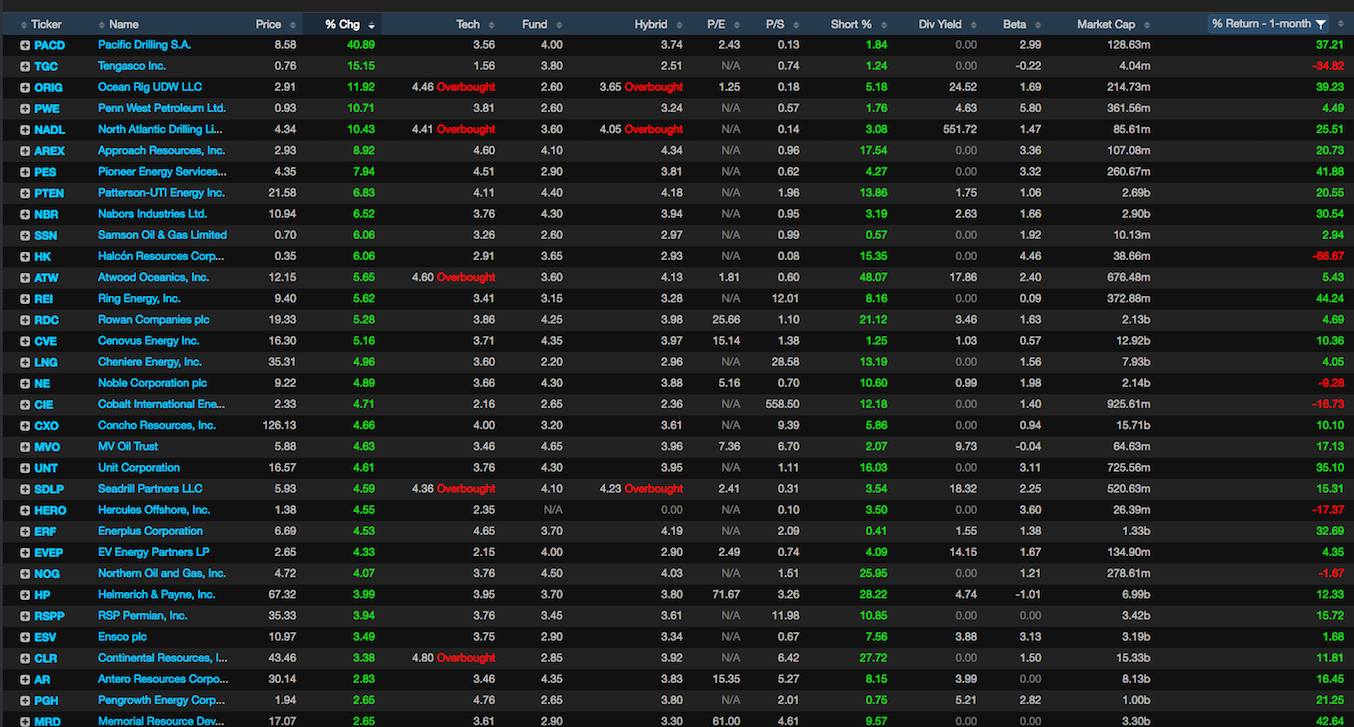
Energy Stocks at Most Overbought Levels of 2016

With crude topping $50, traders are bidding up oil stocks, like bums vying for the last bottle of Georgi vodka. The gains, quite frankly, are monumental.

oil

I was watching an interview with the CEO of SPN earlier today. He’s indelibly bullish on crude and thinks it trades up to $60 by year end. His thesis is the same lie being shopped around Wall Street since February. Production declines will lead to an equilibrium of supply v demand. Meanwhile, back in the real world, global oil production is at new highs. Sure, many of the marginal players are folding up tent. But these are small little shits, in a vast reservoir of feces.

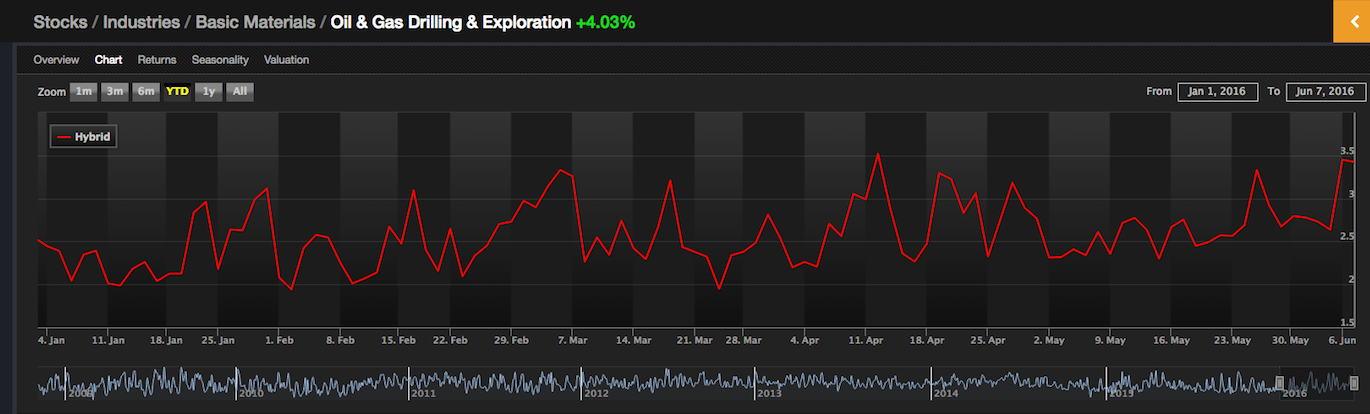
According to Exodus, the energy sector has never been this overbought. Have a look.

oilOB

In fairness to the crude bulls out there, recently, overbought conditions beget more overbought conditions, as prices worked their way higher.

Comments »

Citigroup Made Billions Buying CDOs in the Financial Crisis

I read this article and viewed the clip below and was most astounded by the fact that neither the author of the piece or reporters covering the story felt there was an extreme wrong done here. I guess the statutes of limitations are up for these sort of crimes, so the rats are showing everyone all of the cheese they had stolen over the years.

If you recall, during the grimmest days of the financial crisis, Citi, who was bogged down with billions in bad CDO exposure, received a $300 billion bailout from the government. They didn’t go bankrupt, or in receivership, just bailed out. At the time of the bailout, I assumed they were using the fresh liquidity to sell toxic assets and take writedowns. Instead, they were starting up a new CDO desk to buy these assets from the Fed. Fast forward until now, that desk was the most profitable at the bank, making billions off the toxic crap they bought.

Good news, right?

The fuck out of here.


“It’s impossible to imagine. You’re being bailed out with one hand, and you’re pouring money into the very same assets that precipitated the bailout with the other.”

Citi rose from the ashes, like the Phoenix, to become the biggest player in the CDO market. In some cases, they were 80% of the market–all thanks and praise to the government dollars that bailed them out.

Comments »

Green Mountain Coffee Cancels Keurig Kold Product Line

Has anyone uses this thing? What’s with the K spelling of ‘cold’ anyway? It’s very KLAN-like. It’s funny how the Keurig craze came and went. When it first came out, I went bonkers for it. I used it 5 times per day, until I realized I was brewing algae into my coffee. Now I just use freshly ground beans and a french press. It does not get better. Some people like the pour over technique, which is fine too. Either way, the whole K-cup, Nazified version of coffee frenzy– that swept America off her feet, is gone.

Keurig Kold, released last year, was the company’s big bet that it could duplicate the success it had with single-serve coffee machines. The idea was to let customers make their own soda at home, providing an alternative to SodaStream machines. Coca-Cola Co. threw itself behind the effort, agreeing to buy a stake in the company. Coca-Cola Chief Executive Officer Muhtar Kent said last year that the Keurig Kold might be a bigger hit than the company’s original coffee machine.

Instead, reaction to the device was underwhelming, according to Stifel Financial Corp. That raised concerns that it would become at best a niche product. JAB and other investors then stepped in to acquire the company for about $14 billion and brought in a new CEO. Coca-Cola, which at one point had a Keurig stake of about 17 percent, was bought out by JAB and made a small profit on the investment.

“We are grateful to all of our consumers who have supported our company in the innovation of single-serve beverages,” Suzanne DuLong, a spokeswoman for Keurig, said in an e-mail. “Reimagining how beverages can be created, personalized and enjoyed will continue to guide Keurig’s strategy into the future.”

This cancelation is good news for SODA, who still makes believe Americans are interested in drinking soda pop.

Comments »

Paul Ryan Calls Trump’s Comments on Mexican Judge ‘Textbook Definition of Racism’


Just one day since Speaker Ryan came out to endorse Trump, he’s disavowing him for comments made about a judge presiding over the Trump U case, who Trump says is biased due to his affiliations with pro Mexican, super racist organizations, like La Raza.

Whether you agree with Trump or not, this action by Speaker Ryan is bound to have lasting ramifications. Trump will retaliate, likely saying some pretty crazy shit. Then the GOP might try to replace Trump as their candidate at the convention, using this faux crisis as a reason to do so. They truly hate Trump, so it won’t take much to cause a revolt.


Comments »

Goldman: Sell $JBL Because $AAPL Sucks

Apple is their largest customer. Jabil is a contract manufacturer for the electronics industry. Generally speaking, when they do poorly, the electronics industry is sucking wind.

Hence, Goldman slapped a sell rating on JBL today, citing 7 out of Jabil’s top 10 customers mired with a weakening outlook.

Their Apple exposure has become an albatross to them.

“We see earnings pressure from both limited top-line growth and increased overhead costs for Jabil. For revenue, Street assumptions have been reduced for 7 of Jabil’s top 10 customers since the last EPS report,” Goldman Sachs’ Mark Delaney wrote in a note to clients Tuesday.

“Our reduced estimates are consistent with the fact that Goldman Sachs analysts have lowered estimates for several of Jabil’s key customers since Jabil’s last report (e.g. Apple, NetApp and Ericsson). … High Apple exposure is a key part of the reason that Jabil has had to significantly reduce its guidance in two of the last three fiscal years.”

Comments »

$RL Horsekicked, Following Earnings Warning, Restructuring Plan, Share Buybacks Continue

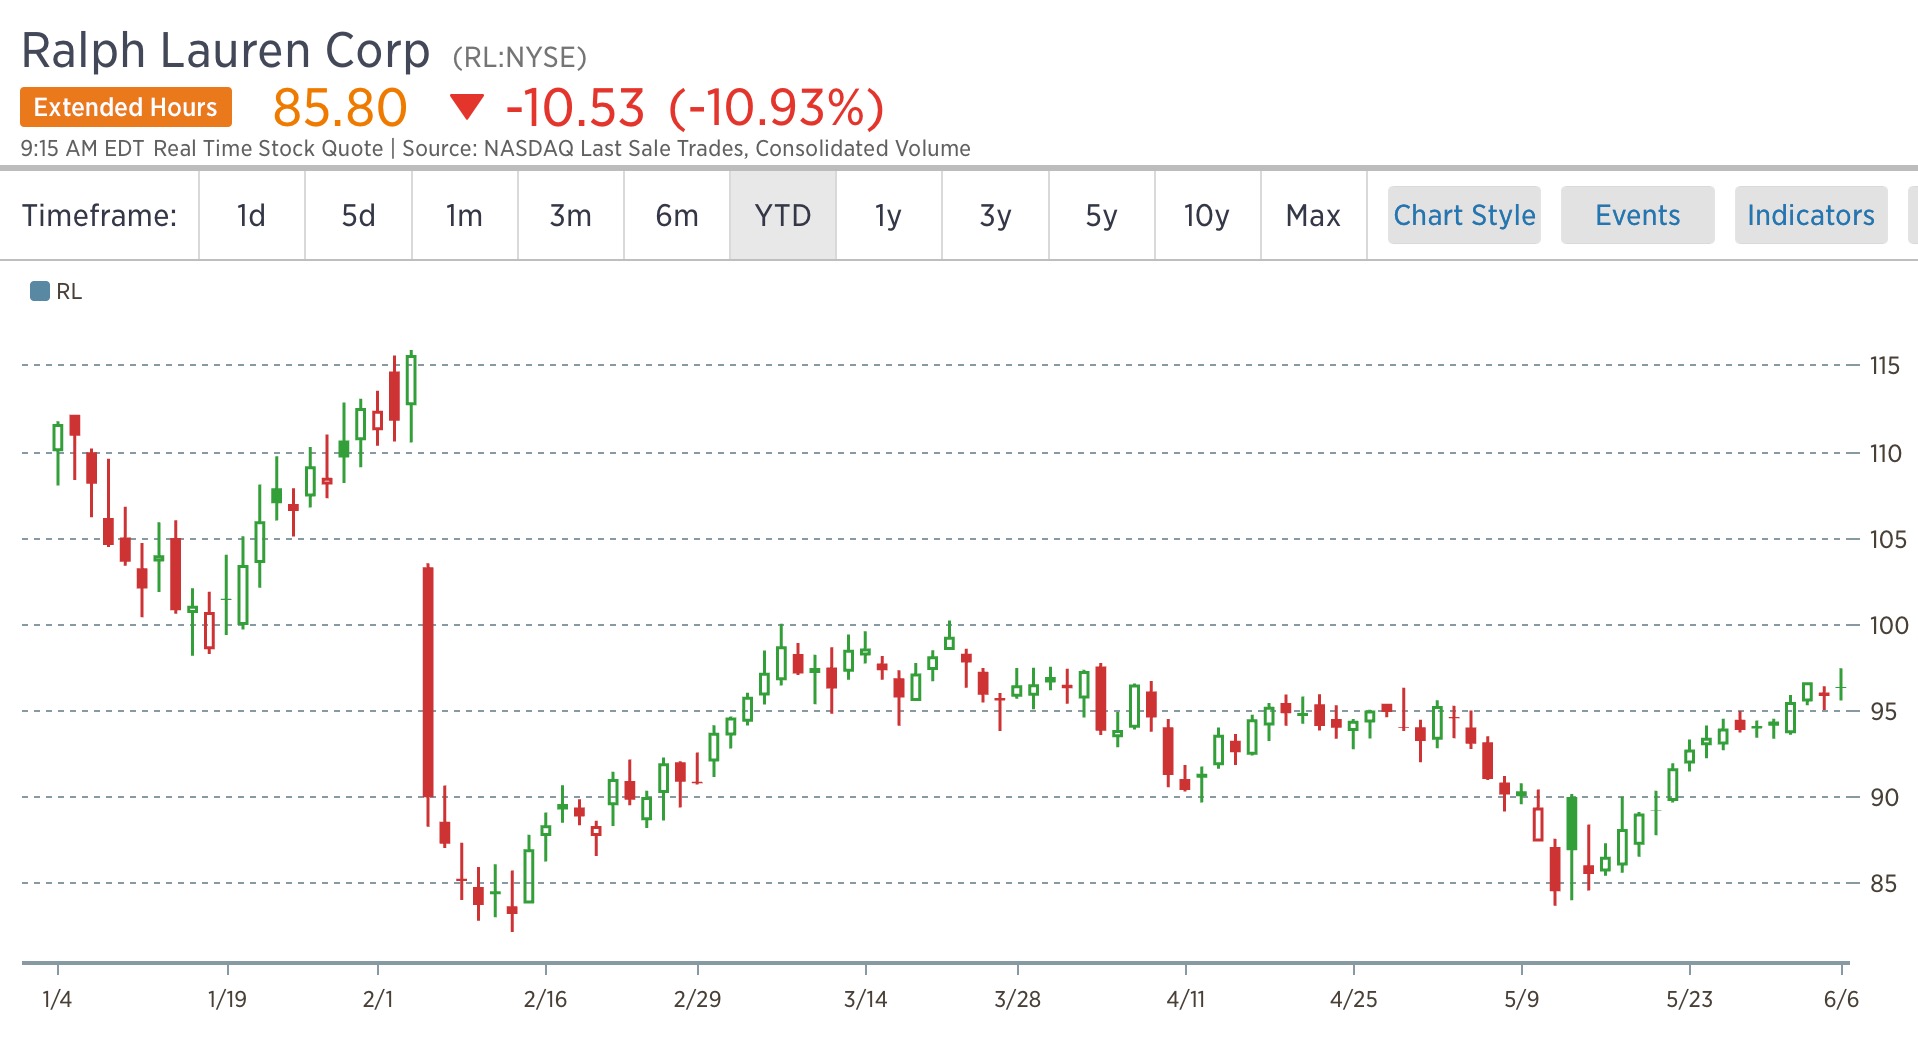
People aren’t wearing clothes like they used to. RL just unveiled their restructering plan, guided revenues lower, and reaffirmed a moronic $200 mill share buyback. The market isn’t impressed. The stock is being drilled.

Alas, the mall is dead. Millennials dress like homeless men. Share buy backs are pretty much the dumbest thing a company with core fundamental problems can implement.

image

Fiscal 2017 Restructuring Activities: Co expects FY17 restructuring activities to result in ~$180-$220 mln of annualized expense savings related to its initiatives to streamline the organizational structure and rightsize its cost structure and real estate portfolio. This is in addition to the $125 mln of annualized cost savings associated with the Fiscal 2016 restructuring activities.Co expects to incur restructuring charges of up to $400 mln as a result of the Fiscal 2017 restructuring activities and up to a $150 mln inventory charge associated with the reduction of inventory out of current liquidation channels in line with the Way Forward Plan. These charges are expected to be substantially realized by the end of Fiscal 2017.

Q1 and Full Year Fiscal 2017 Outlook: Co expects Q1 consolidated net revenues to decline at a mid-single digit rate vs -3.5% consensus, op margin ~110-160 basis points below the comparable prior year period. Co sees FY17 net revenues at a low-double digit rate vs -4% consensus due to a proactive pullback in inventory receipts, store closures, pricing harmonization and other quality of sale initiatives, combined with the weak retail traffic environment in the U.S. FY17 op margin ~10%, as cost savings are expected to be offset by growth in new store expenses, unfavorable foreign currency impacts, infrastructure investments and fixed expense deleveraging. The Fiscal 2017 tax rate is estimated to be approximately 29%. Capital expenditures are expected to be ~$375 mln in Fiscal 2017. This guidance assumes ~$200 mln in share repurchases. Q1 2017 and Fiscal 2017 guidance excludes the restructuring and inventory charges associated with the Fiscal 2017 restructuring activities.

Long-Term Financial Outlook: As a result of its Way Forward Plan, the Company expects to stabilize performance in Fiscal 2018 and pivot to growth off of a smaller, more profitable base in Fiscal 2019, with improving operating margins in both fiscal years. In Fiscal 2020, the Company is targeting market share growth and a mid-teens operating margin.

I thought the stock was interesting in the low $120s. In the $80s, this looks like a steal.

Comments »

Suntrust: If Current Trends Persist, $TWTR Will Pursue Merger

This isn’t exactly a bold call. As a publisher of digital content, I am reliant upon Twitter for traffic and engagement with readers. But many people don’t get Twitter. It’s a bit too complex for them to figure out, so they dick around with facial filters all day long on Snapchat. There is immense value in Twitter that has yet to be released. Hopefully, they can sell the property to someone that could properly manage it.

“We note that if the current trend of meager user and engagement growth remains, we think it’s inevitable that Twitter will need to pursue M&A alternatives as has been discussed in the media for some time,” he writes. “Our current read of trends suggest a difficult April and May consistent with April levels thus far.”

Peck has kept his “buy” rating on the shares given the perceived value of Twitter as an M&A target. “Twitter within a larger property could be much more efficient on the cost and development lines and benefit from the reach on the top lines,” he adds.

The analyst believes a sale would likely be a 2017 event, assuming current trends do not improve. He adds that the most likely partners for such a deal would be Google, Facebook, Apple, or a more traditional media property.

I do believe Twitter would fetch for a decent sized premium from current levels, if it were for sale.

Comments »

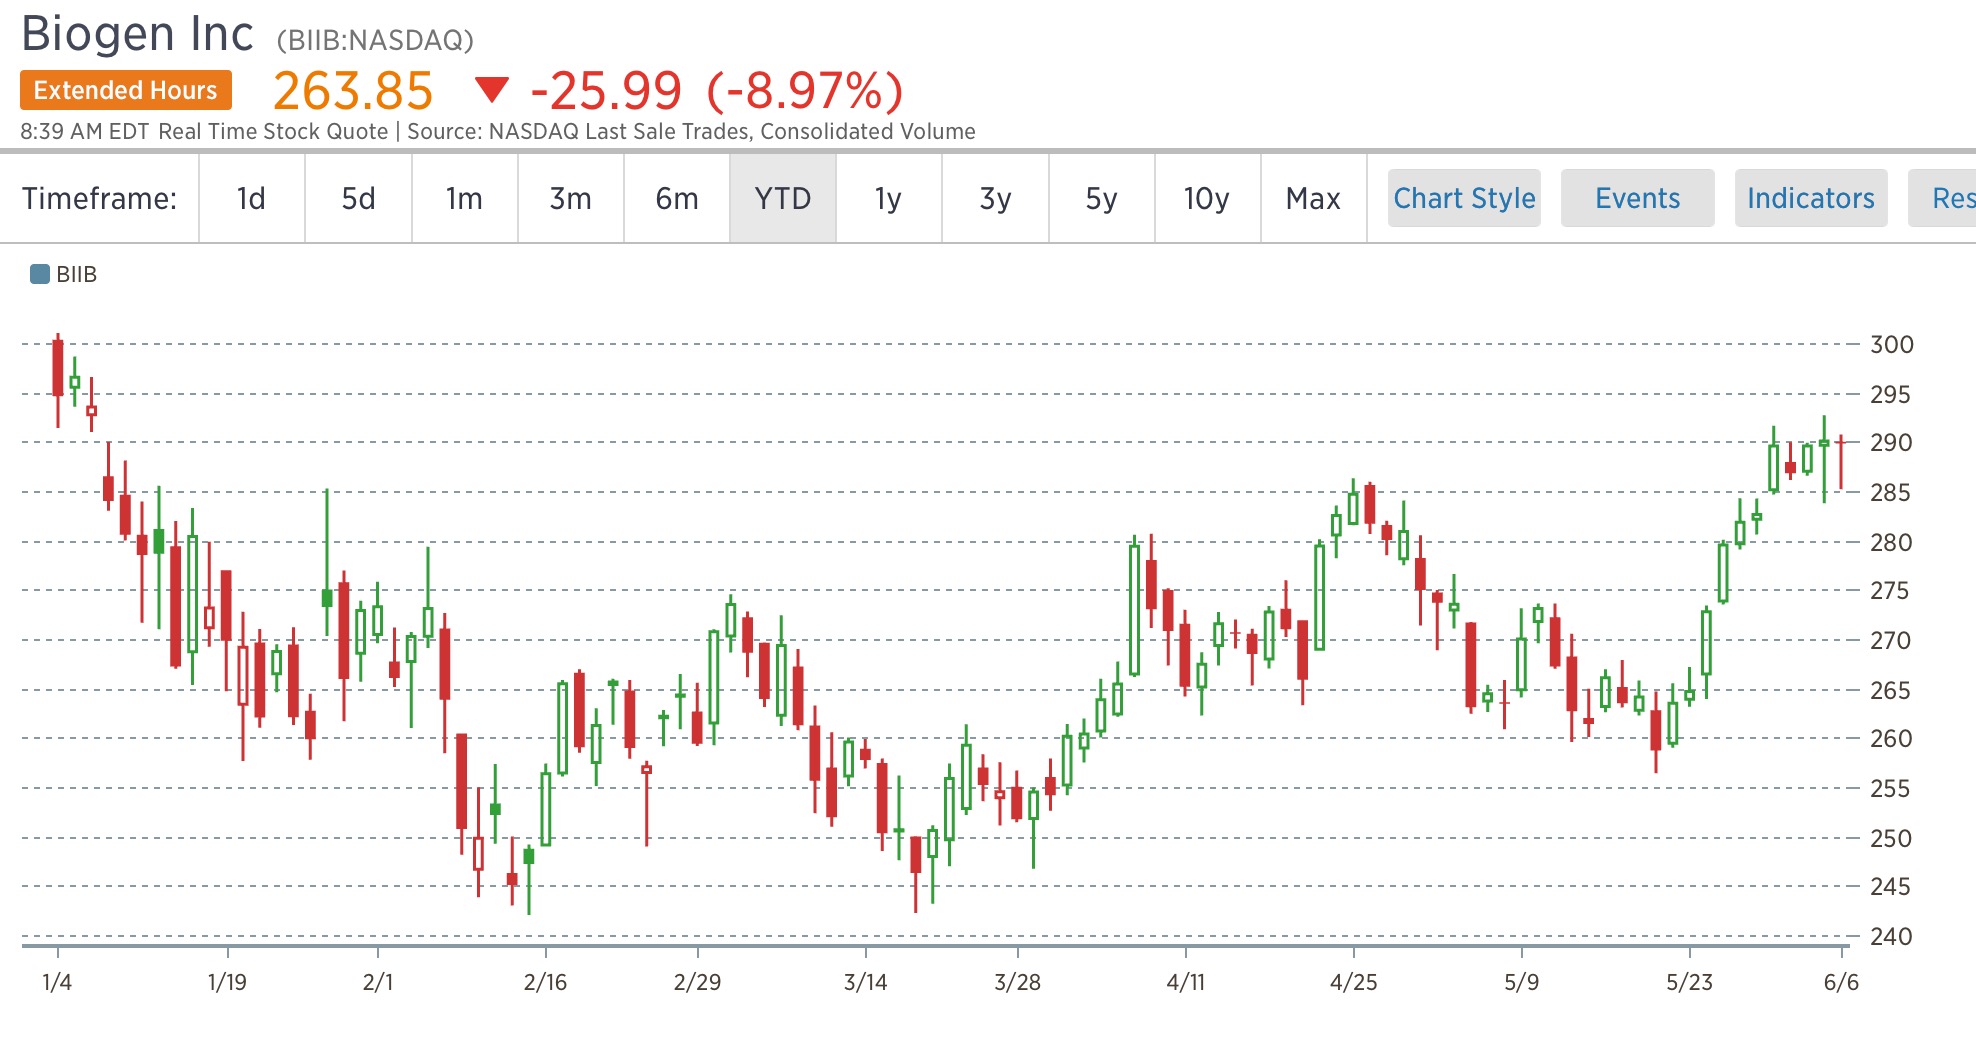
Biogen Plunges After MS Drug Fails to Meet Primary Endpoint

Even when you’re invested in a diverse, revenue and earnings generating machine, like Biogen, failed clinical trials for important pipeline drugs can wreak havoc in investors portfolios.

image

In the study, opicinumab missed the primary endpoint, a multicomponent measure evaluating improvement of physical function, cognitive function, and disability. However, evidence of a clinical effect with a complex, unexpected dose-response was observed.

Opicinumab also did not meet the secondary efficacy endpoint in Synergy, which evaluated the slowing of disability progression. Safety and pharmacokinetics were also assessed as secondary endpoints.

Opicinumab was generally well-tolerated and the safety profile was consistent with what has been observed in prior studies. Opicinumab showed a linear, well-behaved PK profile over the studied dose range. Synergy results will be presented at future medical meetings.

That’s about $6 billion in market cap wiped out because of a phase 2 trial. Utterly ridiculous. There are better ways to get rich, than cavort inside of these biotech fun houses.

Comments »