It looks like the American healthcare system is at a tipping point, both exhausted and fed up with extraneous costs associated with financing large r&d projects for big Pharma, which is geographically exclusive to a nation paying upwards of $1,700 per mo for family healthcare insurance.
Others might argue that America has the best healthcare in the world. While debatable, that doesn’t mean the standards at NYU Langone are the same at Brookdale in Brooklyn. There is a vast ocean in quality standards associated with socio economic backdrops in this country, with the elite getting consieur, cash only, services, while the middle class gets stuck with the ham and egger script writers.
Rant over.
GILD is feeling the bern. Pricing pressures are hitting them on every front.
Gilead’s total product sales rose 4 percent to $7.7 billion. Sales of hepatitis C drugs Sovaldi and Harvoni, the company’s second generation hepatitis treatment, totaled $4.29 billion, which was short of the $4.63 billion average Wall Street estimate, as compiled by ISI Evercore.
“The hep C numbers are a little light in the USA and that could be due to higher rebating and more competition,” said RBC Capital Markets analyst Michael Yee.
Gilead Chief Financial Officer Robin Washington said on a conference call that U.S. Harvoni sales declined due to an “increase in discounts required to open up access to patients with lower (liver) fibrosis scores,” as well as a modest shift in sales to deeply-discounted government payers, including the Department of Veterans Affairs.
As such, the stock is getting clown punched today.
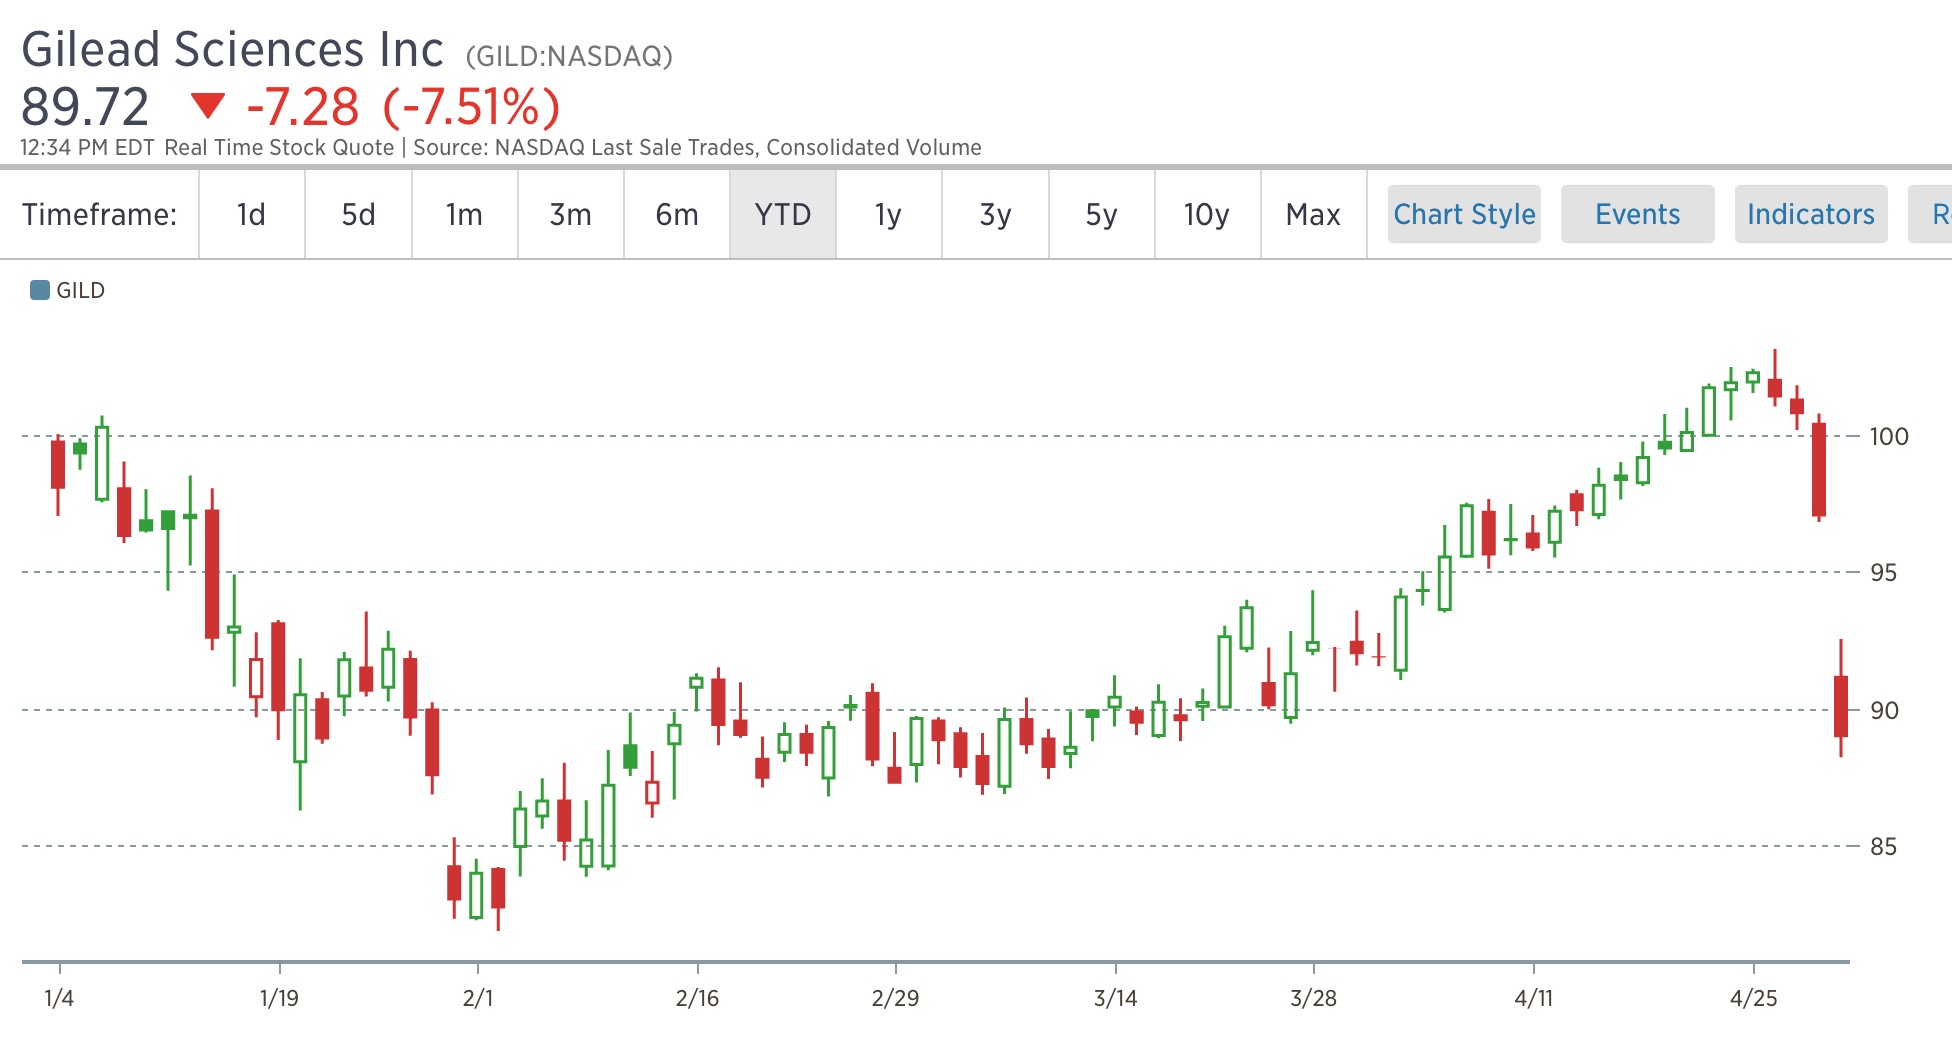
We’re seeing this across the board in Pharma, from GILD to VRX to BMRN to VRTX to CELG. Gone are the days when ENDP or MNK can buy a drug and mark it up 500%.
Comments »