Now with the benefit of hindsight, one guest after the next is visiting CNBC and Bloomberg to show the world what assholes they are, by being condescending pricks — maligning ‘retail’, which is just another word for idiot trader, for getting caught in a black swan event long inverse volatility products SVXY and XIV.
Having spend nearly 2 decades on Wall Street, I am very familiar with the snobbery on trading desks or even from the simple assholes managing money for private clients. But it takes a special sort of asshole to go on teevee and flippantly dismiss those who just got ruined in inverse volatility products — equating their loss as non-events — chastising them for not reading the fine print in the prospectuses. I know 1 person out of 100 who actually reads these things. Please, go fuck yourself.
Here we have Dean Curnutt from Macro Risk Advisors saying the blowing up of these products was a ‘good thing’ for the Fed.
Watch this tone deaf man be an asshole on live teevee.
And here’s another one, Tim Freeman from Elevation LLC saying everything is wonderful and behaving as it should. This has a certain Baghdad Bob flair to it — some slickster calmly telling people everything is good, when in fact the fucking world is melting down around him. Wonderful.
And then Wall Street wonders why Main Street hates their guts.
Do not be fooled by the futures markets on some of your commercial outlets. There is a significant ‘fair value‘ of more than 350 points that needs to be accounted for and most people aren’t aware of this. After FV, Dow futures are -680, Nasdaq -120.
The VIX markets have blown up after years of complacency, spending most of its time in the low double digits. Early going, VIX is trading at 50, which has laid waste of inverse vol ETFs, such as XIV, ZIV, and SVXY. What is being talked about by people on Wall Street this morning is the over-the-counter vol markets or ‘shadow volatility markets’ — which has been used to sell premium in volatility, boosting returns for hedge funds all around the world. The ramifications of this trade blowing up aren’t known yet, in spite of the fact that Credit Suisse says they’ve got the whole trade covered and is entirely hedged. There are many others who aren’t hedged and are now naked volatility into a market screaming lower, blowing out standard deviations — putting the fear of the devil into traders.
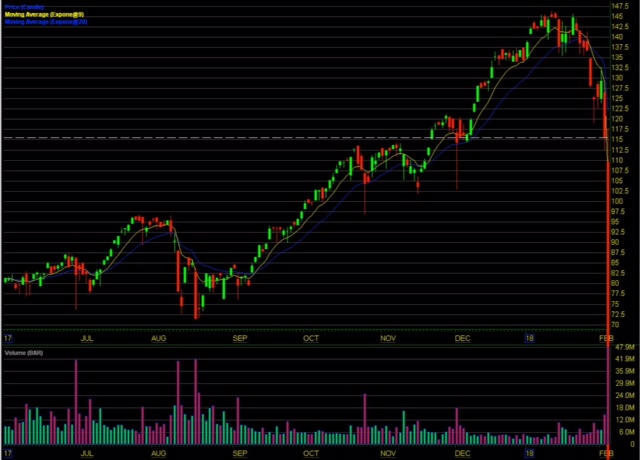
The downside move in XIV, which was triggered by a termination event that caused Credit Suisse to buy volatility between 4-4:15pm during yesterday’s trading session, literally broke charts.
What people will be watching next is the plumbing of the system, credit default swaps, bond yields, and especially the junk markets — which have also been used as a place to achieve easy returns in a non-volatile market. Now with the OTC vol market blowing up, in addition to the retail vol ETNs, there could be ancillary victims that may pop up in these areas.
WTI is -1.2%, Gold +0.1%, Dollar +0.3% v Euro, and BTC -10%.
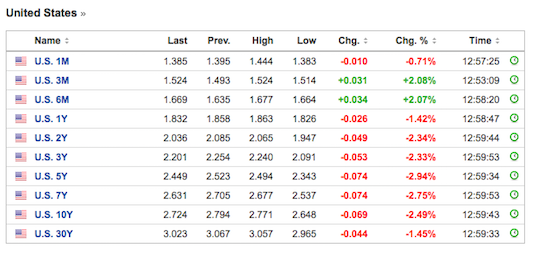
Bond yields are going lower and the market is no longer pricing in 4 hikes, but 2.
Zerohedge has a research note by Morgan Stanley up, discussing the debacle.
Some of the selling on Monday likely reflected investors anticipating systematic supply on Tuesday – this means the $30 to $35bn QDS estimates for sale Tuesday (detailed below) may net down to $15 to $25bn. This is still enough to have negative impact on markets though and will be compounded by dealer short gamma positions.
Anticipation of further supply later in the week from both annuities and risk parity funds could bring in more fast money sellers Tuesday.
The near bankruptcy of the inverse VIX ETPs will be a very negative headline, and the several billion dollar loss for holders, largely retail, will scare some out of the market or force liquidations of other products to raise cash.
Institutional vol sellers will likely cover exposures as well in the coming days and weeks. While these positions will not take losses on the same scale of the VIX ETPs (because they are generally scaled more conservatively) unless there is a quick snap back many investors will likely take down risk, supporting implied volatility in the process.
On the positive side, much of the short gamma exposure in the VIX market has been wiped out, leaving less risk of a further volatility spike from here.
Investors were not in panic mode despite the selloff, as this move has ‘only’ wiped out one month of P/L. As noted earlier in one sense this is good as it might slow discretionary supply, but it also highlights that discretionary investors are still very long risk and could easily turn sellers.
Who are the incremental buyers here? Macro funds betting on the vol unwind that has now happened could cover and turn buyers, but for real support the market needs deep pocket asset allocators to step in. Vol target supply will eventually wane as volatility peaks and/or leverage comes down, but they likely remain sellers for the next several days.
Net-net: more supply likely pushes markets lower Tuesday and potentially Wednesday, and buyers will need to see signs of slowing supply and stabilization to come back in. Short-dated implied volatility has likely peaked, while the back end of the vol curve likely rises over the next week and realized volatility will continue to move higher. This is unlikely the turn of the cycle as the selloff is largely technical and positioning driven, and likely not large enough to feed back into the real economy and become fundamental, so dips will be bought after the systematic supply and vol unwinds abate.
QDS came into Monday expecting nearly $5 to $10bn of equity supply from systematic funds, principally annuities as they tend to react quickest to recent increases in realized volatility. That supply likely contributed to the move lower, but it was then compounded by dealers having to hedge their short gamma exposures. QDS estimates that in total dealers likely had to sell $11bn of S&P 500 futures on the way down today.
The VIX market saw the net buying pressure on record. For background on the risks that materialized Monday see If the VIX Goes Bananas, this is What it Might Look Like from July 2017. Details and implications:
The ETPs had to buy 282,000 VIX futures to rebalance their short gamma… needless to say this is the largest VIX buy in history, dwarfing Friday’s previous record of 78,000. Dealers hedging their short gamma exposures likely contributed to VIX futures demand as well.
Most of the rally in VIX futures happened after the 4:00 pm cash close, not leaving a lot of time for investors or the issuers of the VIX ETPs to react.
This move was incredible particularly because VIX and VIX futures were already elevated – and the amount of volatility to buy exceeded QDS estimates (below shows what QDS estimated coming into Monday) and speaks to the size of the short vol exposures in the market:
Whether the inverse ETPs continue to exist tomorrow is up for debate at time of this writing (contact us for details), but for the broader market the implication is clear: the inverse ETPs have effectively delevered down to zero, going from short 230,000 VIX futures to short just 4,000. (note exact numbers will need to be updated to reflect creations / redemptions reported overnight).
On a positive note this means there is much less risk going forward of further vol to buy from rebalancing of these products. On a negative note holders of the inverse ETPs lost $3.4bn as the products went nearly bankrupt and this removes a steady source of volatility supply over the last year.
Futures are down a thousand and Asia is having their balls chopped off, which is child’s play in comparison to what’s in store for me tomorrow morning with my XIV position.
Just a few days ago, I cockily sashayed into the position, promising great fortune to my great, great grandchildren — profiting from the total breakdown in volatility — which has been a given for the past decade — until now.
Starting rather immediately, both SVXY and XIV will trade directly to zero. DO NOT PASS GO!
We played the game in a funhouse of mirrors beset by fiendish clowns and leave with nothing at all — not even our pants. It’s actually poetic to get blown the fuck out in an ETN that has done nothing but trend higher for a decade. Going into Friday’s tape, XIV had a Sharpe ratio of 1.81, which is insanely strong — indicative of a product that doesn’t really shift in standard deviation. It was a simple product, the farmer of the ETF world. And now it’s dead — triggered by a clause that maybe 1% of buyers bothered to research. There is a lesson in here, tucked away deep under all of this chicanery. I am sure Credit Suisse will just redeem the product and issue a new one next week — maybe even under the same ticker symbol.
Last week I featured a chap named Carlos who got wiped the fuck out in Bitconnect. We’re all Carlos now. Watch this video and simply replace the word “Bitconnect” with “XIV” and you’ll know exactly what I looked like last week.
My gameplay for tomorrow is simple: enter the hellscape with guns blazing, sell out of my SOXS position for a quick profit, lick my wounds with XIV, contain losses with other retard positions, allocate cash into something that is going to fucking rip heads off to the upside whenever the market turns higher again.
Futures are chopping dicks off to the downside right now — down by 1,200. European markets, more or less, off by 7%. Asia: fucked. Bitcoin: a memory. A Devil Dog moment fast approaches.
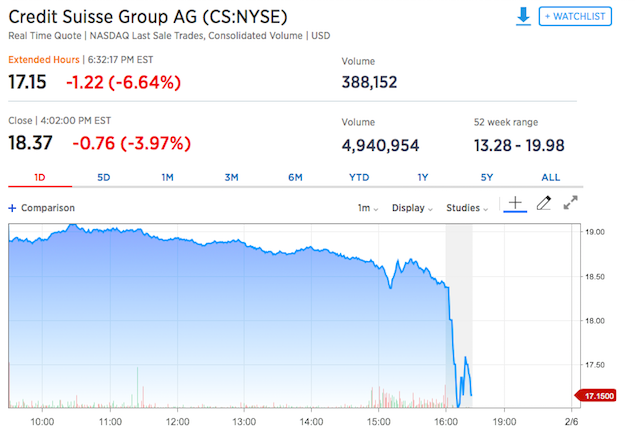
Shares of CS are down nearly 7% in after-hours thanks to the rickety bullshit unfolding in XIV, the inverse volatility ETN — which has been the single best performing ETN over the past 5 years. In what is truly hard to believe, there is a ‘termination’ trigger in this product that permits the underwriter, in this case Credit Suisse, to liquidate the fund in order to prevent a negative equity situation.
What their exposure is to this trade is unclear at this time. One trader has an idea what might be out there and it doesn’t bode well for CS. In after-hours trade, inverse volatility ETNs SVXY and XIV are down by 78% and 85%, respectively.
Larry McDonald, founder of the Bear Traps Report, warned that such a huge spike in volatility could spell similarly large losses for investors in popular inverse volatility notes like Credit Suisse’s XIV, which rises when the VIX falls.
“Positioning in all sorts of VIX ETFs has increased 5-fold in recent years,” McDonald said in an email. “Even a spike in volatility similar to August 2015, would force VIX ETFs to buy an incredulous $37 billion exposure in short-term VIX futures. Such a spike can even get more exacerbated in case liquidity dries up as the market realizes certain structures need to rush in and cover their shorts at whatever the cost.”
McDonald told CNBC that the August 2015 VIX move was roughly 45 percent, while today’s move was double that.
Here’s a CNBCtard attempting to explain the math here, but leaves out the black swan ‘termination’ even that is apparently happening.
I know a lot of people have been hit with this trade. Friends of mine have been emailing me some truly harrowing details about how they took million dollar positions before the bell today. Hopefully, you’re exposure is limited; but judging from experience, I imagine some of you have high exposure to this product. There’s no negotiating with events like this, which is commiserate to Bear Stearns opening up at $2 from Friday’s close at $30. We never had a chance with this thing, closing at $99 — only to trade down sneakily in the after-hours. Like thieves in the night, the people who concocted this product fucked up in a significant manner.
I’ll hold the damned thing and take the loss when the smoke clears. I am writing this off as a total loss, a sharp set back for me — but life has to continue and I will view this set back as another foray into hardship that has served me well in the past.
I am truly sorry to anyone who bought into this God forsaken curse.
UPDATE: What sort of ETF has a termination event that is triggered in the after-hours to absolutely FUCK everyone is owns it? Moreover, how many active managers just got caught with their pants down like me? It’s all fun and games until your fucking ETF goes to zero in the after-hours.
UPDATE: Apparently, there is a termination clause on these VIX products that permits underwriters to liquidate the product in the event of an 80% move in volatility, which would explain the selling. However, and I must admit, this is the worst ETF fuckery I’ve ever seen. I have 10% of my account in this, so I’m guessing I will lose 10% of my account by tomorrow.
NIKKEI futures are -8% now. Other than that, I have no idea how this is possible, but XIV is now trading at $38 in the after-hours, down from $100.
As you know, I am long XIV, even bought more on Friday at $120 — and now it’s down 70% in after hours trade — a move that I cannot explain. I just got back from ordering sushi. I turned on the teevee and saw XIV scrolling on the ticker. I thought this was the result of a reverse split. But then I looked at the long VIX products, and they’re all up 25-30%.
Redpill me on how this is even possible?
As it stands, this will represent my worst percentage loss of my life — an ironic end to a calm market that knew nothing but upside. The very tool that kept order and emotions in check has dislocated from reality, which could lead to a truly harrowing decline tomorrow.
Cramer is sperging out on CNBC because of the Dow gapping lower by 1500. He believes it’s all fake, a byproduct of machines running stocks. While that might be true, you cannot enjoy the fruits of the robot market without enduring its poisons. We are crashing because people aren’t trading stocks, only algorithmic trading.
As such, I find it hard to believe we will not retest those lows. Since I’m already long a bunch of shit, I threw down a hedge in my tactical account, which will be sold tomorrow, buying SOXS — short semis.
You’ve got to stop bitching about the market going down when all we saw was upside for the past year. Come on already with your sanctimonious bullshit, Cramer.
The Dow is off by 800 now. Cramer is mocking people for selling when it was down 1,600, calling them ‘morons.’
So what happens when the Dow retests the lows? Will Cramer apologize?
The Dow is off by 1,500 and sinking fast. This is the largest point drop ever.
VIX is up more than 75% and I am getting lit. However, I do have 20% cash in my quant account and do have some dry powder to buy this catastrophe.
This is margin call selling and it could not have happened on a worse day for Jerome Powell, our new Fed Chair, who is getting absolutely raped on his first day on the job.
FYI: The Market will halt if we drop more than 7%. With less than an hour left in trading, we can only hope for MOAR downside and carnage on an unimaginable scale.
The Dow is off more than 550 points now, bringing losses to a grand total of 1,700 points since the market top on 1/29/18. I know this isn’t the biggest scare you’ve ever seen, but this is a major shift in the character of the market, blowing out on a standard deviation basis, at the same time keeping normies plugged into the matrix hoping for respite, which is assuredly right around the corner.
One thing to consider is we have a new Fed Chair now, Jerome Powell — a fucking lawyer. In other words, he knows literally nothing about the economy and is merely spitting balling this shit for the benefit of Trump.
Market breadth stands at 27% and Amazon is +6. This has to be the least jittery two day 1,200 sell off of all time. Don’t worry kids, I am sure the Fed is gonna help you out soon enough.
I am telling you right now, this market will not bounce until Bitcoin stops going lower. We’re just stuck in one of those retarded trends that is important to investor psyche now. This too shall pass. But you have to understand, many people got sucked into Bitcoins between $16,000-$20,000, myself included. The euphoria was infectious and it spilled into equities and made people fortunes in crypto proxies. Now all of that has ended and the losses in the crypto space are severe.
According to coinmarketcap.com, the entire crypto space is now worth $320 billion, a loss of nearly $500 billion from the top. That’s like the faggots from FB simply vanishing and going right to zero. How would you live with FB at zero?
Pro-tip: you wouldn’t.
Also, the ramifications of the losses in the cryptos could be more systemic than you know. According to a survey done in early January, 18% of people bought Bitcoins with credit cards. How many of those HODLers will actually pay their bills, now that they’ve been wiped the fuck out?
Just guessing here, but I imagine losses to the banks could be in the billions.
Alas, all we have to do is hold on to dear life and all will be good and just again, no?
Everyone is a genius again. I am so pleased to learn that so many people saw the market plunge coming and are now short equities. You know, often times I feel a certain sense of dread, thanks to this whacky world I live in; but after learning about so many of you marker oracles, playing the market like a fiddle, I once again have hope in a bright future for my children.
The past week has been a doozy for stocks and cryptos. Let’s do a cursory review of the biggest losers with market caps above $1 billion.
OSTK -32%, CORT -30%, PRTA -27%, OMI -26%, AKS -24%, GPOR -23%, WFT -23%, EGOV -23%, GES -22%
As fucked up as it sounds, retail has been hit the hardest the past week — off nearly 8% as a group. You’d think the sector got hit enough last year and that tech would recoil from their highs during this sell off. Large cap tech is a mixed bag — with gains posted in AMZN and FB, and 7% losses in GOOGL, BABA, and NVDA.
The best performers, as a group, have been movies and wine/beer. How cliche.
MUH bond yields are NOT higher today, yet stocks are. The 10 yr is down 1bps to 2.84% and the 2 yr is down 3bps to 2.12%, creating a nice big fat spread of 72bps for banks to get rich off from.
Over in crypto world, BTC is struggling to keep its head above $7,000 — as the entire markets drowns in its own hubris.
Volatility is of course spiking — but there are signs of hope. We’re seeing strength in the metals: gold, aluminum, silver, and iron. Also, oil doesn’t look all that bad, at least not dreadful — especially when compared to the banks.
The banks are getting hit hard, naturally because their profit margins are spiking with the yield curve spread widening.
Market breadth is ~+30%, which means there are signs of life. I did purchase more XIV on Friday, so I’ll be hard pressed to do it again. I will, however, make a gigantic purchase of SPY, if and when Exodus closes oversold. We haven’t enjoyed a systemwide oversold signal since March of 2017 in this bastard of a market. In spite of losing money now, I am pleased with the vigor and the verve this market is showing now — coming back to life — playing both sides of the spectrum.
After all, what good is making money if there’s never any risk of losing it?