iBankCoin

Saturday Cinema with Le Fly: Red Dawn (the original)

This movie made me want to kill Russians. Made during the height of the cold war, young Fly, running about the sewers of Brooklyn, was infuriated when he saw this movie. The fucking Russians, with the explicit support of certain men of a latin persuasion, invaded America and took our great freedoms away. I could not believe what I was seeing. Thank heavens  the Wolverines were around to kill all of the invaders.

Also, and I found this to be supremely interesting, at the time this was rated as the ‘Most Violent Film Ever’, by Guinness Book of World Records. In comparison to the depravity shown in theaters today, Red Dawn is like a Saturday morning cartoon.

This was a huge commercial success and for good reason. It makes you want to kill Russians and drink cups of hot blood out from the dying body of deer.

Fin.

Comments »

A Redeemable Day; But Nothing Has Been Resolved Just Yet

I was out of pocket most of the day, running around doing chores. After reviewing the day’s trade, it can only be described as profoundly bullish. With 80% of stocks higher and all sectors in the green, it was a classic melt up day. My bubble basket filled with shit stocks was up 3% for the day, while my GARP index was higher by 1.7%.

For the week, both semis and banks were strong. This is especially important when taking into consideration how dreadful retail has been. Logically, it makes no sense for semis to rally if the consumer’s jaw has been dislocated from his fucking face.

A wide swath of biotechs pressed higher by 10% for the week, also suggestive of a market with a bullish bias.

On the downside were REITs, gold, fucking meat stocks, restaurants, copper, casinos and steel/iron. Empirically, this week was marked by a fear that the Fed would raise rates, which hurt anything with yield, such as bonds, REITs, utilities etc. Also,  investors extrapolated that higher rates could be invective towards inflation hedges,  asserting a King Dollar policy upon the marketplace. As such, China, gold, bonds, oil, retail and anything or anyone sensitive to carrying costs were sold.

This narrative should spell doom for equity markets. As a matter of fact, stocks closed down for the 4th consecutive week, the first time since 2014.

In short, today’s rally was super impressive, almost too perfect. Nothing traded down, not even TLT. The jury is still out as to the near term direction of the market. Moreover, I have a very hard and pernicious bend to my bias.

Comments »

IBC’s Investor’s Boot Camp Time: Sign Up Now

The advantages of having a diverse group of strong willed thinkers writing for the site is especially profound for our readers trying to determine the direction of the markets. For the entirety of 2016, I’ve been a scowling bear, hoping for catastrophe around the bend. On the other hand, The Option Addict has remained steadfast in his belief that we’re going much higher. In many ways, we’re both right. Markets truly were an abomination early on and have rallied since. Over the past month, markets have been dreadful, aside from today’s effervescent trade.

But that’s what makes a market, the diversity of opinions pinging off one another. Unlike many other sites, where one predominant voice echoes  throughout a vacuum, iBankCoin gives you something to think about–almost each and every day.

For the past three quarters, we’ve hosted internet conferences, or webinars rather. We’ve found them to be more efficient at educating, or informing, a wide swath of iBC readers as to the ongoings of the market. Starting Monday, the week of “The Fly’s” birthday, The Option Addict is hosting a boot camp, which will last all week long, encompassing 5 hours of meticulously planned out material to paint a narrative that Jeff believes is the way forward in this market.

I won’t pull punches. Jeff and I have different views about the market. But when it comes to trading in a bull market, no one is better than The Option Addict. I’ve seen him crush upswinging tapes like no one could, over the past decade — from the interwebs. If you’re a grizzly bear like me, pissed off at all the kids playing ball on your yard, I entreat you to sign up for the Boot Camp too. Being able to change an opinion, or at least research an opposing view, is the very foundation of what makes a great investor.


I look forward to hearing Jeff’s ideas next week. I hope to see you there too.


Here is the link to the Boot Camp sign up page.

Comments »

David Faber vs The Wall Street Journal: Fight!

The petulant knaves at the Wall Street Journal are having their quinoa salads eaten for them, by none other than the illustrious D. Faber. The master of all scoops, Faber, is taking the WSJ to task for their ‘sources’ wrong information in regards to the Yahoo bids. The Journal said the bids were coming in very low; so low, it was an abomination to all of mankind–sending shares of YHOO appreciably lower this morning.

Faber’s sources, who have proven to be of the highest quality over the years, likened the Journal’s story as hogwash and said it was outright ‘wrong.’

Shares of YHOO have recovered some since then. It is time for the WSJ to issue a restatement and shut up about the whole Yahoo bidding process. Marissa Mayer needs to golden parachute the fuck out of that place a very wealthy woman, indeud.

Comments »

The NBA is a Generational Short and so is Footlocker

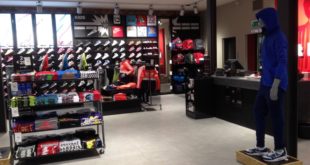
When was the last time you’ve been to one of these stores? Talk about absurdity. More than 80% of the real estate is dedicated to stuff no one wants or buys. They sell all different types of NBA gear and cheesy Nike shirts with infantile slogans on them. Their sneakers are overpriced, wholly dependent upon Nike. For the most part, Footlocker has ignored Underarmour.

Essentially, Footlocker is a proxy for the NBA. I know ratings were up this year. But that was only because of the Warriors magical season. The overarching trend for ratings is lower. The attendance growth is lackluster and unimpressive, given the immense media dedicated to this sport.

Back in April, I posted this quick note about FL being a short. I’ve been meaning to complete my research on it, but have been too busy as of late.

image

This company caters to an urban audience, whose median incomes have gone nowhere over the past decade. However, the price for their ridiculous, made in a Vietnamese Thai sweatshop, sneakers have soared. Some of these rubber shits sell for upwards of $200 now. It doesn’t take a genius to figure out this dichotomy between price point and target customer is unsustainable.

Since 2012, the market has assigned a very premium valuation to FL, more than 40% higher than historical averages. Yet, looking at today’s earnings, growth is slowing.

Reports Q1 (Apr) earnings of $1.39 per share, excluding non-recurring items, in-line with the Capital IQ Consensus of $1.39; revenues rose 3.7% year/year to $1.99 bln vs the $2 bln Capital IQ Consensus.
First quarter comparable-store sales increased 2.9 percent. Company’s gross margin rate remained stable year-over-year at 35.0% of sales.
“We are focused on productivity as we work to drive top line sales, and we remain confident that we can achieve a mid-single digit comparable sales gain and a double-digit earnings per share increase for 2016.” (FY16 EPS Capital IQ consensus +10.7% YoY).

image

image

image

Revenue growth stands at 3.7%. They are tethered to the hip to a sport that has lost momentum and is in decline. Their main product has inflated in price to the point that it attracts criminal activity and in some cases murder. Demographically, the company is fucked, based on wage malaise and sneaker inflation. The majority of their real estate is dedicated to selling jackass Jerseys and NBA paraphernalia.


image

Just based off historical metrics, this stock should be 40% lower. But the problems at FL are much deeper than valuation. They’re tethered to a sport in decline, one that might look very bleak 10 years hence. I have no position in FL and only enjoy, as an avocation, to see it trade lower.

NOTE: This is a mall based retailer, which is a huge negative unto itself, due to drastically declining foot traffic and sales at these brick and mortar relics.


UPDATE: During FL’s conference call they revealed Q1 basketball comps were down mid single digits.

Comments »

A Look at the Deterioration Over the Past Month

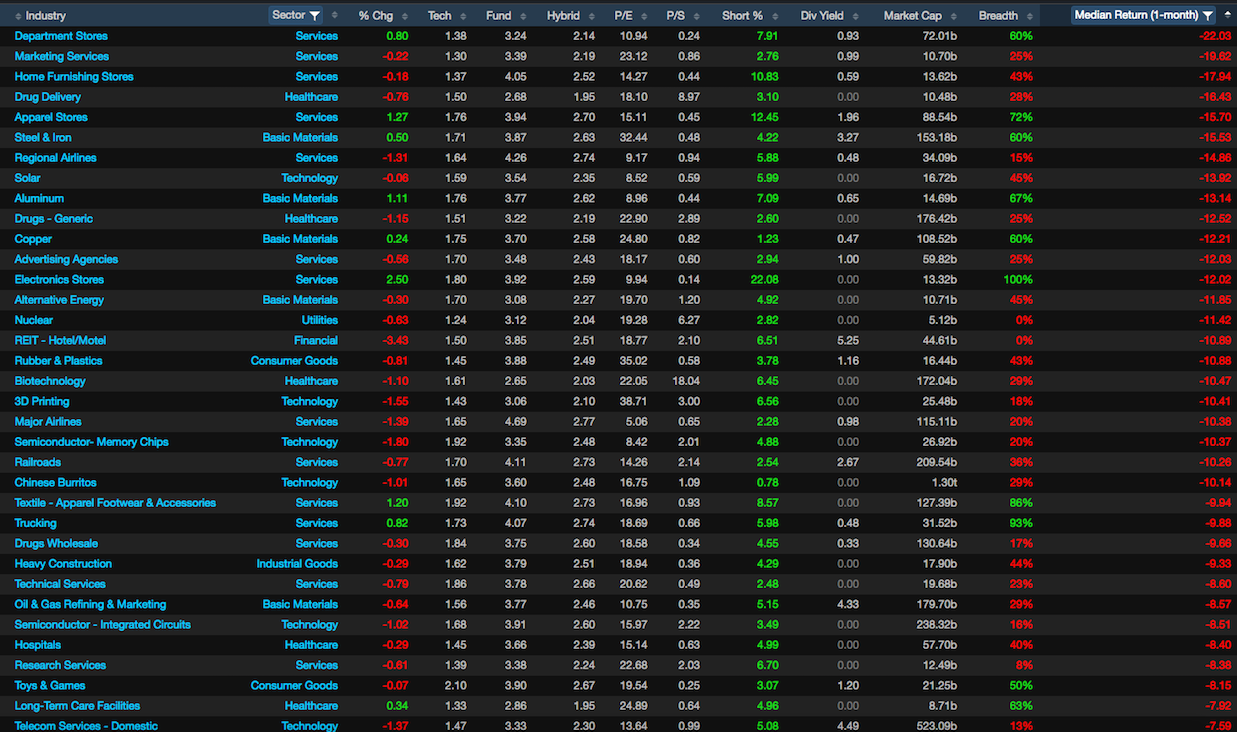
There seems to be a bit of a disconnect between reality and fiction, circulating about the interwebs. Just because the market went up in March through mid April doesn’t mean it has yielded positive returns over the past month. A closer look at the recent price action spells out vast deterioration over a wide swath of sectors.

Let’s ferret a few of these out, shall we?

These are the median returns for whole industries over the past 30 days, courtesy of Exodus.
Industries

On a micro-level, the price action has been nothing short of deleterious.

Here are some standouts.

LC -54%
ENDP -49%
CHK -36%
FOSL -34%
SHLD -34%
PCRX -33%
SCTY -33%
X -33%
BITA -32%
SQ -31%
GPRO -31%
JWN -29%
VALE -28%
M -25%

Mega cap
AAPL -11%
GILD -17%
CX -11%
SBUX -10%
BHP -13%
LFC -17%
BIDU -13%
AMX -20%
TGT -19%

Hardly inspiring, wouldn’t you agree?

To be fair to the argument, there have been winners. Here are some standouts, which represents the current leadership in the market.

NGL +57%
AMD +44%
TEGP +37%
ONCE +34%
BGS +29%
GNW +29%
Z +22%
NVDA +20%
WMB +19%

Mega cap

AMZN +11%
MNST +15%
BSX +12%
CHTR +11%
VMW +14%
EA +11%
NTES +16%

The losers of -10% or more, whose market caps are greater than $1 billion, outstrip the winners of +10% or more with a 3:1 ratio.

Comments »

Chris Johnson’s Warning: ‘2,040 is the Line of Demarcation’

Technician and CEO from JK Investment Group believes 2,040 on the S&P is the ‘line of demarcation’ for the bulls. If we trade down below it with vigor, he thinks the selling could intensify. In addition to trying to scare people with all of that, he delved into other forms of technical analysis witch-craftery to make his case against stocks.

I respect those who partake in the consumption of technical analysis theories. Although not a big fan of it myself, the plebian class lives and dies by it, as a method to fastidiously analyze stocks without having to undergo the nuisance of having to read earnings reports and undertake balance sheet analysis. If this Mr. C. Johnson is correct, markets might be at the tipping point for much lower prices, or a supreme support level from which new highs could be launched from.

Comments »

The Gap’s Earnings Were So Bad, the Stock is Rallying


This company is so bad, it’s good. Earnings are down, missing earnings expectations by large mountain ranges. Margins are horrid. Universally, their fashion choices are an abomination. Yet, in the after hours, thus far, shares are rising by 3.6%. All of this can change, naturally.  But it’s worth noting that the price action, in the face of abysmal news, is exceedingly bullish.

Maybe people are happy to see 75 wretched stores closing?

Bottoms are forged in the pits of hell, not the harems in heaven (extra 72 virgins).

Via Briefing.com

  • Reports Q1 (Apr) earnings of $0.32 per share, in-line with the Capital IQ Consensus of $0.32; revenues fell 6.0% year/year to $3.44 bln vs the $3.54 bln Capital IQ Consensus.
  • Warned on May 6: Preannounced EPS $0.31-0.32 vs. $0.45 consensus; rev $3.44 bln vs. 3.54 bln consensus; comps -5% (-3% Gap, -11% Banana Republic, -6% Old Navy).
  • Co is not reaffirming its earnings per share guidance for fiscal year 2016 ($2.20-2.25). The company noted that the current consensus earnings per share estimate of $1.92 falls within a reasonable range of potential outcomes, excluding restructuring impacts from its store closure and streamlining measures. However, the company also noted that trends in the apparel retail environment would need to improve from the first quarter of fiscal year 2016 in order to achieve this estimate.
  • The company will report May sales on June 2, 2016.
  • As part of Gap Inc.’s continued commitment to better position the company for long-term growth, the co has announced the following measures to better align talent and financial resources against its most important priorities:
    • Focus on geographies with the greatest potential. The company remains committed to growing its brands in regions where it has a structural advantage and the greatest opportunity to gain market share. As part of this effort, Old Navy will strategically shift its focus to markets most favorable to the brand’s growth, resulting in the closure of its fleet of 53 stores in Japan in fiscal 2016. Old Navy’s near-term growth ambitions will be anchored in North America, including its most recent debut of company-operated stores in Mexico, as well as China and its global franchise operations. Additionally, the company expects to close select dilutive Banana Republic stores, primarily internationally, in fiscal year 2016. In total, the company expects to close about 75 stores related to these measures.
    • Streamline its operating model. The company will take steps to create a more efficient global brand structure, enabling its portfolio of brands to more fully leverage its scale advantage and move even faster in anticipating and responding to the ever-changing environment and needs of customers.
  • The company estimates that together these measures will result in annualized pre-tax savings of about $275 million and operating margin improvement of nearly 2 percentage points. The company estimates an annualized sales loss of about $250 million associated with the store closures and expects to recognize restructuring costs in fiscal 2016 of about $300 million pre-tax

Comments »

Markets Pare Losses, Trades Down 0.5% in Apathetic Trading

Let’s recap the past month of trade, a month which I predicted would mark the top in the broader indices dating back to February.

S&P is -3%.

China is -10.7%

Japan -4.4%

Germany -6.4%

France -5.5%

I think it’s fair to say, thus far, that my predictions for a May correction, stretching all the way towards the end of the time/space continuum have proven to be sagely.

Markets closed down a little less than 100. It would’ve been far worse, had it not been for the energetic gains in WMT. All sectors were weak, with exception to the dividend rich utilities. In a way, today’s drop was keenly representative of a classic risk off day. The price action has been, hitherto, cordial and methodical in its effervescent climb towards new highs. Oil is up more than 50% from the lows and a vast swath of commodity related stocks are up triple digits. It’s very easy to sit here, from the sidelines, and prognosticate doom. Bear in mind, aside from my small TLT position, I have no vested interest in seeing stocks trade lower. It isn’t to my benefit to see the overwhelming majority of my readers and members of Exodus to lose money in equities. Rather, I feel an intense duty to bring forth evidence, to an otherwise catatonic and very sleepy audience, that things are changing for the worse. The fabric from which this rally was built upon is being destroyed. In my estimation, it’s only a matter of time before the seams give way to the pressure and markets resume the treacherous path it forged back in February.

nasdaq

Comments »

Cashin: ‘The Market Isn’t Happy with the Fed’

A. Cashin, chief iced cube marinator, doesn’t believe the Fed will hike rates either. Are you seeing a pattern here?

Furthermore, he cites emerging markets as something of a chief concern to investors here in ‘senior’ markets. The sell off is due to investors’ displeasure with the current Fed head speeches, all point towards a live meeting in June.

Comments »