With so many Russian hackers out there wreaking havoc, you’d think there would be demand for these piece of shit software companies who take advantage of weak minded morons running IT budgets for fortune 500 companies. I can recall a conversation that I had with an executive at Bofa/Merrill, who was in charge of a $500m per annum IT budget, who declared the cyber security sector ‘a fucking scam’ — bitching about prices being artificially and predatorily high.
When he took the role, he canceled all contracts and was working on crafting new ones — at much lower prices. That was two years ago.
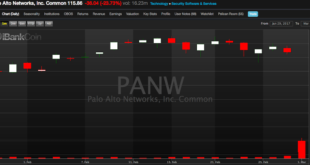
Since then, $FEYE is down 75%, $VDSI -48%, $CUDA -37%, $QLYS -24% and today’s leader to the downside, $PANW -18%.
PANW just warned and guides lower. The party is, inexorably, fucking over for them.
Source: UBS
Comments »UBS downgrades PANW to Neutral from Buy and raises their tgt to $160 from $130. Amid a tough set-up, an across the board weak F2Q marked PANW’s 3rd set of inconsistent results in the LTM, ascribed to broad-based, go-to-market issues, aggravated by unforeseen purchasing pauses consequent to PANW’s recent slate of new product releases. While lower sales productivity and poor pipeline conversion were specific culprits cited, firm thinks investors are increasingly unlikely to dismiss competitive factors (CSCO’s security growth has been stable and respectable in mid/high-teens; peers CHKP, FTNT capped off strong CY16s) from here on. What has now emerged as a pattern of inconsistent execution and stark decel optics, firm sees PANW’s heretofore premium valuation as likely impaired, with a re-rating contingent on multiple Qs of growth reacceleration and “clean” results. As such, they are moving to the sidelines as they see the stock range-bound until the execution uncertainty clears.