Too bad everyone didn’t read the fucking prospectus. I bet some of you swing traders out there are trading stocks today. Before doing so, you better go read those prospecti — for you never know what you’re gonna find inside.
Here’s Cramer finding it interesting that such a devilish instrument, such as XIV, exists.
Let this be a lesson to all of you out there, courtesy of Credit Suisse. Do your homework next time, else end up with zero assets in your brokerage account.
NANEX has a hilarious tool that grades liquidity. According to their stats, we’re not at ‘Lord of the Flies’ tier liquidity.
By all accounts, markets feel broken now, quickly and violently moving between gains and losses. At one point we went from -700 on the futures to a +400 in the opening minutes of trade. I would call that fuckery of extreme proportions.
On top of that, Fidelity and other online brokerages have been down all morning, effectively stopping advisors and retail from accessing accounts to make adjustments. This is probably why markets ripped higher in the morning. There was no one there to sell because all of the fucking platforms were down.
I am paralyzed here and not doing a thing. I have no idea where the next direction is for the day and would rather do nothing than sell into this panic or buy into this lack of liquidity. From my vantage point, I already lost the day — long 10% of my tactical account in XIV. I don’t feel like compounding that loss and error with emotional driven trades, so I’ll probably do nothing.
My Quant account is higher by 0.4%, all of which are mega caps. There is a certain calmness to having a quantitative strategy that correctly adjusts with the market. While I do not believe I can withstand the barrage of selling and actually make money in a down tape using a systematic approach, I do believe I can and will outperform — which is the point.
My chief tells are OSTK and Bitcoin and how that might have a ripple effect into risk acceptance.
In case you were up all night worrying about Credit Suisse and their exposure to volatility, do not worry, for they are completely hedged and haven’t lost any money in their FUCKING DEATH TRAP of an ETN XIV — which is slated for execution from the natural world on 2/20/18.
Wall Street experts now warn to read those pesky little prospectuses before making swing trades in these bastard products. Because, next thing you know, you lean into one of these things for a quick soiree into volatility at $100 and you wake up with this motherfucker at zero.
Any god damned questions? Read the fine print, son, otherwise you’re nuts might be mashed into paste.
Via CNBC:
Credit Suisse said it will end trading in a security that traders said was exaggerating movements in volatility futures markets and even the overall stock market.
The last day of trading for VelocityShares Daily Inverse VIX Short-Term exchange-traded note (XIV) will be Feb. 20, according to an announcement from Credit Suisse. It is triggering this liquidation because the product could not keep up with the scenario it was supposed to track: a calm market.
The XIV security, which had fallen roughly 85 percent in after-hours trade, had been halted pending this news early Tuesday. The security is supposed to give the opposite return of the Cboe Volatility index (VIX), the market’s widely followed turbulence gauge.
Multiple exchange-traded securities that are also supposed to be bets on calm markets were also halted Tuesday morning after losing the majority of their value overnight.
Credit Suisse said late Monday ET that the XIV’s plunge would have no “material impact” on the Swiss bank itself, though a source familiar with the news told CNBC that the investment bank was considering redemption of the ETN but had yet to make a final decision.
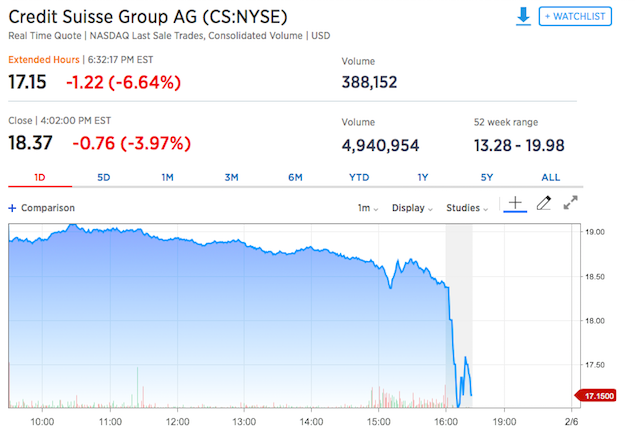
Shares of Credit Suisse slumped nearly 4 percent on Tuesday morning amid the wider sell-off in equity markets.
In case you missed the prospectus for XIV, just prior to picking up some shares at your discount house brokerage account before the bell, here’s the print you would’ve loved to have read.
As explained in the VelocityShares prospectus, the company can elect to “accelerate” any of their ETNs, liquidating them early.
“If the price of the underlying futures contracts increases by more than 80 percent in a day, it is extremely likely that the Inverse ETNs will depreciate to an Intraday Indicative Value or Closing Indicative Value equal to or less than 20 percent of the prior day’s Closing Indicative Value and will be subject to acceleration,” read the company prospectus. “If an Acceleration Event occurs at any time with respect to any series of the ETNs, we will have the right, and under certain circumstances as described herein the obligation, to accelerate all of the outstanding ETNs of such series.”
See folks, you have only yourselves to blame. The product worked perfectly fine. There was nothing awry with its behavior. You should expect to lose 100% of your investment between the after-hours session of 4:05pm to 4:45pm, as underwriters cover their OTC volatility contracts, effectively ‘terminating’ your investment. If, by chance, you happen to be long XIV, it’s tough luck — being at the wrong place at the wrong time. After all, Credit Suisse did warn you it could happen. Sure, perhaps they might’ve asked Nasdaq to halt trading last night, in order to prevent others from buying ‘dips’ in the after-hours session — but that was probably just an honest mistake and you can’t really hold it against Credit Suisse — since it’s all there in the prospectus. I swear, it’s all there — every single bad thing that has happened today was there, even the notion that a product trading at $100 could open up the next trading day at zero because it had been terminated, naturally.
Oh, one more thing before I go, UVXY is -31% today and volatility is dropping fast. The otherwise of that UVXY trade would’ve been XIV. The irony here, as the Dow moves from -700 to +400 for the session, is that had XIV chicanery not taken place last night, it would’ve been a winner today.
Now with the benefit of hindsight, one guest after the next is visiting CNBC and Bloomberg to show the world what assholes they are, by being condescending pricks — maligning ‘retail’, which is just another word for idiot trader, for getting caught in a black swan event long inverse volatility products SVXY and XIV.
Having spend nearly 2 decades on Wall Street, I am very familiar with the snobbery on trading desks or even from the simple assholes managing money for private clients. But it takes a special sort of asshole to go on teevee and flippantly dismiss those who just got ruined in inverse volatility products — equating their loss as non-events — chastising them for not reading the fine print in the prospectuses. I know 1 person out of 100 who actually reads these things. Please, go fuck yourself.
Here we have Dean Curnutt from Macro Risk Advisors saying the blowing up of these products was a ‘good thing’ for the Fed.
Watch this tone deaf man be an asshole on live teevee.
And here’s another one, Tim Freeman from Elevation LLC saying everything is wonderful and behaving as it should. This has a certain Baghdad Bob flair to it — some slickster calmly telling people everything is good, when in fact the fucking world is melting down around him. Wonderful.
And then Wall Street wonders why Main Street hates their guts.
Do not be fooled by the futures markets on some of your commercial outlets. There is a significant ‘fair value‘ of more than 350 points that needs to be accounted for and most people aren’t aware of this. After FV, Dow futures are -680, Nasdaq -120.
The VIX markets have blown up after years of complacency, spending most of its time in the low double digits. Early going, VIX is trading at 50, which has laid waste of inverse vol ETFs, such as XIV, ZIV, and SVXY. What is being talked about by people on Wall Street this morning is the over-the-counter vol markets or ‘shadow volatility markets’ — which has been used to sell premium in volatility, boosting returns for hedge funds all around the world. The ramifications of this trade blowing up aren’t known yet, in spite of the fact that Credit Suisse says they’ve got the whole trade covered and is entirely hedged. There are many others who aren’t hedged and are now naked volatility into a market screaming lower, blowing out standard deviations — putting the fear of the devil into traders.
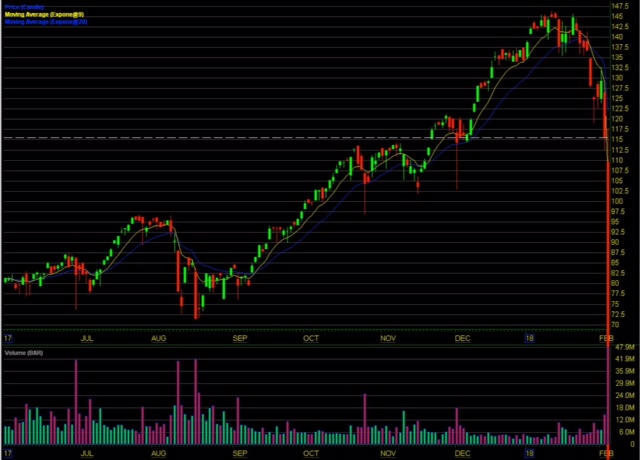
The downside move in XIV, which was triggered by a termination event that caused Credit Suisse to buy volatility between 4-4:15pm during yesterday’s trading session, literally broke charts.
What people will be watching next is the plumbing of the system, credit default swaps, bond yields, and especially the junk markets — which have also been used as a place to achieve easy returns in a non-volatile market. Now with the OTC vol market blowing up, in addition to the retail vol ETNs, there could be ancillary victims that may pop up in these areas.
WTI is -1.2%, Gold +0.1%, Dollar +0.3% v Euro, and BTC -10%.
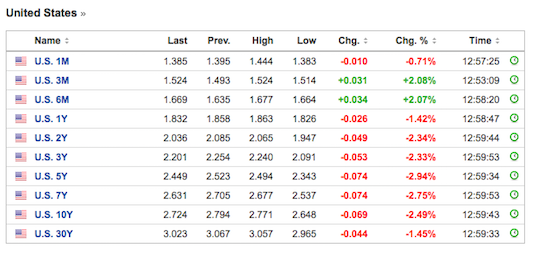
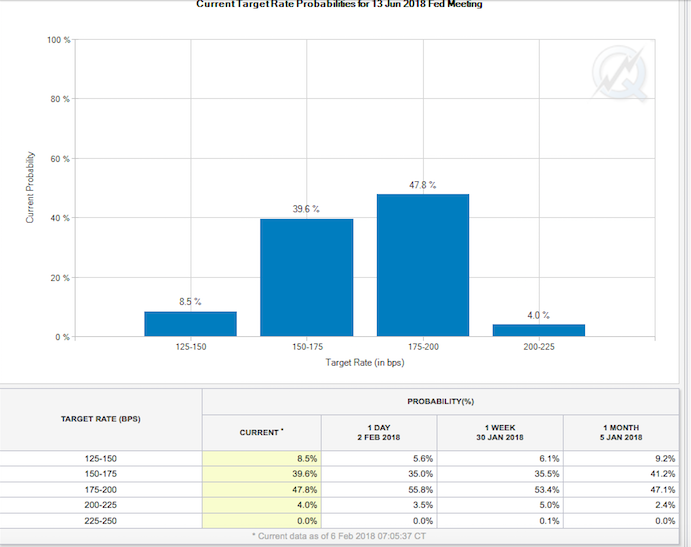
Bond yields are going lower and the market is no longer pricing in 4 hikes, but 2.
Zerohedge has a research note by Morgan Stanley up, discussing the debacle.
Some of the selling on Monday likely reflected investors anticipating systematic supply on Tuesday – this means the $30 to $35bn QDS estimates for sale Tuesday (detailed below) may net down to $15 to $25bn. This is still enough to have negative impact on markets though and will be compounded by dealer short gamma positions.
Anticipation of further supply later in the week from both annuities and risk parity funds could bring in more fast money sellers Tuesday.
The near bankruptcy of the inverse VIX ETPs will be a very negative headline, and the several billion dollar loss for holders, largely retail, will scare some out of the market or force liquidations of other products to raise cash.
Institutional vol sellers will likely cover exposures as well in the coming days and weeks. While these positions will not take losses on the same scale of the VIX ETPs (because they are generally scaled more conservatively) unless there is a quick snap back many investors will likely take down risk, supporting implied volatility in the process.
On the positive side, much of the short gamma exposure in the VIX market has been wiped out, leaving less risk of a further volatility spike from here.
Investors were not in panic mode despite the selloff, as this move has ‘only’ wiped out one month of P/L. As noted earlier in one sense this is good as it might slow discretionary supply, but it also highlights that discretionary investors are still very long risk and could easily turn sellers.
Who are the incremental buyers here? Macro funds betting on the vol unwind that has now happened could cover and turn buyers, but for real support the market needs deep pocket asset allocators to step in. Vol target supply will eventually wane as volatility peaks and/or leverage comes down, but they likely remain sellers for the next several days.
Net-net: more supply likely pushes markets lower Tuesday and potentially Wednesday, and buyers will need to see signs of slowing supply and stabilization to come back in. Short-dated implied volatility has likely peaked, while the back end of the vol curve likely rises over the next week and realized volatility will continue to move higher. This is unlikely the turn of the cycle as the selloff is largely technical and positioning driven, and likely not large enough to feed back into the real economy and become fundamental, so dips will be bought after the systematic supply and vol unwinds abate.
QDS came into Monday expecting nearly $5 to $10bn of equity supply from systematic funds, principally annuities as they tend to react quickest to recent increases in realized volatility. That supply likely contributed to the move lower, but it was then compounded by dealers having to hedge their short gamma exposures. QDS estimates that in total dealers likely had to sell $11bn of S&P 500 futures on the way down today.
The VIX market saw the net buying pressure on record. For background on the risks that materialized Monday see If the VIX Goes Bananas, this is What it Might Look Like from July 2017. Details and implications:
The ETPs had to buy 282,000 VIX futures to rebalance their short gamma… needless to say this is the largest VIX buy in history, dwarfing Friday’s previous record of 78,000. Dealers hedging their short gamma exposures likely contributed to VIX futures demand as well.
Most of the rally in VIX futures happened after the 4:00 pm cash close, not leaving a lot of time for investors or the issuers of the VIX ETPs to react.
This move was incredible particularly because VIX and VIX futures were already elevated – and the amount of volatility to buy exceeded QDS estimates (below shows what QDS estimated coming into Monday) and speaks to the size of the short vol exposures in the market:
Whether the inverse ETPs continue to exist tomorrow is up for debate at time of this writing (contact us for details), but for the broader market the implication is clear: the inverse ETPs have effectively delevered down to zero, going from short 230,000 VIX futures to short just 4,000. (note exact numbers will need to be updated to reflect creations / redemptions reported overnight).
On a positive note this means there is much less risk going forward of further vol to buy from rebalancing of these products. On a negative note holders of the inverse ETPs lost $3.4bn as the products went nearly bankrupt and this removes a steady source of volatility supply over the last year.
Futures are down a thousand and Asia is having their balls chopped off, which is child’s play in comparison to what’s in store for me tomorrow morning with my XIV position.
Just a few days ago, I cockily sashayed into the position, promising great fortune to my great, great grandchildren — profiting from the total breakdown in volatility — which has been a given for the past decade — until now.
Starting rather immediately, both SVXY and XIV will trade directly to zero. DO NOT PASS GO!
We played the game in a funhouse of mirrors beset by fiendish clowns and leave with nothing at all — not even our pants. It’s actually poetic to get blown the fuck out in an ETN that has done nothing but trend higher for a decade. Going into Friday’s tape, XIV had a Sharpe ratio of 1.81, which is insanely strong — indicative of a product that doesn’t really shift in standard deviation. It was a simple product, the farmer of the ETF world. And now it’s dead — triggered by a clause that maybe 1% of buyers bothered to research. There is a lesson in here, tucked away deep under all of this chicanery. I am sure Credit Suisse will just redeem the product and issue a new one next week — maybe even under the same ticker symbol.
Last week I featured a chap named Carlos who got wiped the fuck out in Bitconnect. We’re all Carlos now. Watch this video and simply replace the word “Bitconnect” with “XIV” and you’ll know exactly what I looked like last week.
My gameplay for tomorrow is simple: enter the hellscape with guns blazing, sell out of my SOXS position for a quick profit, lick my wounds with XIV, contain losses with other retard positions, allocate cash into something that is going to fucking rip heads off to the upside whenever the market turns higher again.
Futures are chopping dicks off to the downside right now — down by 1,200. European markets, more or less, off by 7%. Asia: fucked. Bitcoin: a memory. A Devil Dog moment fast approaches.
Shares of CS are down nearly 7% in after-hours thanks to the rickety bullshit unfolding in XIV, the inverse volatility ETN — which has been the single best performing ETN over the past 5 years. In what is truly hard to believe, there is a ‘termination’ trigger in this product that permits the underwriter, in this case Credit Suisse, to liquidate the fund in order to prevent a negative equity situation.
What their exposure is to this trade is unclear at this time. One trader has an idea what might be out there and it doesn’t bode well for CS. In after-hours trade, inverse volatility ETNs SVXY and XIV are down by 78% and 85%, respectively.
Larry McDonald, founder of the Bear Traps Report, warned that such a huge spike in volatility could spell similarly large losses for investors in popular inverse volatility notes like Credit Suisse’s XIV, which rises when the VIX falls.
“Positioning in all sorts of VIX ETFs has increased 5-fold in recent years,” McDonald said in an email. “Even a spike in volatility similar to August 2015, would force VIX ETFs to buy an incredulous $37 billion exposure in short-term VIX futures. Such a spike can even get more exacerbated in case liquidity dries up as the market realizes certain structures need to rush in and cover their shorts at whatever the cost.”
McDonald told CNBC that the August 2015 VIX move was roughly 45 percent, while today’s move was double that.
Here’s a CNBCtard attempting to explain the math here, but leaves out the black swan ‘termination’ even that is apparently happening.
I know a lot of people have been hit with this trade. Friends of mine have been emailing me some truly harrowing details about how they took million dollar positions before the bell today. Hopefully, you’re exposure is limited; but judging from experience, I imagine some of you have high exposure to this product. There’s no negotiating with events like this, which is commiserate to Bear Stearns opening up at $2 from Friday’s close at $30. We never had a chance with this thing, closing at $99 — only to trade down sneakily in the after-hours. Like thieves in the night, the people who concocted this product fucked up in a significant manner.
I’ll hold the damned thing and take the loss when the smoke clears. I am writing this off as a total loss, a sharp set back for me — but life has to continue and I will view this set back as another foray into hardship that has served me well in the past.
I am truly sorry to anyone who bought into this God forsaken curse.
UPDATE: What sort of ETF has a termination event that is triggered in the after-hours to absolutely FUCK everyone is owns it? Moreover, how many active managers just got caught with their pants down like me? It’s all fun and games until your fucking ETF goes to zero in the after-hours.
UPDATE: Apparently, there is a termination clause on these VIX products that permits underwriters to liquidate the product in the event of an 80% move in volatility, which would explain the selling. However, and I must admit, this is the worst ETF fuckery I’ve ever seen. I have 10% of my account in this, so I’m guessing I will lose 10% of my account by tomorrow.
NIKKEI futures are -8% now. Other than that, I have no idea how this is possible, but XIV is now trading at $38 in the after-hours, down from $100.
As you know, I am long XIV, even bought more on Friday at $120 — and now it’s down 70% in after hours trade — a move that I cannot explain. I just got back from ordering sushi. I turned on the teevee and saw XIV scrolling on the ticker. I thought this was the result of a reverse split. But then I looked at the long VIX products, and they’re all up 25-30%.
Redpill me on how this is even possible?
As it stands, this will represent my worst percentage loss of my life — an ironic end to a calm market that knew nothing but upside. The very tool that kept order and emotions in check has dislocated from reality, which could lead to a truly harrowing decline tomorrow.
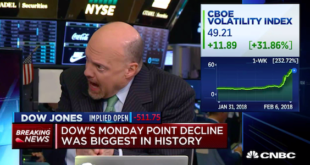
Cramer is sperging out on CNBC because of the Dow gapping lower by 1500. He believes it’s all fake, a byproduct of machines running stocks. While that might be true, you cannot enjoy the fruits of the robot market without enduring its poisons. We are crashing because people aren’t trading stocks, only algorithmic trading.
As such, I find it hard to believe we will not retest those lows. Since I’m already long a bunch of shit, I threw down a hedge in my tactical account, which will be sold tomorrow, buying SOXS — short semis.
You’ve got to stop bitching about the market going down when all we saw was upside for the past year. Come on already with your sanctimonious bullshit, Cramer.
The Dow is off by 800 now. Cramer is mocking people for selling when it was down 1,600, calling them ‘morons.’
So what happens when the Dow retests the lows? Will Cramer apologize?
The Dow is off by 1,500 and sinking fast. This is the largest point drop ever.
VIX is up more than 75% and I am getting lit. However, I do have 20% cash in my quant account and do have some dry powder to buy this catastrophe.
This is margin call selling and it could not have happened on a worse day for Jerome Powell, our new Fed Chair, who is getting absolutely raped on his first day on the job.
FYI: The Market will halt if we drop more than 7%. With less than an hour left in trading, we can only hope for MOAR downside and carnage on an unimaginable scale.