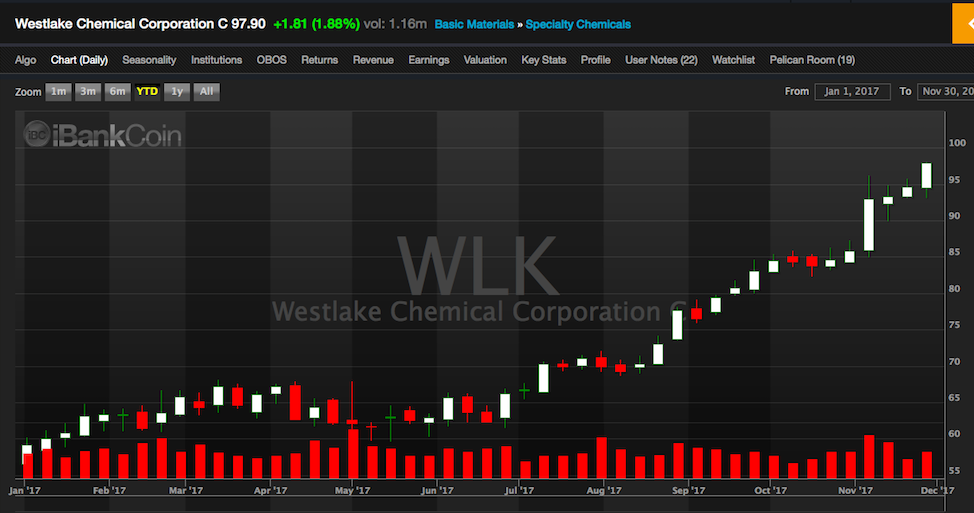
The trades that I show here is nothing short of river boat gambling. No investor of serious thought would ever subject himself to the pangs of HMNY and UVXY in one portfolio, at the same time. But that’s my gambling personal money and I can do as I like with it. But some of you might think this is a reasonable way to invest and that is something I’ve been trying to change for the past two years here, gearing more towards a quantitative strategy by using Exodus.
Hopefully you’ve enjoyed some great gains this year — but it’s time to analyze the quality of said gains.
Here’s how you do it.
You must analyze the quality of said returns for risk. You can best do this by examining the Sharpe ratio for your portfolio. What the sharpe ratio will tell you is the level of degeneracy by which you conducted yourself all year to get said gains. As an advisor or self directed investor, it’s in your best interest to gear an investment plan with limited drawdowns and volatility.
Eventually, I will build this all into Exodus. For now, you need to find the standard deviation of your positions, which is, essentially, the distance from the mean, and then calculate the Sharpe per stock, which is the excess returns minus risk free returns divided by the standard deviation. To account for position weightings, I suggest using a multiplier from the mean size of your positions and then you’ll have a good idea how you really stack up.
This approach is only useful for long term portfolios that haven’t been traded. To attain the Sharpe for an active account, you’ll need to get the monthly returns of your accounts, minus excess returns, divided by the standard deviation for the entire portfolio.
Why do this?
Because when the market shits the bed at some point, you’re gonna want to know how risky your stocks are.
For example, CMI is up handsomely this year by 22%, yet sports a Sharpe of just 0.82 (anything under 1 is shit). On the other hand, PayPal sports a Sharpe of 3.27 to go with its 90% returns, implying its gains have been calm and genteel. The risk adjusted returns for PayPal vs CMI are of no comparison. If your portfolio is stacked with names like CMI, you’re in for a severe raping when the market turns lower.
This is merely the statistics portion of the portfolio. In order to get the investable ideas, I’m a huge believer in fundamentals and using strategies to find the very best names to invest in. I’ve been doing this on a weekly basis in Exodus and the gist of it is to find high growth companies trading at a reasonable valuation, chasing alpha — meaning high returns. This is a delicate thing to do, since high returns usually accompanies risk — but if you’re mindful of your Sharpe, you’ll be ok.
The first thing you should do is find the best market cap quintile and get exposure to it. For the past quarter, the $1-5 billion quintile performed best. However, placing all of your money in such small capped stocks is too risky — so you might want to mix in some mega caps for diversification.
Remember, the death knell for your investment career isn’t underperformance, but drawdowns. You must avoid them like the Black Death and make sure that your portfolio can withstand a bad market.
After you do that, then figure out a way to hedge your downside. I prefer to do this though risk off assets, like treasuries or possibly gold — depending on their performance vs the SPY.
Comments »