iBankCoin

$AMZN Beats Estimates, Offers Hilarious Guidance

When you literally rule America with an iron fist and control Xmas, you can do and say whatever the fuck you want.

Amazon just crushed numbers and gave guidance that can only be construed as #YOLO.

Amazon sees Q3 operating income of $50-650 million mln vs ~$800 mln estimate; revs $31.0-33.5 billion bln vs $31.7 bln consensus

Amazon Q2 operating income $1.3 bln vs. $375-975 mln guidance and $900 mln estiamte; rev $30.4 bln vs. $28-30.5 bln guidance and $29.6 bln CIQ Consensus.

Any other company publishes this shit and the stock gets raped for 30% in the after hours.

AMZN is higher by 2%.

Comments »

Markets Shrug Off Headwinds, Sail into the Sunset at Record Highs

This is a repeating theme. No matter how bad oil looks or the data out of China gets, there will always be robots out there buying XOM and CAT, especially since those are Dow 30 components. Both Italy and Spain dropped like fucking anvils, off by 2%. Yet, here we are now and stocks closed out the day higher, +5 on the SPY and +15 on the NASDAQ.

Oil has been tossed into the sewers, off by 14% since last month–but no one cares.

Fed interested in hiking rates?

No one gives a shit.

If you stand back and think about all of these horrible things, you’ll never invest a single penny in the market. The bull case for stocks, especially since 2009, is and will continue to be succored by the fact that ‘there’s nowhere else to put money.’ What a wonderfully monstrous reason to invest earned wages into markets. A fucking casino.

Speaking of which, revenues in Macau might’ve bottomed. Keep an eye out for those WYNN numbers to confirm.

Comments »

Broke Ass Mountain: American Home Ownership Drops to 1965 Levels

What sort of fucking recovery is this? How can the market be at new, fresh, record highs, but home ownership sucking the dick off 1965 levels, a time and place that was both reprehensible and disgusting in American history?

For Q2, ownership dropped to 62.9%, matching levels not seen since 1965. When the economy was running hot and the housing boom was upon us, ownership was at 69.2%.

The reason for this fuckery?

Millennials.

Apparently, we are hamstrung by a generation of fucktards who don’t invest in stocks, buy homes, deodorant, or even have jobs. They just like to ‘feel the BERN’ and walk around all day in Donald Trump masks, texting on their Obama phones.

“While the millennial homeownership rate continues to decline, it’s important to note that the decrease could be just as likely due to new renter household formation as it is their ability to buy homes,” wrote Ralph McLaughlin, chief economist at Trulia. “Certainly low inventory and affordability isn’t helping their efforts to own, but moving out of their parents’ basement and into a rental unit is also a good sign for the housing market.”

“Broadly speaking, the falling homeownership rate is a sign that renting isn’t only for those just starting out or making a transition, but is becoming an increasingly viable longer-term option for many households,” noted Svenja Gudell, chief economist at Zillow. “It also means incomes are not yet rising quickly enough to broadly support new homeownership, and that inventory remains too tight to allow for meaningful access to affordable housing.”

The tight supply of homes for sale, combined with higher home prices, may have been behind the Federal Reserve’s silent warning in its latest statement Wednesday. It removed a line from its previous statement, which said, “The housing sector has continued to improve.”

What ever happened to the men who aspired to become monied property owners, builders of wealth and prosperity?

We’re fucked.

Comments »

Art Cashin: You Should Worry About Oil

In spite of what the Commodity King said earlier today, the iced cube marinator in Chief, Art Cashin, believes you should be exceedingly wary about the prospects for crude oil, as it delves lower on a daily basis.

The truth is, as you can see by the market rallying, NO ONE GIVES A SHIT, ARTHUR.

Back to your regularly scheduled cocaine rally, ya’ll.

Comments »

Greenspan Warns Policy Makers of Economic Dangers, But No One is Listening

Alan Greenspan is a very old and a very smart man. Perhaps he’s had some time to reflect upon the grave dangers that his Federal Reserve policies placed upon the American economy. He’s been warning about entitlements and lack of investment for years now, but no one is listening.

Isn’t it amazing that we have people running this country who believe it’s okay to run up deficits year in and out, without ever thinking about the future? The hand outs are endless. The more people get, the more they want. Higher taxes for lower productivity. It’s a recipe for madness and failure.

Aside from that, Greenspan is concerned that stagnation might morph into stagflation. Should that occur, we’d be truly fucked.

Old man Greenspan is whistling in the wilderness.

Comments »

Dennis Gartman: There Is No Correlation Between the Price of Oil and Stocks

D. Gart is out talking greasy this morning, suggesting that the great oil boom of the past decade, when investors financed and helped leverage up nefarious wildcatters in the hope of cashing in on expensive $100+ crude prices, due to war and fuckery, is meaningless drivel now that oil has collapsed. In other words, D. Gart doesn’t believe there is a debt storm around the bend, in spite of the balance sheet numbers that suggest a solid $600 billion is teetering on distressed levels.

Because there isn’t a debt bubble in crude, Gartman thinks you should all shut the fuck up about a nonsensical correlation between crude and stocks–because he has charts from the 1980’s and 90’s (pre-bubble era) suggesting otherwise. When asked about whether the price of crude going lower might scare people into believing global growth was at risk, D. Gart quickly reversed his opinion and acquiesced to that logic.

Comments »

Wall Street Isn’t Buying What $WFM is Selling

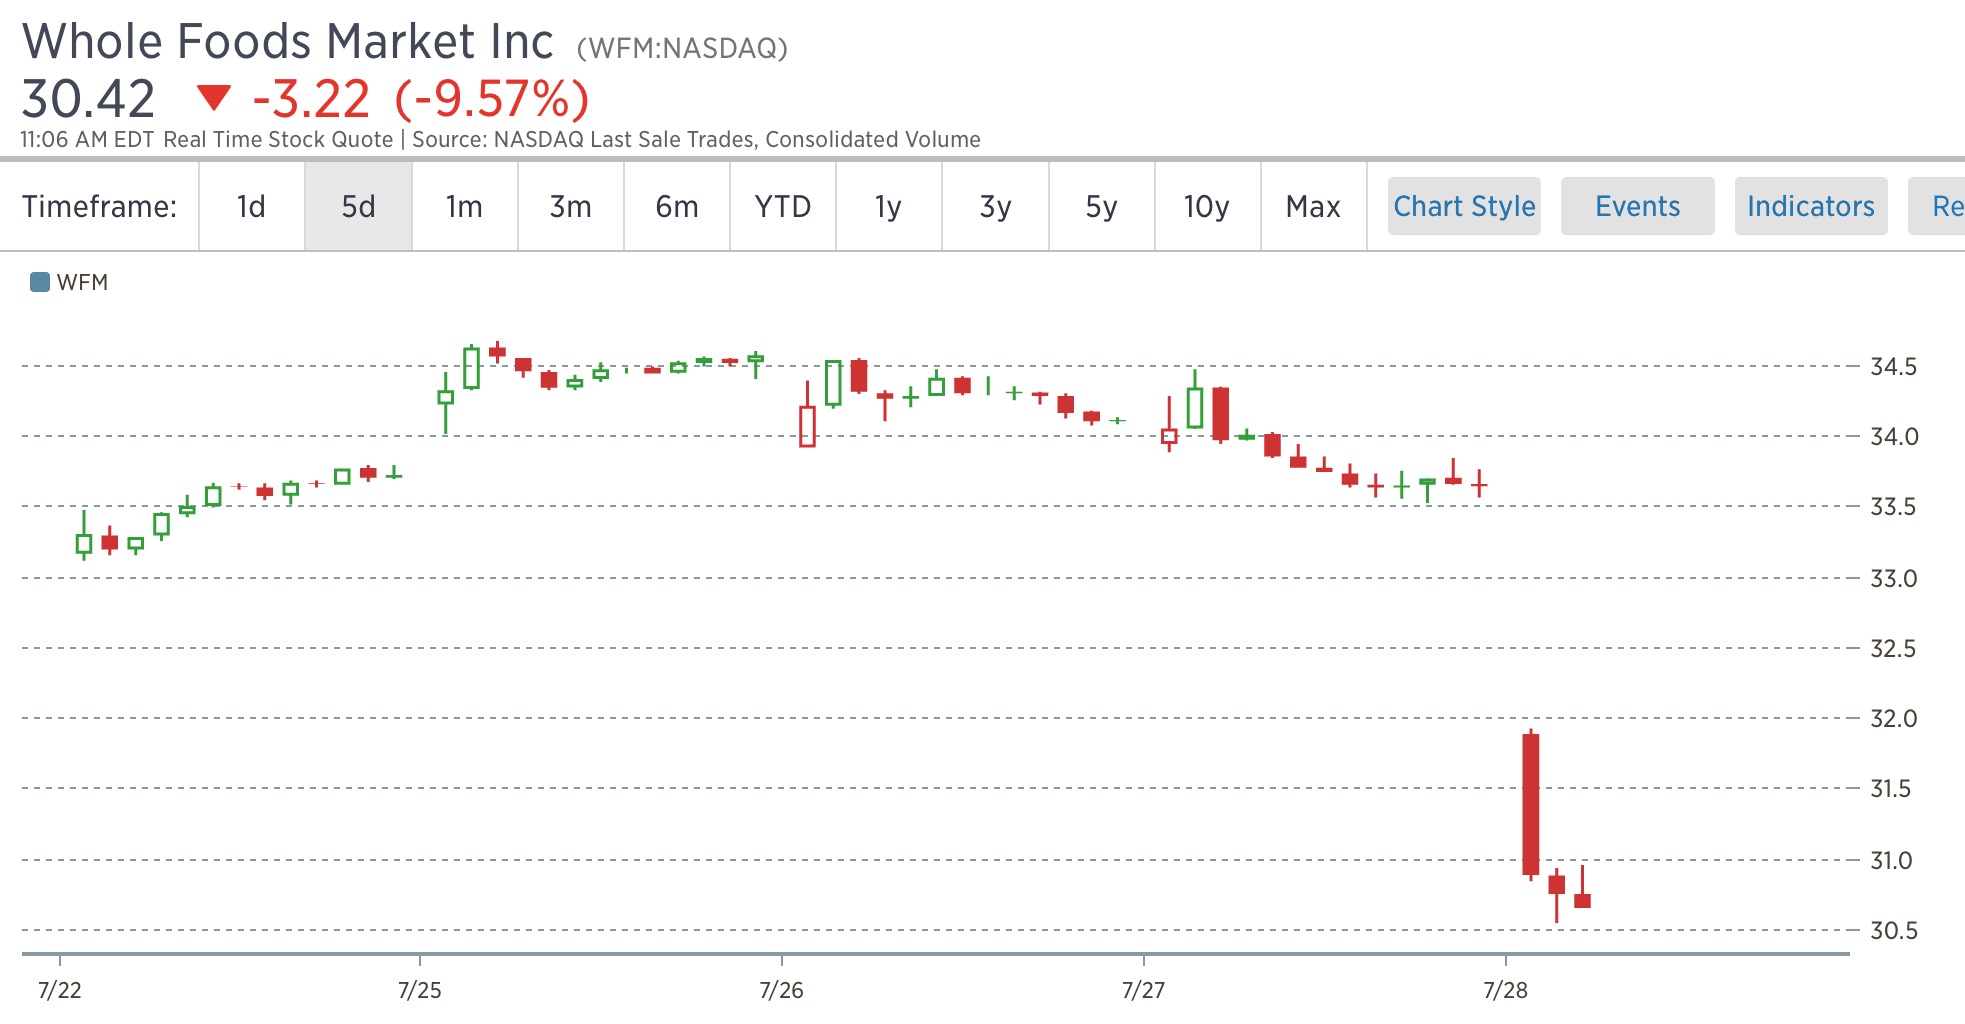
Remember when Whole Foods was a special place? It was a respite from the God foresaken Foodtowns and Pathmarks of the world. But the world caught up to Whole Foods and now the innovator is becoming the imitator of lesser brands. In this case, I am speaking of Whole Foods’ 365 niche store concept, an obvious rip off from Trader Joe’s.

I like TJ; but everyone knows it’s s poor man’s WFM. The company is lost without a paddle. Wall Street isn’t buying what they’re selling and neither am I.

image

Analysts take.

TAG understands the co is actively attempting to reduce costs and restructure the business, but there has not been much improvement in sales despite a multi-year investment in price and traffic driving initiatives. The competitive environment remains intense, and Whole Foods is still searching for a solution. Traditional and other specialty grocers continue to encroach on Whole Foods’ niche, forcing the co to increase its investment in pricing and marketing, and seek growth beyond the core concept via its new “365” by Whole Foods banner. In addition, the shift toward online grocery and the need to invest to be relevant and differentiated in that space may weigh on earnings. Although Whole Foods seems to be doing the right thing by focusing on traffic-driving initiatives and reducing its cost structure, they need to see stabilization in same-store sales to believe that the co’s efforts are generating results.

Pivotal Research notes the most worrisome development about Whole Foods’ latest results is the continued sales deceleration heading into FY17. Two-year stacked comp trends declined from +0.6% in 2Q16 to -1.3% in 3Q16. They expect two-year stacked comps to take a further step back by 130 bps to -2.6% in 4Q. Against this backdrop of heavy gross margin investment and continued descent of Whole Foods’ sales trajectory, the potential for comps to remain negative in FY17 is now a real possibility. Currently, the consensus expectation is +1.5% for FY17 comps. By the time mgt. communicates its preliminary FY17 guidance in early November, they think there will be several more shoes to drop that could weigh on the earnings outlook for next year; Sell.

RBC notes that while QTD commentary fell below expectations, they believe Whole Foods relieved fears over the need to rebase earnings. With better earnings surety and unchanged (albeit weak) comp profile, near-term downside is limited. Their thesis is predicated on 365’s ability to tap into a previously unavailable growth engine. Legacy quarterly results, absent a sequential deceleration, do not shake that view.

Wedbush notes WFM’s 3Q16 performance was effectively in-line on impressive cost control and included encouraging commentary surrounding various initiatives including recent produce investments (beginning to improve basket sizes, traffic), but the company’s QTD comp trend decelerated again on a 2-year stack basis. While they see opportunities for WFM in FY17 as intriguing (new store concept, procurement, affinity program, POS initiatives), these factors may do little to offset near-term competitive concerns for investors and therefore still believe WFM shares will remain range bound.

Comments »

The Crude Story is Being Tarred and Blackened

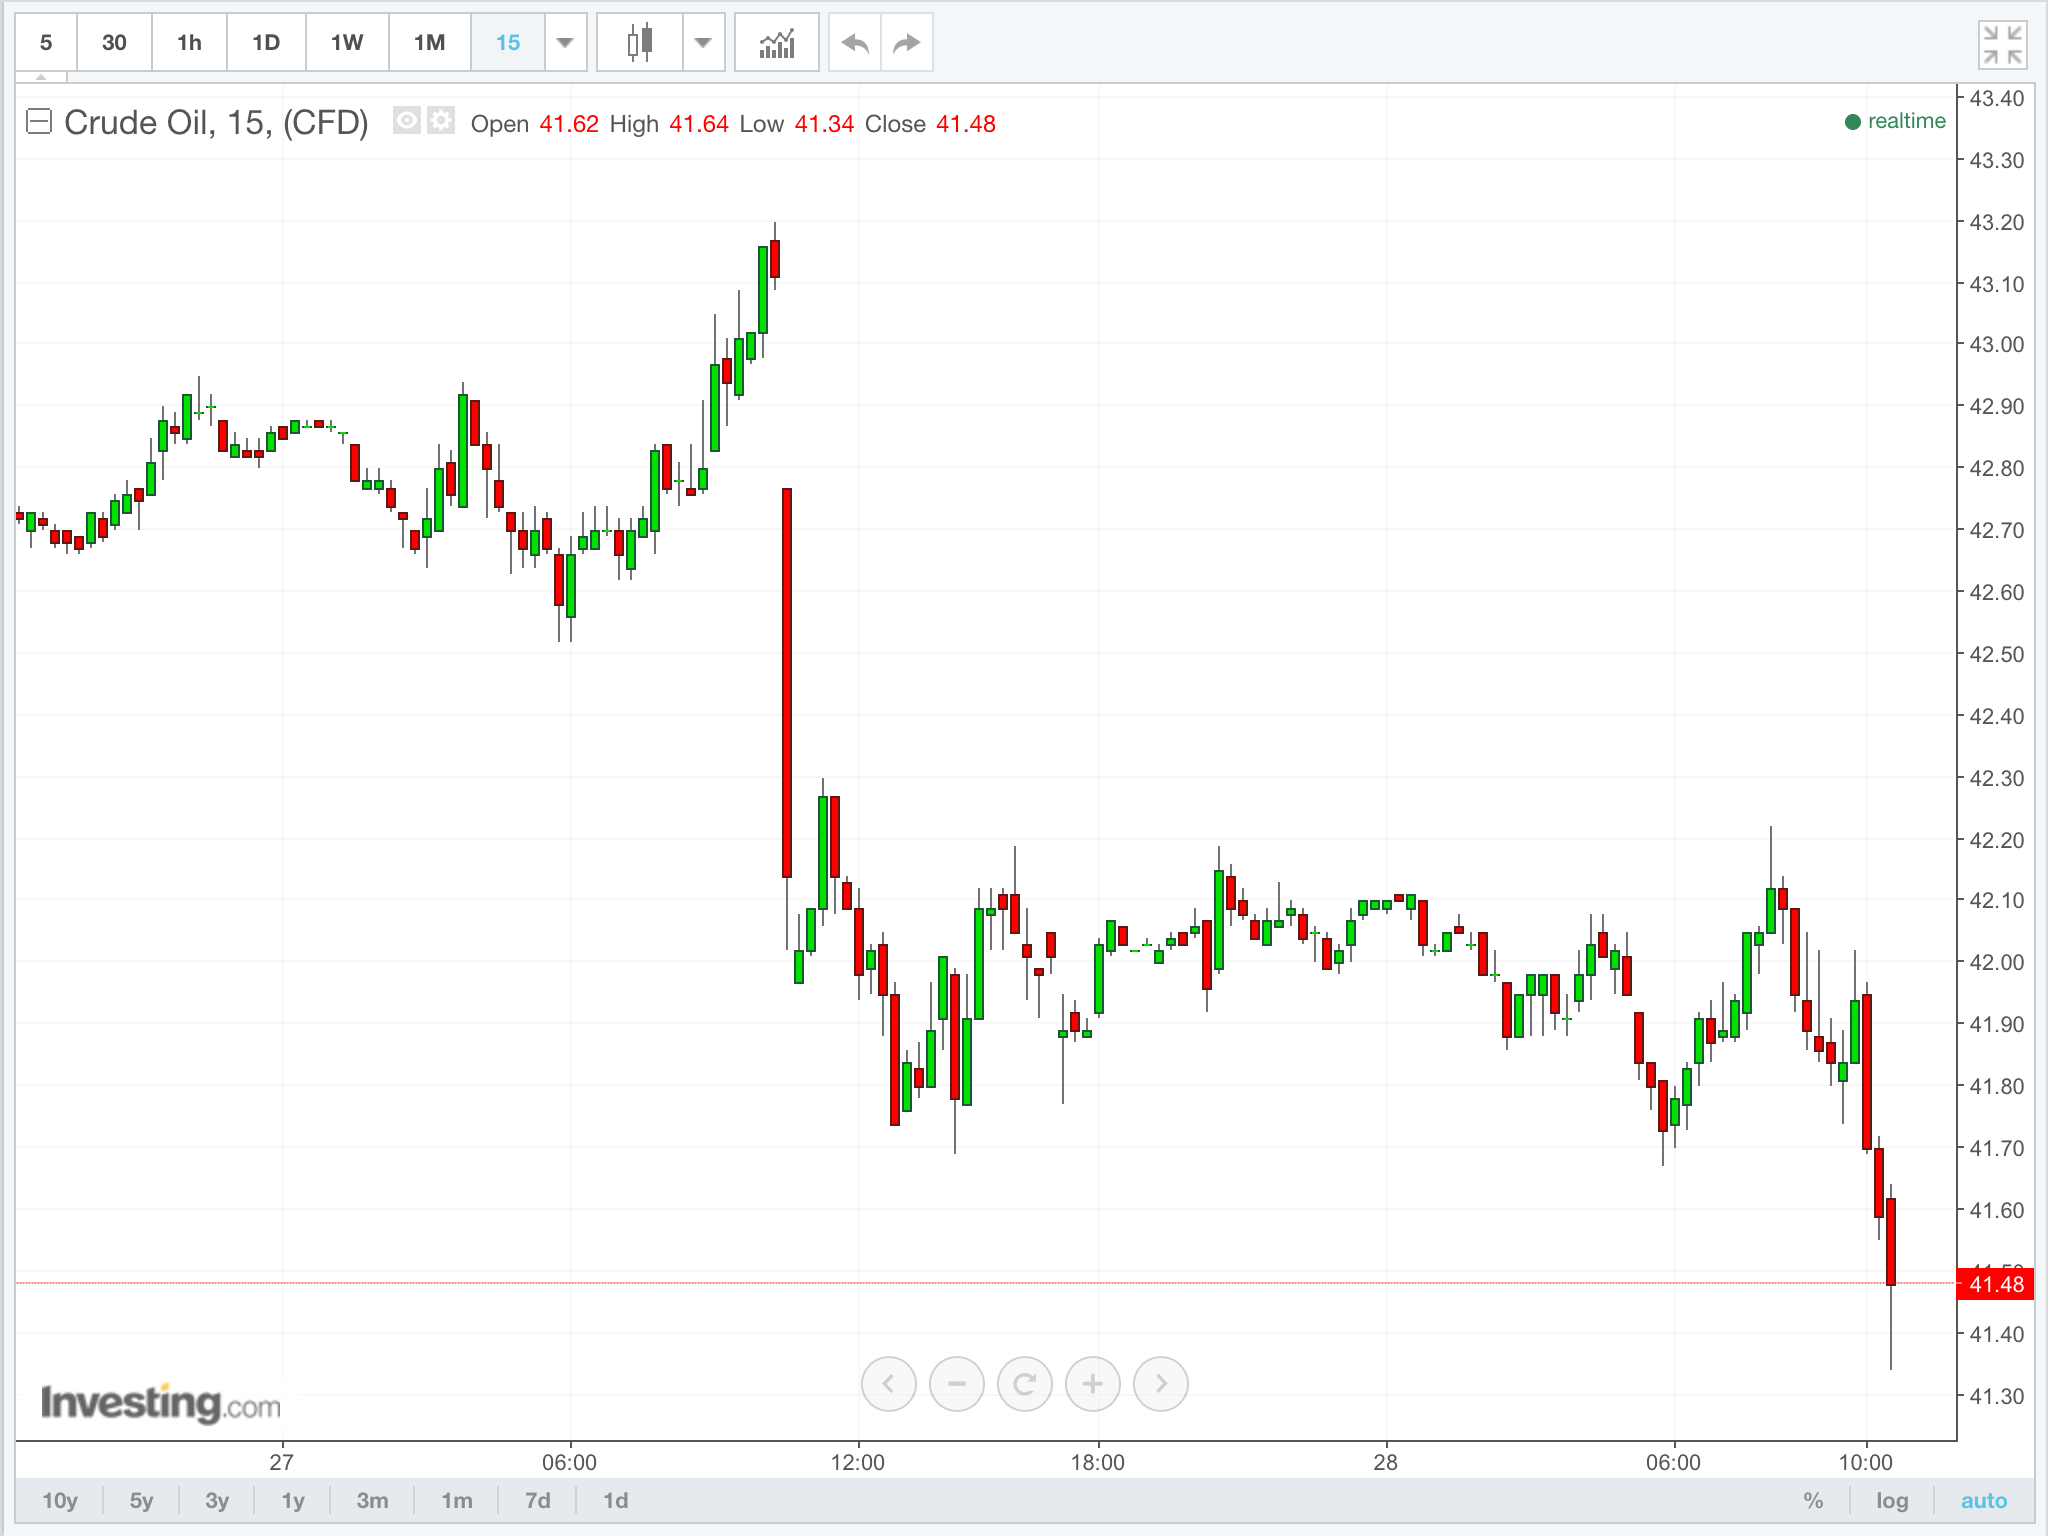
WTI is down another percent today, widening its losses to 14% over the past month. For the most part, oil stocks have stupidly ignored this horrendous price action and have traded like grocery store stocks.

The fuck out of here.

image

Down, down, down.

WLL and CLR are your coal mine canaries. The blood will flow, heavy and with ceaseless consistency. You’d be wise to liquidate your entire portfolio and go swimming in St. Bart’s, should crude break $40 to the downside.

Comments »

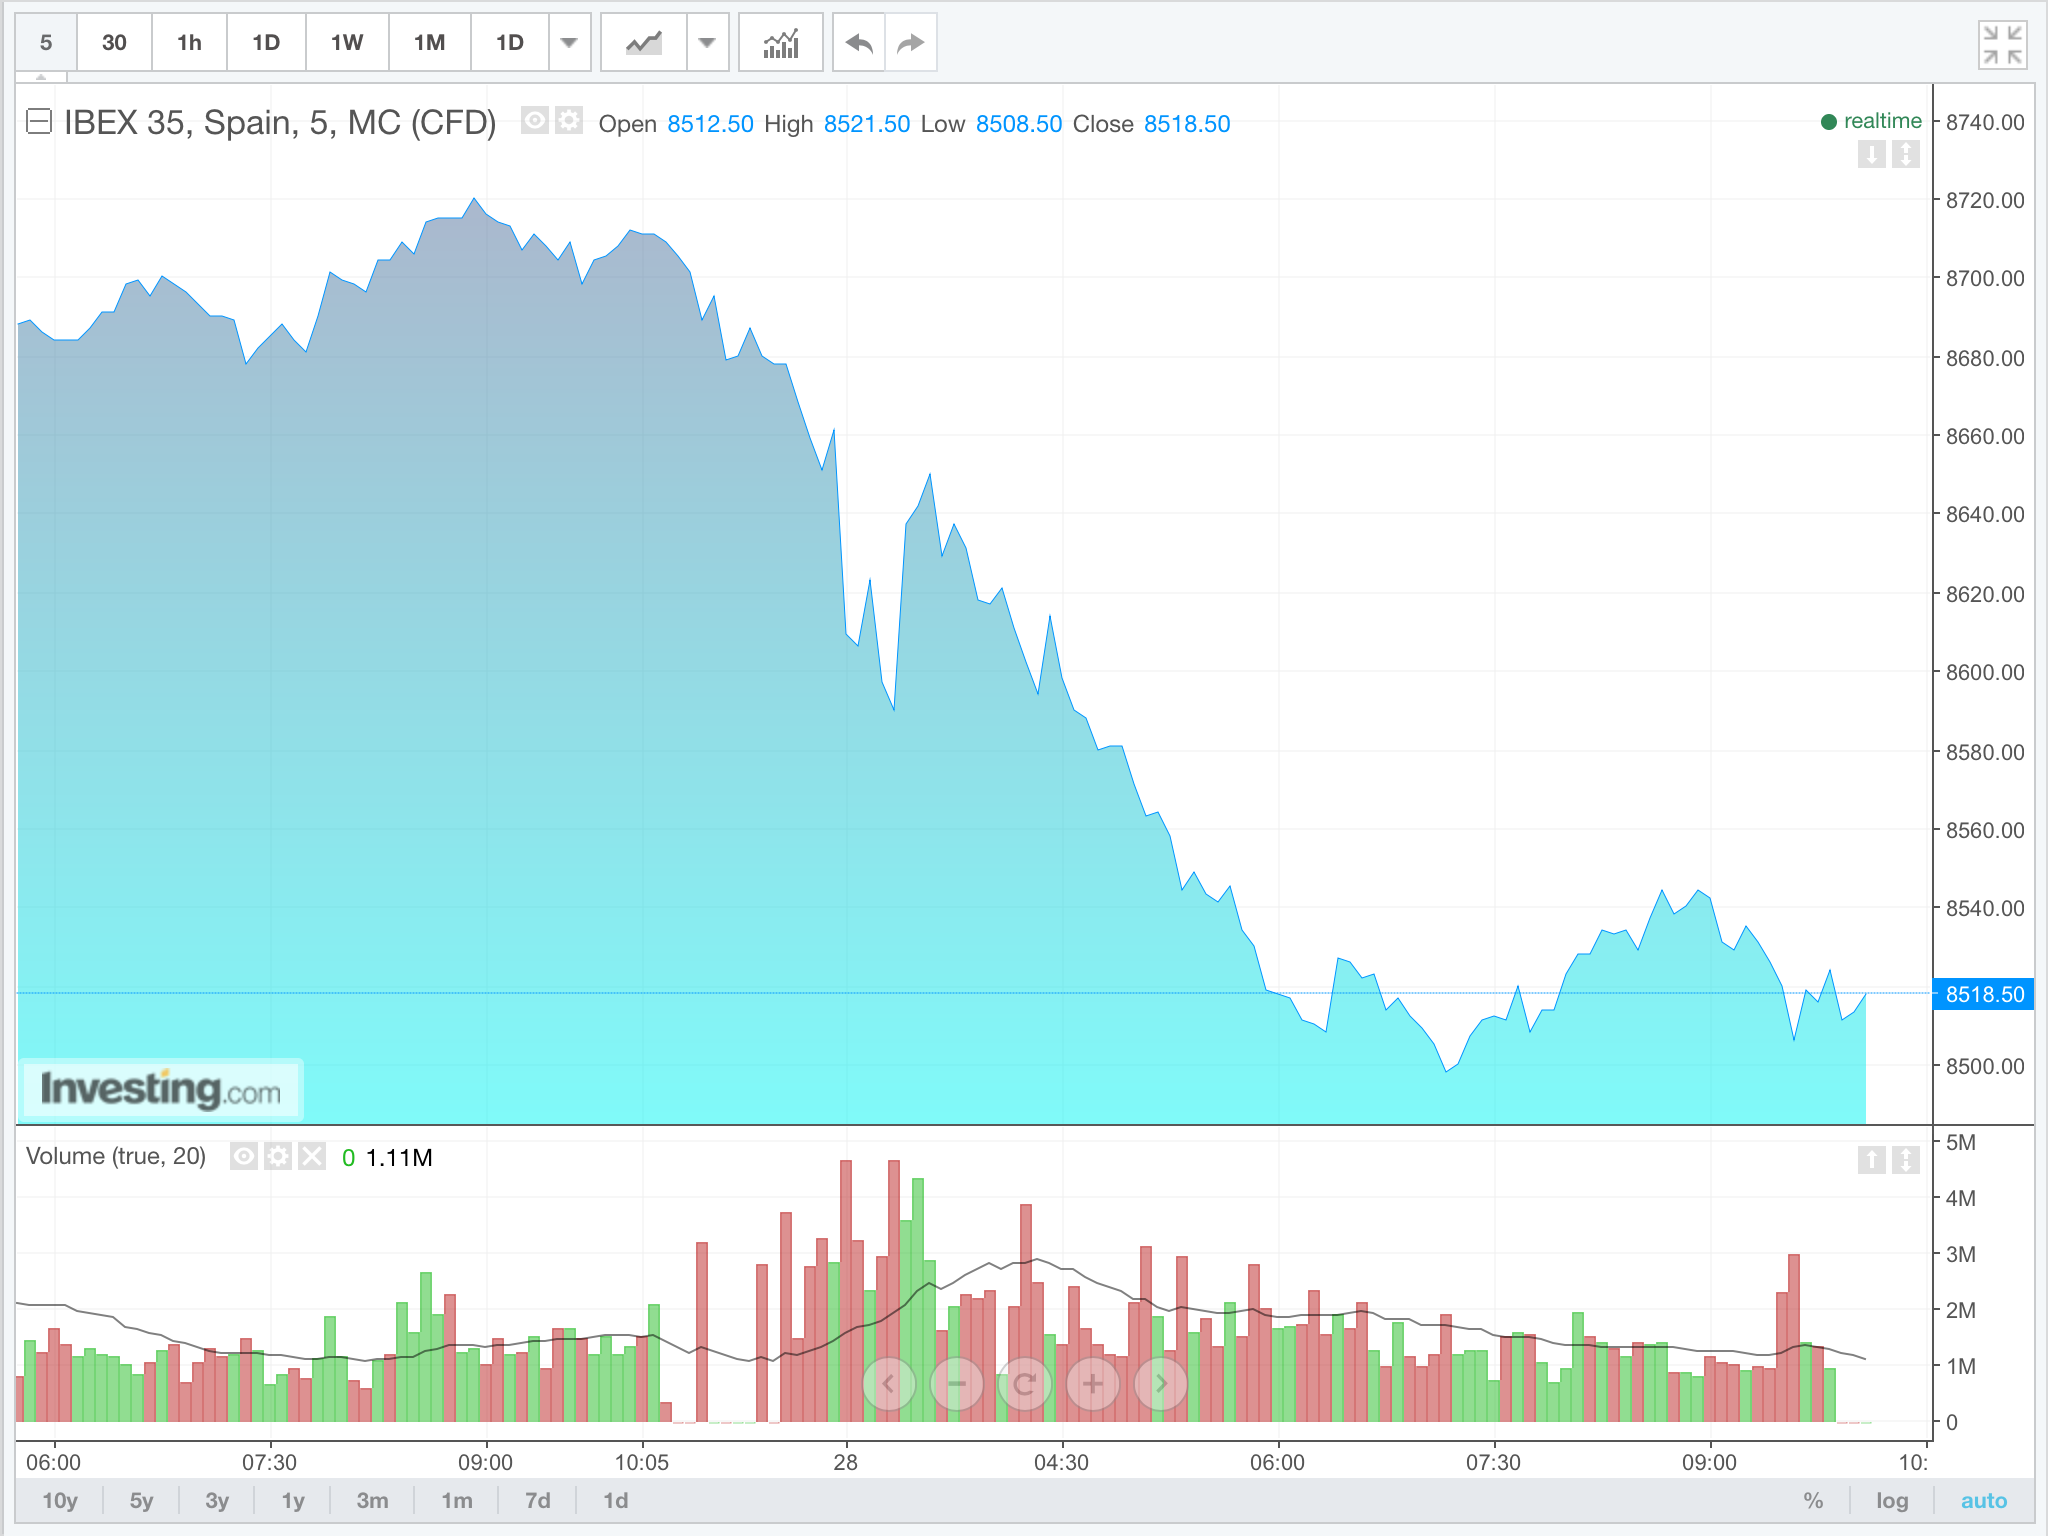
Italian and Spanish Markets Are Getting Rocked

I know, who cares about those latins? Truth is, the jingoistic mentality of this country could see our stocks rise amidst nuclear detonations in Europe. We’re at a point in this cycle that the gains are excessive to the point of madness.

It’s the sort of tape you chase. You get lured into the fray by a sundry of tantalizing moves, like FB, AAPL or even N and GRUB. We’re in the midst of a truly special time for stocks and I am going to make sure that I miss out on every single second of it.

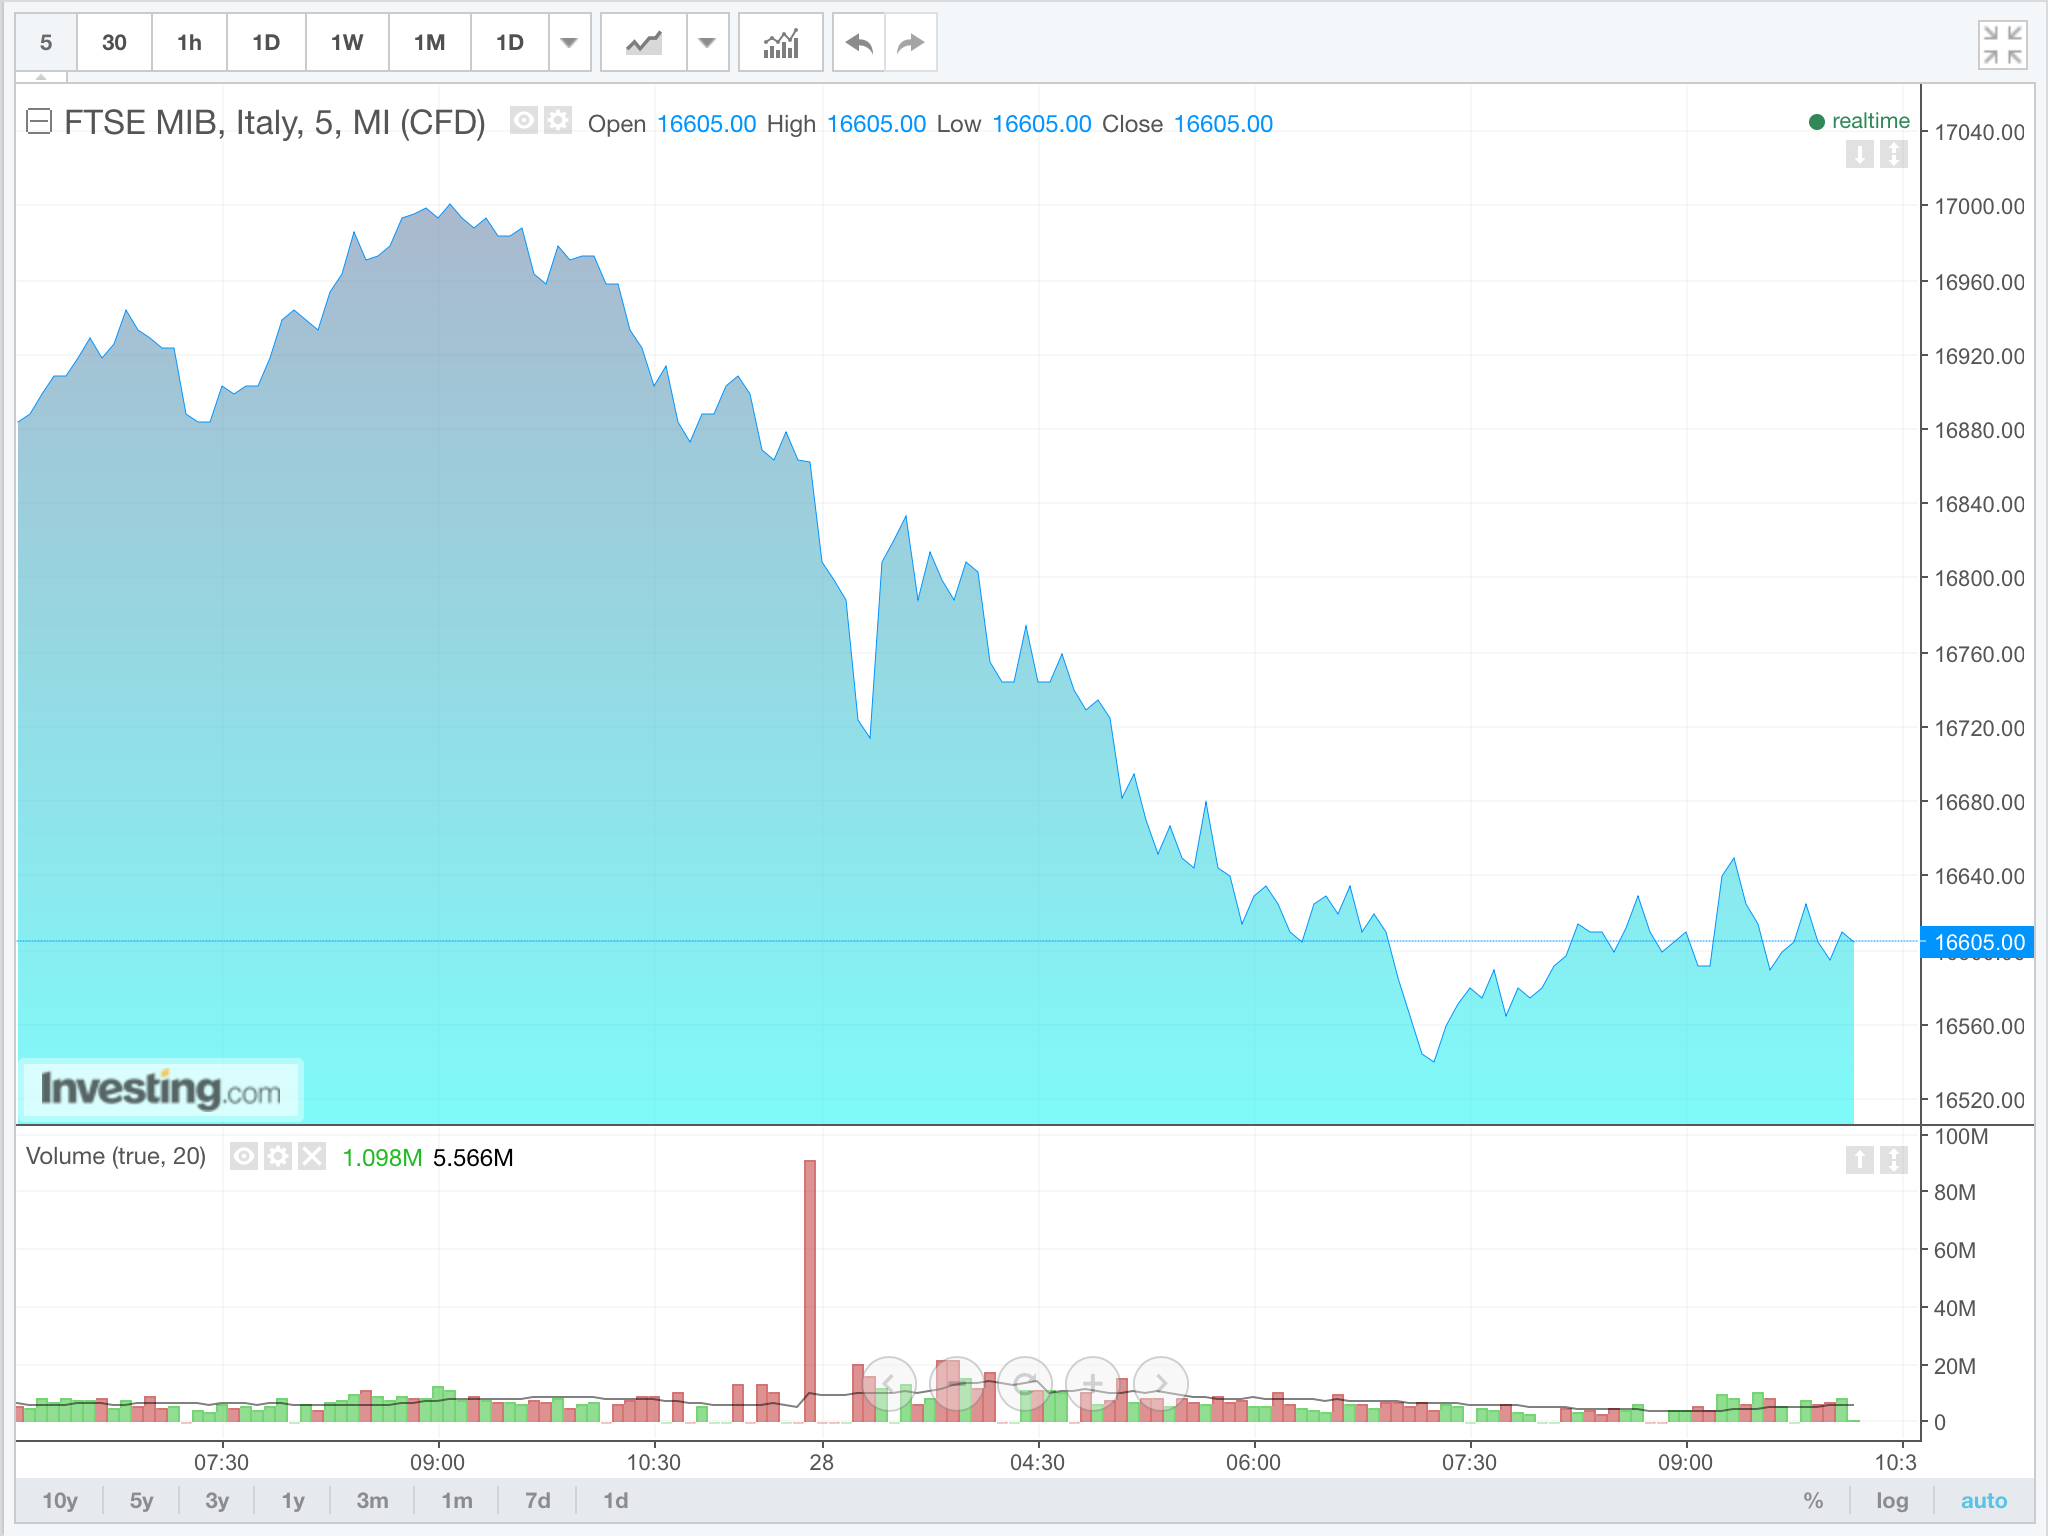
Both Italy and Spain are down in excess of 1.5%, led lower by banks.

image

image

Unicredit is down 4% and about a dozen other banks are lower by 3%.

Comments »

Two Stocks to Own for Those Scared to Get Shot

Afraid to go outside of your housing tenements? That Taco John’s or Kansas Fried Turkey is looking real good, from your window view. If only you could get the food without having to risk going outside and possibly get robbed or shot.

Hey, we live in a very high tech world these days. It’s not like how we grew up in the 90s, playing games with numbers on our beepers. I read a report last week that stated restaurant stocks are weak (Extra Hillary) because people are afraid of the anarchy. The analyst said to buy PZZA. I like that play, and also DPZ. But it’s not the reason why I wrote this damned article.

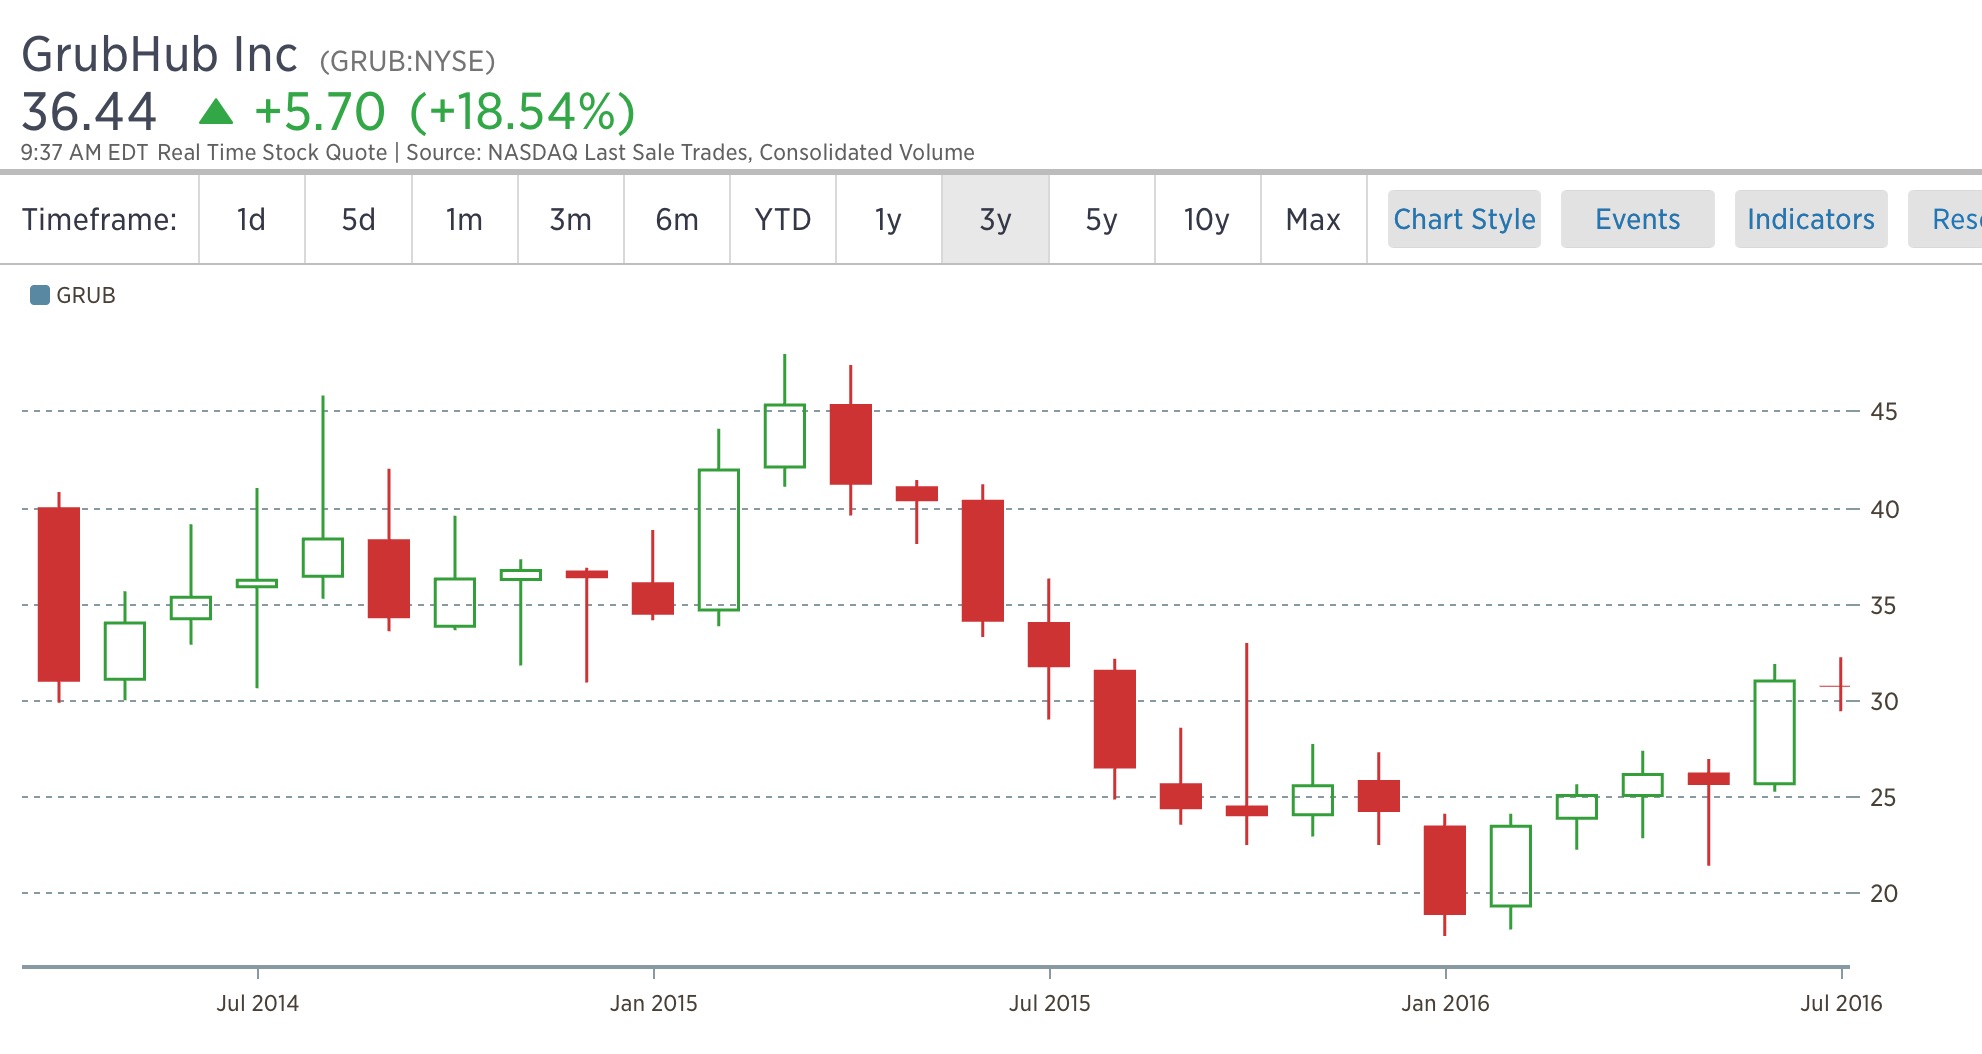
Order via your phones, jackasses. GRUB specializes in placating the coward and the sloth. They just crushed the quarter.

image

Reports Q2 (Jun) earnings of $0.23 per share, $0.04 better than the Capital IQ Consensus of $0.19; revenues rose 36.6% year/year to $120.2 mln vs the $114.25 mln Capital IQ Consensus. EBITDA $37.6 mln vs. $30-32 mln guidance.

Active Diners were 7.35 million, a 24% year-over-year increase from 5.93 million Active Diners in the second quarter of 2015. Daily Average Grubs were 271,100, a 23% year-over-year increase from 220,100 Daily Average Grubs in the second quarter of 2015.

Gross Food Sales were $733 million, a 29% year-over-year increase from $568 million in the second quarter of 2015.

Co issues upside guidance for Q3, sees Q3 revs of $116-119 mln vs. $113.82 mln Capital IQ Consensus; EBITDA $30-32 mln.
Co issues upside guidance for FY16, raises FY16 revs to $480-488 mln from $465-480 mln vs. $473.30 mln Capital IQ Consensus; raises EBITDA to $136-142 mln from $125-133 mln.

The other obvious play is YELP. It’s one of my go to apps. As a food and a very brave man, I enjoy the many luxuries that YELP affords me. They also have an order in feature, which of course caters to the dystopian world we’re delving into.


Comments »