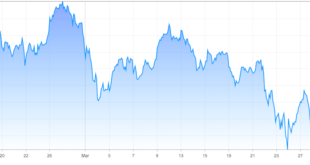
Hahahaah, where are the MuskFAGS now? Do you see the share price? Let me show you, for those without quotes.
BAM!

An analyst at Morgan Stanley is very bullish on the stock, but also warned today that the recent spate of bad luck for the stock might, in fact, beget even more bad luck. While some of you retarded one’s out there might discard that statement as pure folly, or perhaps insignificant. But for those of us on Wall Street with brain, we know damned well what it means. The firm is implying TSLA might be entering a fucking death spiral, one that worsens as the shares decline. One that is accentuated by its debt/eq levels which has been the cause of innumerable bankruptcies over the years.
“A sharp drop in Tesla’s share price in part reflects questions on Model 3 ramp … an event that directly impacts both the company’s near-term cash needs and ability to potentially access the market for capital,” analyst Adam Jonas wrote in a note to clients Wednesday. “A lower share price begets a lower share price… For a company widely expected to continue to fund its strategy through external capital raises, a fall in the share price can take on a self-fulfilling nature that further exacerbates the volatility of the share price.”
That’s code talk for get your share price up, or see it trade directly to zero.
Then the analyst shills for Musk, likely forced by gunpoint by Morgan upper management to retain good relations with their client, saying it might be a good time to step in and buy some TSLA, in spite of it being ‘very high risk.’
“We think that we are looking at one of the buying opportunities that many investors have been waiting for,” he wrote. “We’d use further weakness from here as an opportunity to build an Equal-weight position in the stock … We see Tesla as modestly undervalued with very high risk.”
The fuck?
On a related note, a small hedge fund manager, with symptoms of a brain injury, thinks TSLA is ‘months away’ from bankruptcy. He’s betting on it too, shorting TSLA with ruinous implications.
Unless Elon Musk “pulls a rabbit out of his hat,” Tesla will be bankrupt within four months, says John Thompson of Vilas Capital Management.
“Companies eventually have to make a profit, and I don’t ever see that happening here,” he told MarketWatch. “This is one of the worst income statements I’ve ever seen and between the story and the financials, the financials will win out in this case.”
“Tesla, without any doubt, is on the verge of bankruptcy,” he told clients in an email over the weekend. He explained that funding will be hard to come by in the face of problems in delivering the Model 3, declining demand for the Model S and X, extreme valuation and a likely downgrade of its credit rating by Moody’s from B- to CCC.
“As a reality check, Tesla is worth twice as much as Ford [estimate of the enterprise value of both companies], yet Ford F, -0.09% made 6 million cars last year at a $7.6 billion profit while Tesla made 100,000 cars at a $2 billion loss,” Thompson said. “Further, Ford has $12 billion in cash held for ‘a rainy day’ while Tesla will likely run out of money in the next 3 months. I’ve never seen anything so absurd in my career.”
From Moody’s credit downgrade today.
Tesla’s liquidity consists principally of $3.4 billion in cash and securities at December 31, 2017. The company also has moderate availability under the $1.9 billion ABL facility. This liquidity position is not adequate to cover:
1) the approximately $500 million in minimum cash that we estimate Tesla must maintain for normal operations;
2) a 2018 operating cash burn that will approximate $2 billion if Tesla maintains high discretionary capital expenditures to increase capacity; and
3) convertible debt maturities of approximately $1.2 billion through early 2019. These cash needs will likely require Tesla to undertake a near-term capital raise exceeding $2 billion. Moreover, if the company maintains its expected pace of expansion, it will likely need to raise additional capital during the second half of 2019.
Tesla’s rating could be lowered further if there are shortfalls from its updated Model 3 production targets. The rating will also be pressured if the company is unable to raise sufficient new capital to cover its late-2018 and early-2019 convertible maturities, and to cover the operating cash consumption that will likely continue into 2019.
The rating could be raised if production rates of the Model 3 meet Tesla’s current expectations and if the company maintains good liquidity.
Elon Musk – Trippin' Balls
RELATED: Hitler finds out he’s invested in TSLA 2025 senior notes.
Comments »