iBankCoin
Home / 2016 / October (page 16)

Monthly Archives: October 2016

Goldman Might’ve Beat Earnings, But They Still Suck

Look at their balance sheet statement for the first 9mos compared to last year. Does this look like a healthy business, making up the majority of its gains in interest income schemes? If it weren’t for their money changing abilities to turn gold out of shit, one might surmise this was a shitty business.

img_5263

The stock is higher in the pre market, but I’m not impressed.
img_5264

For the quarter, they bought back 7.8m shares at $162 for more than $1.2b. They have 34m shares left in their buyback program, while steadily cutting back on their employee headcount.

For the past 3 months, all of their growth has been in lending.

img_5265

If you’re buying Goldman here, you’re betting on a company that is using buybacks to boost earnings and wholly dependent on non investment bank growth to fuel their business. They just unveiled their new lending business, dubbed Marcus, so I suppose they’ve seen the future and it has more to do with lending than it does with their core business of investment banking.

It’s too muddled with lots of gray areas. I’d avoid.

Comments »

A Global Stock Rally is Underway; BREXIT Might Be Stalled

The market loves corruption and stagnation. Asian markets ripped higher last night, led by Hang Seng up 1.5%.

This morning it’s all about the MIB — higher by 1.8%.

img_5262

And of course there are rumblings that the U.K. might need the House of Corrupt Commons vote on BREXIT.

This from bbg

“There’s a very strong argument for the government allowing the approval of a deal reached, but of course it would prefer a vote after Article 50 is triggered,” said Robert Thomas, professor of public law at the University of Manchester. Against the backdrop of a ticking clock, lawmakers would be “pressured to agree” to any deal, he said.

So it’s all very well and good. WTI and gold are edging higher and futures are up 100.

Comments »

Politico’s Chief Political Correspondent to Podesta: ‘I Have Become a Hack…Please Don’t Tell Anyone I Did This’

In ancient times, Glenn Thrush, Politico’s Chief Political ‘Correspondent,’ would be called a ‘catamite’ for the ruling class. The Praetorian Guard would summon him to pleasure one of Rome’s Senators and then whipped about a pole, then told to go home to his disgusting hovel of a shit house. He is a man of little to zero integrity, living in a world that isn’t his own. He believes that by doing good by those who he adores, it will further his career and maybe become ‘one of them.’ He isn’t one of them. He never will be one of them. Instead, he prostitutes himself over the mantle of degeneracy — always attempting to please the ruling class of socially trendy totalitarians.

He is a cog in the agitprop wheel and has been outed for what he is: a scandalous mountebank, member of the Third Estate, ordinary canaille. Very plain and very boring.

Read.

2016-10-17-politico-1

Comments »

RIGGING THE ELECTION: Undercover Investigation Reveals Wanton Fuckery in the DNC on a Large Scale

Does anyone care anymore? I sense that this sort of in your face criminality isn’t interesting enough for the average American. We’re more interested when some two bit stock broker gets a tip and trades on it, sending him into gaol for a period of 10 years, than this stuff.

All of these people should be in jail, even placed inside of electric chairs and roasted without a watery cap.

If you could watch just one undercover video regarding the election of 2016, it is this one.

Comments »

Netflix Positively Crushes Estimates; Stock Soars in After Hours Celebration

Netflix is higher by 19% in the after-hours, on an earnings beat for the ages. If you recall, I highlighted the idiot nature of Wedbush and the people that work there about a week ago — who made just about the worst call in the history of stocks — suggesting NFLX was to be cut in half.

Here are the headlines, via Briefing.com.

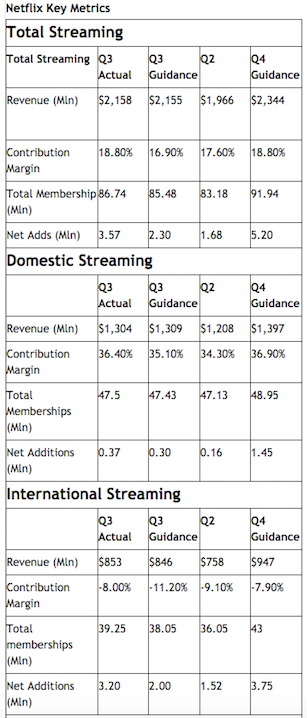
Netflix Q3 Domestic Net Additions 0.370 mln vs 0.30 mln guidance; Q4 guidance is for 1.45 mln, expectations were for ~1.00 mln; Q2 adds was 0.16 mln

Netflix prelim Q3 $0.12 vs $0.05 Capital IQ Consensus Estimate; revs $2.29 bln vs $2.28 bln Capital IQ Consensus Estimate

Netflix sees Q4 $0.13 vs $0.08 Capital IQ Consensus

Netflix Q3 International Net Additions 3.20 mln vs 2.00 mln guidance; For Q4 NFLX expects addition of 3.75 mln, expectations were for ~3.00 mln; Q2 Adds was 1.52 mln

nflx


In Q3, we added 0.4 million members in the US vs. our forecast of 0.3 million and 3.2 million members internationally vs. our forecast of 2.0 million. Our over-performance against forecast (86.7m total streaming members vs. forecast of 85.5m) was driven primarily by stronger than expected acquisition due to excitement around Netflix original content.

By the end of Q3’16, we had un-grandfathered 75% of the members that are being un-grandfathered this year and the impact has been consistent with our expectations. ASP grew over 10% year-over-year in both the US and international segments (excluding a $35 million F/X impact).
In the international segment, we exceeded our internal projection for net adds as the acquisition impact of our originals was greater than anticipated across many of our markets.We are investing in more content across multiple international markets in Q4 and, as a result, we project international contribution loss to grow moderately to $75 million.

For Q4, we forecast 5.2 million global net adds, with 1.45 million net adds in the US and 3.75 million new members internationally. Our expectation for a moderate year-over-year decline in net adds reflects the completion of un-grandfathering. We are pleased with the results thus far as we expect ASP to grow 12% from Q1’16 to Q4’16. Internationally, the initial demand from our launch in Spain, Portugal and Italy in Q4’15 will also affect our year-over-year net adds comparison.

China- The regulatory environment for foreign digital content services in China has become challenging. We now plan to license content to existing online service providers in China rather than operate our own service in China in the near term. We expect revenue from this licensing will be modest. We still have a long term desire to serve the Chinese people directly, and hope to launch our service in China eventually.

Consequently, we plan on investing more, which will continue to weigh on free cash flow. We expect Q4’16 FCF to be similar to Q3’16 FCF. Over time, we will be able to fund more of our investment in programming through the growth in operating profit and margin already underway. Streaming content obligations at quarter end were $14.4 billion, up $1 billion sequentially.

We finished the quarter with $1.3 billion in cash and equivalents. As we have often done over the past few years, we plan to raise additional debt in the coming weeks. With a debt to total capitalization ratio of about 5%, we remain underleveraged compared both to similar firms and to our view of an efficient capital structure.

The stock is trading at $119 in the after- hours. The 52 week high is $133. Look for the stock to squeeze towards and above that high in the days and weeks ahead. There are a lot of bears marooned in this stock.

The one caveat here: cash burn is up big, doubling from $250m to over $500m for the quarter. Look for the company to announce a secondary soon. After the price drops from the offering, get back in for the lift higher.

Comments »

Hillary Won the Election Today, So How’d the Market Do?

According to a recent poll by NBC/WSJ, Clinton is up by 11 points on Trump — all but eviscerating the great orange one from ever stepping foot in the White House. My initial reaction is to buy burglary protection stocks — since criminality will be all the rage under the Clinton regime. Everything trickles down — in this case: burglary.

But in all seriousness, if today was the day that the Clinton-Kaine campaign hammered coffin nails into Trump’s live body, how’d the market do? Which sectors were affected most?

Autos, drugs, textiles, banks, semis, trucking and food sectors all bore holes in the market today — sporting deleterious breadth of less than 20%.

On the upside:

Gold, utilities, steel, REITs and metal fabrication did well.

What can we surmise from all this?

During an H. Clinton administration, we’ll all be employed by our local welders creating doomsday devices and/or in a mine in search for metals for an alien race. The memories of when cars, clothes, banks and food were easily acquired will be all but a wistful after-thought — a time in America when things were good. The water was bountiful and milk and bread retailed at the grocer in great abundance.

If today is the celebration of political victory for the establishment, prepare for a woefully forboding 4 years of sheer market fuckery.

Comments »

Halftime Report Drivel: Icahn, Tepper Interviews Produce Nothing But Boring Meaningless Subterfuge

Congratulations to the Halftime report for wasting our fucking time for the 5th year in a row. On this joyous day, they beset upon us a meaningless Icahn interview where Scott Wapner asked one of the world’s best investors about Donald Trump’s pussy grabbing jargon. Before that, he offered us a hard hitting interview with the Sage of the Short Hills Shopping Mall, David Tepper.

Here is what he said.

Absolutely nothing. Fuck you Halftime Report. I’d be better off watching Sponge Bob and my pal Squidworth (sp?), than this shit.

Comments »

A Broad Look at Consumer Discretionary Stocks

The stock prices reign supreme. Everything else is just rhetoric. If the American economy is upwards of 70% consumer oriented, the health of said consumer is absolutely vital to the long term prospects for the market.

Here are the returns, year to date, of some of the bigger consumer discretionary stocks — broken down by sector.

Apparel

VFC -11%, UA -6%, HBI -16%, PVH +50%, RL -11%, LULU +5.5%, GIL -4%

Apparel has been tepid in 2016 — as a fickel consumer hops from one fashion to the next. One thing is constant, however, LULU continues to execute, while PVH surprises to the upside. They own the iZod brand and that’s been crushing this year.

Apparel Stores

ROST +21%, LB -20%, GPS +10%, FL +6%, JWN +9%, URBN +53%, AEO +13%, DSW -9%, ANF -40%

LB had some issues early on, while URBN nailed the trends. Overall, it’s truly a tale of two cities. If there’s one constant it is this: you’re either killing it with good fashion or getting the price points just right, like ROST, to attract buyers. Nothing unusual about the sector so far.

Department Stores

TJX +5%, M +4%, KSS -6%, JCP +29%, DDS -9%

Department stores have been plodding along — seemingly able to navigate a lethargic consumer. There was notable strength in JCP this year, still recovering from the harrowing Ron Johnson-Bill Ackman years.

Restaurants

MCD -2%, SBUX -11%, YUM +22%, CMG -17%, QSR +18%, DRI +3%, DPZ +39%, PNRA -2%, DNKN +22%, CBRL +12%, PZZA +41%, JACK +26%

While many of the smaller chains have done poorly, the larger names continue to shovel food into the fat, fucking, faces of the American pie gobbler. There was a noteworthy drop in the poisonous CMG, while DPZ and PZZA continue to deliver artery clogging pizza pies to American at a record pace. Also, DNKN gained on SBUX and JACK took share from CMG.

Sporting Goods

DKS +59%, CAB +32%, POOL +16%, VSTA -14%, SWHC +17%

Killer year for sporting goods, following the liquidation of Sports Authority. Gun sales are robust too, which helped CAB.

Auto Dealerships

KMX -5%, CPRT +41%, AN -19%, PAG +9%, LAD -10%, GPI -16%, ABG -18%

Car sales appear to be stagnating.

Specialty Retail

NFLX -13%, SHW +4.6%, LUX -28%, ULTA +40%, TSCO -22%, TIF -3.5%, SIG -34%, MIK +6.5%, SPLS -17%, BUFF +32%, BC -4%, BID +39%

Monster gains in ULTA. I hear they have the right mix. People love their pets, via BUFF. And the super rich appear to be collecting stuff again, via BID.

Home Furnishing

BBBY -16%, WSM -18%, RH -63%, HVT -16%, PIR -16%

Dreadful year for this sector. This is indicative of the stagnant home buyers market for the middle class. Rich people don’t buy stuff from BBBY or PIR. And,  while WSM might be expensive for middle class folks, it’s not exactly high end either. This is a really hard industry to invest in now, unless we see a big uptick in home sales.

Catalog/Mail Services

AMZN +21%, EBAY +15%, QVCA -31%, W -26%

Amazon and Ebay are executing. Everyone else gets executed.

Discount Stores

WMT +13%, COST -6.7%, TGT -5%, BURL +80%

Cheap stuff. Walmart is the cheapest grocery and random shit store, while BURL sells the cheapest clothes on the planet.

Apparel Footware and Accessories

NKE -17%, COH +10%,  KORS +17%, SKX -27%, WWW +35%, DECK +18%

Nike struggling, while FL stock is up? Something is off. This is a comeback year for COH, KORS and DECK.

Grocery

KR -25%, WFM -13%, CASY -3%, SFM -18%, CST +23%, WMK +25%, SVU -23%

This sector is beguiled by margin pressures. I am surprised to see KR get hit. Blame WMT.

Overall, the consumer is doing okay. There are some big winners out there and plenty of losers. Like most things in life, it all depends on your perspective. It’s performing like an economy growing at 2%. Enough said.

Comments »