iBankCoin
Home / 2015 (page 43)

Yearly Archives: 2015

The Valeant Drama Continues

Bloomberg is out with a late night, exclusive article, talking shit about VRX, giving Bill Ackman nightmares. Don’t you know he barely sleeps after all of the grief that fucker Ron Johnson gave him after the JCP fiasco? Last thing he needs is a $3 billion position turn into fairy dust, a la Enron, the Canadian pharma version.

Actually, the documents BBG secured are pretty damning, painting a fairly vivid picture of a boiler room type operation at VRX. For the record, I would expect nothing less, being that it’s domiciled in the traitorous soil where loyalists took root and plotted to burn down our fucking whited house, all for God and Country of course.

Philidor Rx Services LLC, which fills prescriptions for Valeant Pharmaceuticals International Inc., instructed employees to submit claims under different pharmacy identification numbers if an insurer rejected Philidor’s claim — to essentially shop around for one that would be accepted.

Employees were to first submit paperwork with Philidor’s national provider identifier, or NPI, and if that didn’t work were to then try with the NPIs of partner pharmacies, according to a Philidor training manual. “We have a couple of different ‘back door’ approaches to receive payment from the insurance company,” said the manual, dated October 2014.

“You will run across several insurances that we are not contracted with,” according to the document, which was obtained by Bloomberg News. In that case, “submit the NPI for our partner in California, West Wilshire Pharmacy,” the manual said. “There is a good chance they are contracted.” If that was denied, the next step was to “add the Cambria Central Fill insurance and run that as the primary,” apparently referring to a pharmacy in Philadelphia. “They should then get a paid claim and then Cambria, another one of our partners, will reimburse us.”

The document’s guidance on NPIs was first reported by the Wall Street Journal.

Valeant’s relationship with Philidor is at the heart of questions being raised by prosecutors, lawmakers and investors about the drugmaker’s operations and practices. Laval, Quebec-based Valeant has lost almost $10 billion in market value since a Wall Street short-seller on Oct. 21 suggested the company was using Philidor to pump up retail sales and engage in Enron-style accounting tactics. Valeant has denied the allegations.

Ron Hutcheson, a spokesman for Philidor, said the pharmacy is “the patient’s advocate in seeking to ensure that they receive the medication that was prescribed by their doctor at the lowest possible cost to them. This includes following up with insurance companies on behalf of patients.”

Calls placed after regular business hours to Valeant and West Wilshire in Los Angeles weren’t immediately answered. At Cambria Pharmacies, Stephen Bailkin, a manager, said, “I can’t imagine why anyone would be using my NPI number.” He declined to answer questions about Philidor and its relationship with Cambria.

I expect the stock to come under pressure tomorrow. Bill “Montauk” Ackman has his work cut out for him during his 10/30 morning presentation to defend these rascals.

Comments »

Pfizer in Talks to Acquire Allergen

The WSJ is reporting that Pfizer is in discussions to acquire AGN, which, if permitted, would catapult PFE to the 6th largest company in America by market cap.

The process is at an early stage and may not lead to an agreement, the Journal said. Pfizer has a market capitalization of about $219 billion and Allergan has a market value of about $113 billion. Joan Campion, a spokeswoman for Pfizer, said the company doesn’t comment on speculation, while Mark Marmur at Allergan didn’t comment.

A deal of this size is bound to have ripple effects, as the biotech industry reels from one heck of a fucked up tape. Perhaps this is the jolt needed to get the animal spirits going again. One thing is for certain, if this merger passes, PFE will be a force to be reckoned with.

Comments »

A Look at the Underbelly of this Market

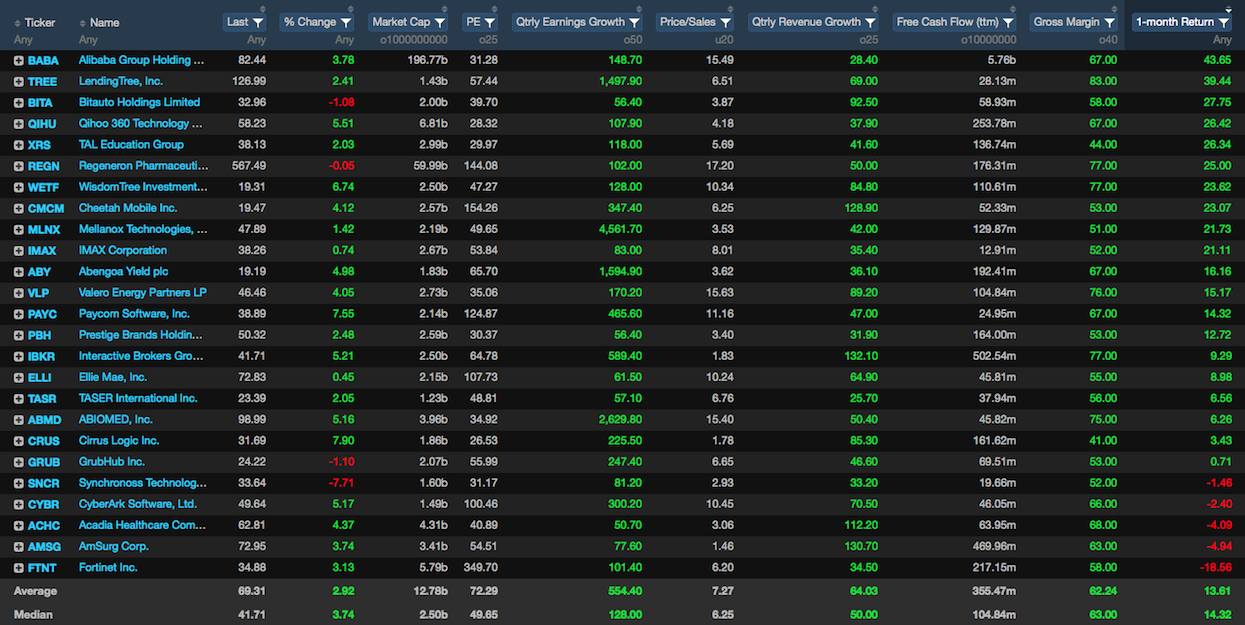
Inside of Exodus, there is a fantastic tool that permits users to profile the market based on fundamentals. I know, for you lazy clam shucking chart chompers, the word fundamentals beckons the days when you had to read, something disdainful to you. While this market is promoted by and pursued by chart licking illiterates, some of us still care about what these companies actually do.

To my point.

I ran screens to find a criteria that has produced the top performing stocks over the past month. The higher I went in market cap, the greater the returns. We already knew that, by simply witnessing the lack of muscle in the Russell. Then I tweaked the gross margins and found that too high was no good, the same for too low. They needed to be right in the middle, at 40%.

Price sales under 20.

PE over 25

Earnings growth over 50%. This was a huge game changer in the returns had over the past month, which paints a market that truly appreciates earnings.

Free cash flow over 500 million.

Now, individually, each screen produced dozens, if not hundreds of different stocks. But if you combined all of the criteria mentioned above, just one stock is produced.

BABA

Odd no?

Loosening the Mussolini type reigns on this screen, here are some additional ideas, based upon scientific fact, not conjecture or wanton opinion produced out of ignorance.

Profile

To put this into perspective, the median return for all stocks over the past month is 7.1%. The screen above produced a return double that. There will be outliers, like the fucking liars at GPRO, swindled by parasitic VCs, mountebanks, who rape and pillage the average Joe on a regular basis through a dizzying panorama of tommyrot IPOS. You’d be mindful to recuse yourselves from the litter of IPOs that is fanned out across the market, like shit in a catapult, by Morgan Stanley, Goldman Sachs, JP Morgan and others. Instead, why not focus on what’s been working?

If I am but one thing, I am a river to my people.

Comments »

RISE $TWTR, RISE

It personifies risk. As a company, Twitter is dysfunctional and stupid and wrong. Their leader gives zero fucks about it and is busy with his real company Square. He cares so little about TWTR that he just gave away 1/3rd of his entire stake, to disgruntled employees.

So if all of these things are true, why was TWTR the most important stock in the market today?

For one, it’s the most talked about, most visible amongst bulls and bears alike. Also, it represents the American brand of craziness that all of you have grown to mock and hate. And, lastly, it represents risk.

In the good confines of Exodus, TNA was flagged OVERSOLD yesterday. Look at her run today. The bounce we are getting today is more than just Apple. It included resurrecting the likes of Twitter from the dead, snatching it from its coffin, applying electricity to its body. At first it twitched and kicked violently, breaking its coffin and making a big fuss about the dirt around it. But, not before long, the mad scientist named Dr. Benjamin Bernanke, from the corner office at Citadel, brought life into the icy veins of Twitter and redubbed him FRANKEN-TWITTER (by now, FRANKEN-TWITTER was rampaging through Beartown, fucking shit up), whilst exclaiming “Bitch is a alive, it’s alive” in between marijuana induced coughs.

TWTR is my 3rd largest position as of the close and I have no idea where that last paragraph came from.

Comments »

An Evil Market

Realizing all of you have done nothing but bank “fuck you money” this year, I wanted to offer an alternative view of this situation. I believe this market to be hell on earth, a brand of evil not seen since the middle ages.  Similar to ancient torture devices, this tape has designs to “purify” its inhabitants and offer them up to the Lord in sacrifice.

Look over the landscape and you will see mangled automobiles, blown out buildings with body parts festooned on them. Those who’ve survived are shell-shocked, numb to the world around them. For avocation, they play russian roulette and blog all day long about how the devil is literally inside of the NYSE.

This message will reach someone, somewhere, who’s brand new to the market, punk rookie, uninitiated bozo the clown. He will scoff at my prose and chalk it up to “old man at the market” syndrome, whatever the fuck that is.

I missed out on massive SLCA gains; but made gains elsewhere. While it’s true, Exodus did flag oversold yesterday and I was 90% long heading into today’s tape, I have nothing but sheer disdain for everything this market represents, with its morbid predilections for pain and misery, thrusted upon the good folks of the United Steaks,

Comments »

Carl Icahn’s Love Letter to $AIG

You’ve got to love Uncle Carl, a million years old, like a vampire, energetic and trying to squeeze out that last billion or two before he goes.

Carl has a position in AIG. Now he wants changes and he wants them fucking now, God  damn it.

His letter to AIG:

Dear Peter:

It is my experience that in Corporate America, even when all available data points to the same undeniable conclusion and when all stakeholders desire the same mutually beneficial outcome, an external force is often still required to effect meaningful and positive change. This is the current situation in which AIG shareholders find themselves. The company continues to severely underperform its peers and is now facing an increasingly onerous regulatory burden which will only further erode its competitive position. Despite definitive action on the part of Congress and regulators to encourage this company to become smaller and simpler by splitting up, you have shown no sign of urgency and have chosen a “wait and see…for years” strategy void of decisive leadership. As a result AIG consistently trades at a substantial discount to book value. It is a “no-brainer” that the simple act of splitting this company up will greatly enhance shareholder value. AIG should immediately:

Pursue tax free separations of both its life and mortgage insurance subsidiaries to create three independent public companies. Each would be small enough to mitigate and avert the Systemically Important Financial Institution (“SIFI”) designation.
Embark on a much needed cost control program to close the gap with peers.
We believe there is no more need for procrastination, the time to act is now. I have already heard from several large shareholders who are frustrated with the lack of clear progress and are supportive of an AIG break up. I cannot fathom how you could ignore repeated requests from shareholders to execute a plan that would release billions of dollars of capital, free the company from onerous excess regulation, and leave shareholders owning stock in three separate, market leading insurance franchises.

“AIG is frankly overdue in following in the footsteps of all other major multi-lines in breaking up Life and P&C into separate companies. By separating into three independent companies, reducing unnecessary corporate overhead, operating at average industry returns, and buying back stock, AIG can trade at over $100 per share – 66% above its current $60 price,” John Paulson, President, Paulson & Co. Inc.

Too Big to Succeed

“We’re beginning to see discussions that these capital charges are sufficiently large it’s causing those firms to think seriously about whether or not they should spin off some of the enterprises to reduce their systemic footprint, and frankly, that’s exactly what we want to see happen.” Federal Reserve Chairman Janet Yellen, February 2014

Despite years of dismantling and selling non-core assets, AIG is still too large. The combination of life insurance and p&c insurance into a single entity offers no net benefit to shareholders (proven by industry low ROE), a fact that has driven other major multiline insurers to aggressively focus on a single line of business. We believe you must acknowledge that the current multiline strategy is not generating competitive returns. Separate monoline companies will be more focused, more efficient, generate better returns and, as a result, command significantly higher market valuations.

Additionally, “Because of AIG’s size and interconnectedness” the Financial Stability Oversight Council (“FSOC”) has deemed AIG a non-bank SIFI, subjecting the company to Federal Reserve oversight and increased capital requirements. We believe you must acknowledge that enhanced regulation is intended to be a tax on size, designed to approximate the cost that large companies impose on the financial system. The regulators have made clear that the best outcome is for SIFI’s to shrink and “reduce their systemic footprint.” If nothing is done, returns and AIG’s competitive position will continue to suffer as the SIFI regulation, including its costs and capital requirements, is fully implemented.

“The other way it [the FSOC Designation Process] can make the system safer is by providing an incentive for designated companies to change their structure or operations so they can reduce the risk they pose and change their designation and the amount of oversight. In many ways [this] outcome is more desirable than the first because it would allow business to find the more efficient way to reduce the risk they pose to the economy.” Senator Elizabeth Warren at Secretary Lew’s testimony before the Senate Banking Committee, March 2015

We believe you should immediately pursue, in the quickest and most efficient manner, a separation of both life and mortgage insurance from the core p&c insurance business. We believe all three companies would be small enough to avert the increased capital requirements and regulations associated with non-bank SIFI status. In the face of a changing and potentially punitive regulatory framework, you must realize that insurance businesses of AIG’s caliber are more valuable to shareholders if held directly than they are as part of a SIFI conglomerate.

Competitive Cost Structure

AIG’s ROE is below its peers not only because of size and capital constraints, but also because of lack of cost control. You have acknowledged that returns are below peers and must be improved, even going so far as to provide a long-term ROE goal of 10%, which is still below peers. At the same time you have suggested returns would not increase by more than 0.5% per year. Amazingly you have turned the quest for a 10% ROE into a half decade journey. The one thing we do agree on is AIG’s lack of competitiveness. Do you honestly think now is not the time for the inevitable AIG transformation? You must be proactive and commit to closing 100% of the ROE gap between AIG and its peers.

It is now incumbent upon you to explain why, despite pressure from the stock price, regulators, and shareholders, the company should not take immediate and transformative action. Achieving these two goals in combination with continued share repurchases is the only realistic path to a healthy and competitive company and, more importantly, exceed the potential of any alternative plan. AIG has taken too long already and we hope you come to the same conclusion. Time is of the essence. We look forward to engaging with management, the Board, and shareholders.

Sincerely,

Carl C. Icahn


When I grow up, I want to be just like Carl.

Comments »
Unforgiveable

I sold the best house in a bad neighborhood. The neighborhood got gentrified. Hipsters moved in. And now I want to place myself in a carnivale cannon and shoot myself into a red bricked wall.

Look at SLC, up 25%.

I’ve held this bastard for more than a year, rode it from $40 to $70, back down to drill bits. I averaged down in large quantities down here and capitulated ahead of their earnings report.

Why did I do that?

I drew a line in the sand and decided that I no longer wanted the pain that it was  doling out to me on a daily basis.  You have no idea how frustrated I am today.

I am pleased that the market is up 100 and that all of you are making money, children sucking on jollied ranchers, laughing at my plight. I will move on, like a locust, and destroy the next bear that I find. I will eat him whole (no homo) and enact the vengeance of 10,000 SLCA trades onto his entire bloodline.

Fuckitty fuck fuck fuck.

Comments »

Italy Sells Negative Yielding Notes For First Time Ever

Do you recall when Italian yields were blowing out in the summer of 2011? Had it not been for european QE, Italy, Greece, Spain, Ireland and France probably would’ve failed and the euro and all of the people who use it–fucking destroyed.

On Tuesday, Italy sold 1.75 billion euros of zero-coupon, two-year paper at a yield of minus 0.023 percent for the first time ever.

The lowest yield paid at an auction of Italian bills had already fallen into negative territory in April, when six-month debt fetched a minimum yield of minus 0.011 percent.

Wednesday marked the first time in which also the average yield and the maximum yields were negative.

This is in stark contrast with a record 6.5 percent yield Italy paid to borrow over six-months in November 2011, when concerns over its public debt — the world’s fourth-largest — mounted amid fears of a possible break up of the euro zone.

For those of you who swear QE does nothing: eat on that Italian sausage. QE saved the fucking world!

Italy, europe’s most indebted nation, can now MAKE MONEY while borrowing it. What a splendid way for the west to finance its way out of a mess, without actually having to do anything at all. Keep spending, eating, drinking, and borrowing. The plebs will pay you to take their money.

Comments »

CHINESE STEEL DEMAND EVAPORATING AT ‘UNPRECEDENTED RATE’

I am sure Janet Yellen and her board of retarded governors are reading this tonight, scratching their balls saying “hey, we should raise interest rates.”

Ahead of tomorrow’s Fed meeting, this sort of news can do nothing but help make the case for another round of QE

“Production cuts are slower than the contraction in demand, therefore oversupply is worsening,” said Zhu at a briefing by the China Iron & Steel Association. “Although China has cut interest rates many times recently, steel mills said their funding costs have actually gone up.”

China’s mills — the linchpin of the global industry, producing half of worldwide output — are battling against oversupply and sinking prices as local consumption shrinks for the first time in a generation. The fallout from the industry’s struggles is hurting iron ore prices and boosting trade tensions as China’s mills seek to sell their surplus overseas.

“China’s steel demand evaporated at unprecedented speed as the nation’s economic growth slowed,” Zhu said. “As demand quickly contracted, steel mills are lowering prices in competition to get contracts.”

Now I know what you’re thinking.

“Why do more QE, since it has done nothing for us thus far?”

Oh really? Your science if off, mate. Just because the economy isn’t booming 1999 style, that doesn’t mean QE did nothing. As a point in fact, one could make the argument that without QE the euro would’ve collapsed and all of our stupid, fucking, banks too.

The economy needs more easing because there is deflation. Once the Fed comes around to the facts, stocks will be crashing bears’ fucking skulls again.

Goodnight.

Comments »

Twitter Guides Lower; Stock Plunges, Because They Suck

This has to be the single most dysfunctional tech stock on the planet. No wonder why Fred Wilson sold his shares to the ordinary folk. These guys running Twitter are animals.

Revenue will be $695 million to $710 million, the San Francisco-based company said in a statement Tuesday. That compares with analysts’ average projection for $741.6 million, according to data compiled by Bloomberg.

In the third quarter, when Dorsey was still interim chief, the company’s user base grew 11 percent to 320 million, compared with a forecast for 324 million and growth of 15 percent in the prior period. In the U.S., the world’s largest advertising market, Twitter’s user count remained flat at 66 million.

“The lack of meaningful user growth will clearly be a long-term challenge for Jack Dorsey and his team,” Sweeney said.

Twitter shares slumped to $27.69 in extended trading, after rising 1.5 percent to $31.34 at the close in New York. The stock has slipped 13 percent so far this year.

I am long the stock in pretty decent size. The drop in the after-hours, all but wipes out my recent gains and places me in a position to really, really, ardently hate on the dick-smokers running TWTR into the dirt.

Granted,  Jack is now running the company and perhaps he can turn the ship around. But the crux of the issue with Twitter is the lack of new user momentum. Friends and family that I know think Twitter is the dumbest thing ever. Frankly, if you don’t have a defined genre of people worth following, like us in finance, Twitter is one of the most inane concepts to have ever been created.

Finance and news is where Twitter’s true value is. Management should circle the wagons around that and make this thing into a Facebook-like cash cow.

Comments »