It appears all of the worries about Asia, the credit crisis in China and disaster in Turkey, were imaginary–like friends. The market tends to scare people into giving up their wares, like stick up men, but without the guns.
Janet Yellen’s speech was written by Ben Bernanke, at least that’s what I like to believe. The idiots in Congress will not be able to frazzle her, as her IQ is at least 100 points higher than theirs. Therefore, one should expect markets to continue to trade up forever, without pause, and without any semblance of apprehension.
My reservations about the market have been proven to be wrong, in the immediate term. And I have to hold myself accountable for my haphazard actions.
I am watching Yellen and paying attention to her tone and cadence. If people sell stocks because of her Brooklyn accent, I can only surmise that we should buy that dip.
The biggest form of collateral for the average Joe is his jewelry. When a person in distress goes to a pawn shop, he pawns his gold ring/watch/necklace for a loan. When gold was ripping to the upside, the pawn dealers, like EZPW, DLLR and CSH soared–because loan volume went through the roof. In many cases, they (the publicly traded pawn shops) sold off the pawned jewelry or scrapped it for big profits. However, ever since gold has collapsed, the other side of the blade has victimized the shares of your locally publicly traded pawn shop.
“The Fly” is all about making a bit of coin off of the backs and struggles of the Obama proletariat.
This is what is going to happen to EZPW.
They just started selling wares on AMZN and other third party sites. Very soon, they will launch their own website, which will be “bonus money” for the company, helping to alleviate inventory builds. Year over year gold write-downs will wind down by the end of 2014, setting up for brand new growth in 2015. Ever since gold dropped, the size of their average loan has declined by 2/3rds, since everything else of value is inside of a never-ending deflationary vortex. I am talking about electronics, to be specific.
As you can see, gold is doing well this year. The pawn shops have already taken out any semblance of growth due to their gold collateral from their models, so any appreciable upside is gravy at this point. In other words, these are great retailers, tailor made for a society in flux, like ours. Once they get the gold situation fixed, I suspect share prices will explode–especially EZPW due to their online strategy.
Twelve months from now I expect to see EZPW trading in the mid-20’s and would be shocked to see it under $18.
Fun fact: Janet Yellen presides from my olde dwellings in the neighborhood of Bay Ridge Brooklyn, NY. She even went to the local high school, Fort Hamilton, which later on became a cesspool for the vagrants traveling from untoward parts of Sunset Park. Had I known she was from Brooklyn, I might have changed my mind about going to “extreme cash,” since people from Brooklyn are rather liberal. However, sometimes, every so often, they can stab you about the neck and chest for a pair of sneakers or even corduroys.
Hell, I recall being on the platform of the N/R train, in Bensonhurst, bearing witness to a pack of savages from FDR High School toss fellow children into the tracks, striking them with hammers, whilst singing “I’ve been working on the railroad.” True story.
I’ve come to the conclusion that I should begin buying stocks tomorrow, no matter what. I have 5 solid stocks, some distressed, others momo, that need to be purchased, regardless of whether Yellen stabs us in the neck of not.
Investing is for the living and cash feels like death.
I wanted to buy EZPW because their stores got hit post gold crash. With gold trading higher, it is the perfect way to play the yellow metal, indirectly. With ICPT trading higher, I wanted to buy GALT on Friday. And, as I’ve mentioned here on the blog, I deem SALE to be in the same league as YELP, perhaps a double from here. Oh, let’s not mention the 20% move in IFON, featured here last night.
Thus far, for me, 2014 is about missed opportunity. But I told you I’d hold 90% cash until after Yellen speaks tomorrow. After all, I am a man of my word.
TXTR, DLLR, CSH and ANGI are also of interest to me. And, with RPTP and GALT trading higher off the ICPT jump, CNAT may follow through. That’s all I have for you today.
So I made it this far without offing myself because of missed opportunities. I might as well wait another whole day to see what our new Chief of the Fed will say. My best guess is more of the same. There isn’t a reason for her to bend to the caprices of the market into a rally. As new Fed head, she needs to show the market who’s boss. Ben did it when he got the nod and the market hated him for it. We longed for the days of Super Nerd Allan Greenspan. However, that affection soon morphed into uncontrollable rage, as citizens of the proletariat blamed him for the entirety of the financial crisis, via his insane rate hikes.
I don’t want to sound like a broken record; but it’s entirely possible that Yellen, for lack of a better phrase, is insane.
Something to chew on as you buy chinese burrito accounting suprises.
This is a very bittersweet moment for me. On a plus side, I am genuinely happy to see the good folks at YELP do well. I live by their service and believe they are making the world a better place. Are you?
The bitter side of me laments YELP hitting $100 without me. Valuation borders of the obscene absurd. For the home gamers out there, that’s like a lot of craziness out there, so crazy it’s beyond reproach. But who am I to judge, as I am a simple-mere servant and slave to the markets? YELP is going higher because investors see the forest through the trees. They realize the business is worth many, many, many billions of dollars. As a matter of fact, it’s probably worth more than $10 billion– eventually.
I was long YELP since $14. I last sold it in the $60’s after promising not to. I broke my promise and that’s why I am stuck holding my testicles today.
There are many other YELP’s, by the way.
ANGI is so cheap; they can miss earnings and still go up. Another one to keep on your radar, for a long time, is SALE. They are to coupons what YELP is to reviews. They are killing it.
Lastly, I want to discuss diamond wire saws and why a certain stock is a buy because of it. But not just yet.
I was gonna buy it; but why bother? The market cap is so small, I’ll end up burying myself in a sea of illiquidity if this should seize up.
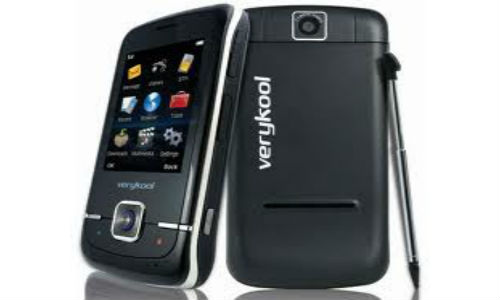
BEHOLD:
The VERYKOOL [sic] smartphone, made by IFON.
Here’s what I know:
Their suite of phones are entirely retarded, yet they seem to be selling quite a few in Latin American countries. Their market cap is a paltry $42 million and sales are ramping. According to their last earnings release:
“We shipped 477,000 handsets this quarter, a 166% increase compared to unit shipments in the particularly soft third quarter last year. Sales to customers in South America more than doubled, and sales in Central America increased by 59%. Our efforts to realign our cost structure reduced total operating expenses by 23% compared to the prior year period and produced a profitable quarter. We continued to refresh our product portfolio by expanding our Xtreme line of ruggedized handsets with the verykool®RS90 “Vortex” smartphone and introduced the verykool®s470 “Black Pearl,” a powerful smartphone with a quad-core processor, Android 4.2 and a 4.7″ HD screen.”
InfoSonics reported net sales for the third quarter of 2013 of $9.9 million, which represented a $4.5 million, or 84%, increase from $5.4 million for the third quarter of 2012. As noted above, net sales to carrier customers in South America doubled and sales to customers in Central America grew 59%. Sales were also strong to U.S. based distributors selling to customers in Latin America and Mexico.
Gross profit for the third quarter of 2013 was $1.8 million, a 60% increase from $1.1 million in the 2012 third quarter, reflecting the significantly higher level of net sales. Gross margin as a percent of net sales in the 2013 third quarter was 18.5% compared to 21.2% in the 2012 third quarter. The lower gross margin this year reflects the sale of slow moving inventory at reduced prices and margins, as well as a decrease of private label sales to customers in EMEA and APAC.
Operating expenses in the third quarter of 2013 of $1.8 million declined 23% compared to $2.3 million in the 2012 third quarter. Reduced spending in a number of areas resulted in a 13% decrease in selling, general and administrative expenses. R&D expenses fell by 58%, reflecting savings associated with the consolidation of our China development team earlier in the year into one location in Shenzhen.
Net income for the third quarter of 2013 was $34,000, or $0.00 per share, compared to a net loss of $1.2 million, or $0.08 per share, in the third quarter of 2012.
At September 30, 2013, the Company had $15.8 million in working capital, including $1.9 million in cash and restricted cash, and no outstanding indebtedness. Cash and restricted cash balances declined by $4.5 million compared to the June 30, 2013 balances primarily as a result of increased accounts receivable incident to the increased sales level.
If this trend continues, there’s no reason to believe it cannot trade at 1.5x sales, which is 50% higher than current levels, not to mention a much higher multiple can be affixed when extrapolating its recent growth rate. The truth is, I know very little about this name and just started exploring its potential. The market cap makes it too small for me to play in any significant way. But that shouldn’t preclude the pikers out there reading, who tend to experiment in the world of high finance, playing Gordon Gekko, with their 4 figure Zeeco accounts.
I haven’t been bearish in years. Aren’t I afforded the levity to run with this idea, or am I supposed to juxtapose my opinion against the fleeting masses– because they’ve become idle, fat, lazy, and somewhat apathetic to the world around them?
You’re all pigs.
There is something very specific you have to remember when perusing my blog: it isn’t for you. This is my diary, where I reflect on ideas and establish hard evidence of my genius and tomfoolery. Nothing was right about my trading this week. I ended January without any gains, after spring-boarding +8% within the first two weeks.
It’s like a child playing with firecrackers; a responsible adult takes them away. Well, I saw myself juggling sticks of dynamite and opted to remove myself from the situation. No one was harmed, as I never placed a bearish bet. As a matter of fact, my ANGI, RPTP and AREX sales were rather timely, as all stocks remain below my sell points, not to mention BALT too.
So, do yourselves a favour and reserve the smugness for your wives, the person who puts up with your endless flaws and poor personal hygiene. I am not amused, regardless of how clever you might think you’ve been.
All of the stocks that I was willing and able to buy yesterday and today (YY, WETF, DOV, MA, GALT, RPTP, just to name a few) have shot through the God damned roof. There isn’t anything cool about missing out on epic rallies. For the love of Sochi hotel accommodations, The PPT was screaming oversold earlier this week, the very algorithm that I created for the explicit purpose of helping me view the market objectively, yet I let my emotions cloud my judgement, and as such, I suck.
This isn’t a mea culpa, just an ordinary walk in the park with a man who’s rambling to himself.
Maybe I will crack next week, just before Janet Yellen throws saltine crackers at the market. Or, maybe I won’t. Maybe, just maybe, I’ll never invest again. This could be it, folks. “The Fly” may opt to quit investing and take up archery or maybe walk amongst the rocks of eastern Europe.
(BTW: I sold out of GOGO this morning out of sheer cowardice, locking in a 13% loss)
I have contractors in the house now, who need to be watched with very watchful eyes.
I just can’t pull the trigger. I am too comfortable on the sidelines, away from dangerous danger, and would rather go to church and pray for the market to implode than buy here and be wrong.
A great man once said “no balls, no babies.” To that end, I am sterile, a eunuch of sorts, blogging about the market without risking anything. It’s a wonderful thing and place to be: enjoy all of the excitement of the markets without having to incur personal hardship. The truth is, I cannot shake the bearish feeling. Might I add, this feeling has been wrong numerous times over the past 5 years. However, it served me well during the flash crash, having 30% of my assets long VXX into the maelstrom. It also served me well during 2008-2009, as I held a net short book and bet against all of the famous names like Lehman and Bear.
Maybe I’ll meet the market halfway and buy something defensive, larger cap. I have a tonne of money here doing nothing, collecting dust.
GTAT looks good off the AAPL news that they will use Sapphire. RBCN should be running tits on that news; but who wants to get long that bastard ahead of earnings? Certainly not I, or it might be my head in a basket.