Initially, everything melted up — in what could only be described as a post Trump short squeeze for the ages. The most significant gains have been found in construction and material stocks — up anywhere from 15-40% since November 8th. Second to the materials are the banks. Contrary to what the cucked media is saying, the banks aren’t going up because Trump is secretly a Wall Street shill. The banks are going up for one simple reason: the yield curve has steepened from 80bps to 129bps. For a banker, that spread is pure profit.
While the gains enjoyed by these sectors steal the headlines, I think it’s important to take note of the broad market cap gains across the biggest sectors, in order to assess a true and pure analysis of the gains.
Sector/Collective Mkt Cap/1mo Return
Drugs – Major/2.1t/+1.8%
Major Oil/1.68t/+6.5%
Internet Info providers/1.57t/+1.88%
Money Center Banks/1.38t/+17.5%
Chinese Burritos/1.3t/-1.1%
App Software/1t/-0.16%
Conglomerates/965b/+6%
In short, if you weren’t long a bunch of banks or oil stocks over the past month, your portfolios marked time. As a point in fact, out of $10 trillion in market capitalization in the aforementioned sectors, just $4 trillion of them enjoyed gains more than 2%.
The biggest losses were endured in gold and foreign utilities (currency fuckery), down 16.5% and 15.9%, respectively.
Over the past two weeks, the rotation and dichotomy of the market was much more pronounced.
Sector/Collective Mkt Cap/2 week Return
Drugs – Major/2.1t/-4.1%
Major Oil/1.68t/+5.9%
Internet Info providers/1.57t/-2.3%
Money Center Banks/1.38t/+3.4%
Chinese Burritos/1.3t/-1.25%%
App Software/1t/-2.4%
Conglomerates/965b/+1%
The biggest losses were endured in shipping and biotech, down 9.7% and 7.8%, respectively.
Not too healthy, eh? The market isn’t a zero sum game. Gains are merely transferring from one sector to the next — frustrating momentum traders with classic misdirection.
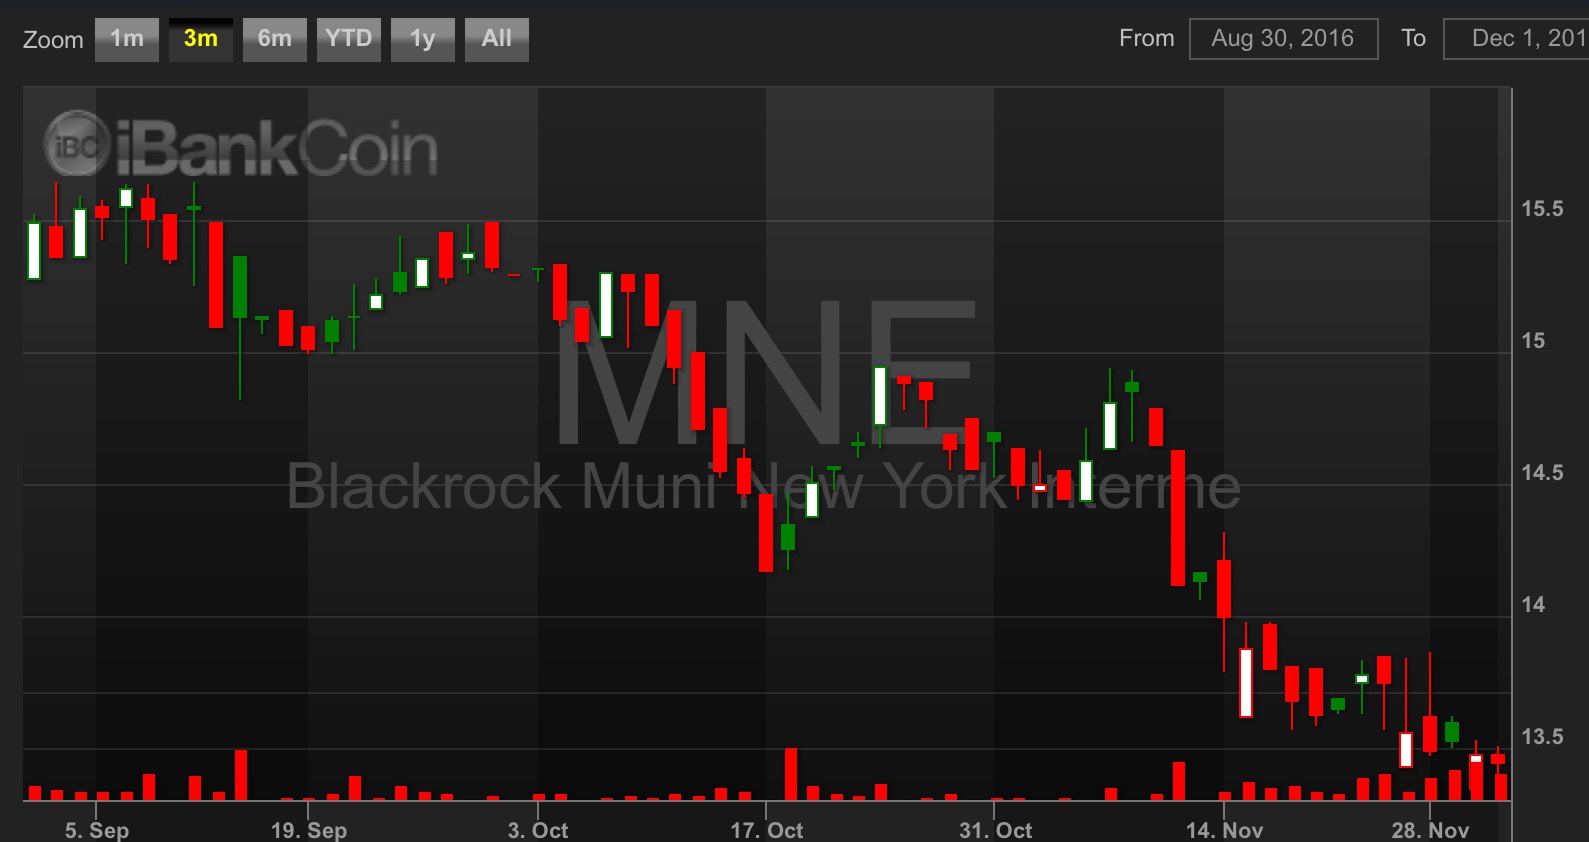
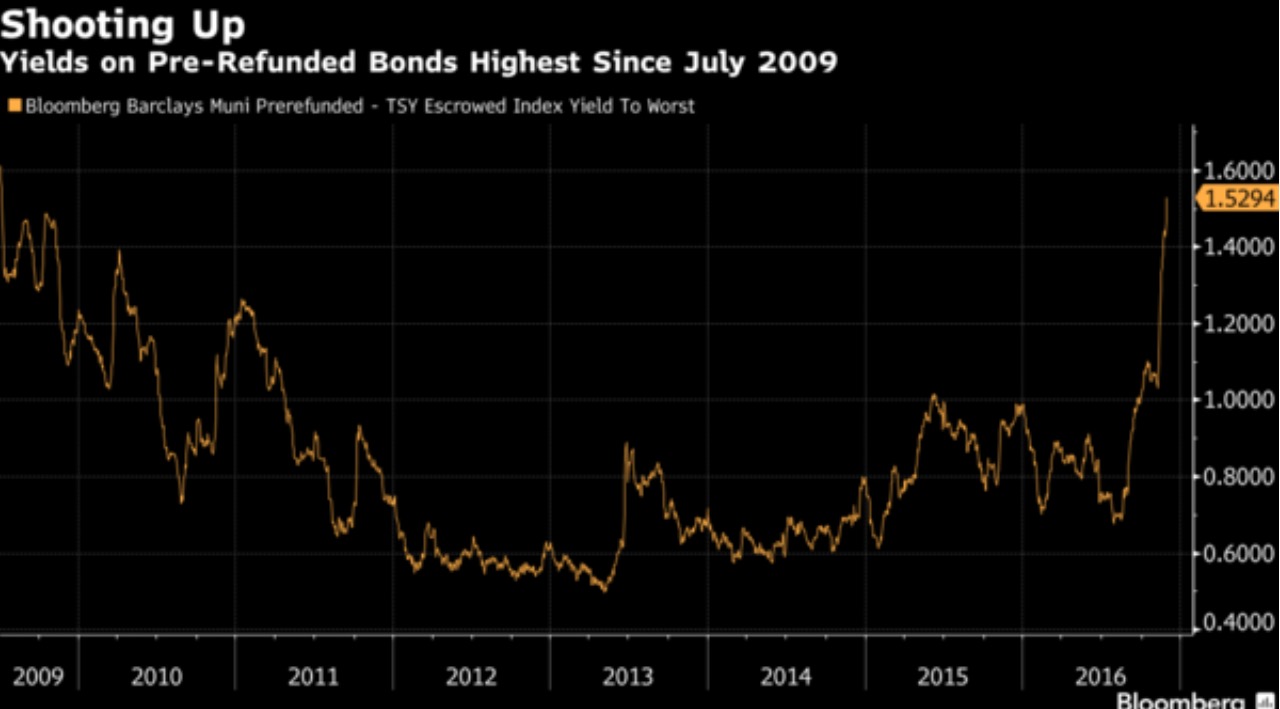
It’s also worth noting, the biggest market of all, the bond market, has been ravaged — with losses in TLT at 9.3% over the past month and -2% over the past two weeks.
Comments »