iBankCoin
Home / Dr. Fly (page 1026)

Dr. Fly

18 years in Wall Street, left after finding out it was all horseshit. Founder/ Master and Commander: iBankCoin, finance news and commentary from the future.

Third Point Posts 4.6% Return in Q2, Led By High Yield Energy Bets

Dan Loeb, aka Mr. Pink_esq, booked a huge return for the second quarter, reversing his short bets in the energy sector and getting long over $1b–into the teeth of CHK bankruptcy rumors.

Loeb conducted all of these acts of heroism and financial winship in the month of February, a time when most managers were soiling themselves, neck deep in losses.

He sold out of AMGN, mainly because it bored him and continues to hold large bets in both AGN and BAX, which is his largest holding.

“The year’s positive performance reflects contributions from nearly all of the strategies we employ; the top five winners include a constructive long equity position, a sovereign debt investment, high-yield debt investments in energy companies, an event-driven long position, and a short equity position in the pharmaceutical industry,” Third Point said.

Third Point has played 2016 like a fine tuned violin this year, almost perfect. God willing they will flail and then implode in the quarters to come.

Comments »
NIKKEI SOARS ON REPORTS OF MASSIVE STIMULUS PACKAGE

The yen is plummeting this evening on rumors that Japan will undertake a massive 27t yen stimulus package, which is 5x the amount previously discussed. The Yen is currently trading 105.86 vs the dollar, down 1.17%. The NIKKEI is responding, in kind, higher by more than 2.2%

These fucked up rumors of degeneracy include the launch of a comical 50yr bond, 13t in low interest loans (also comical) and an explicit intent to cause inflation, which is the most comical of them all.

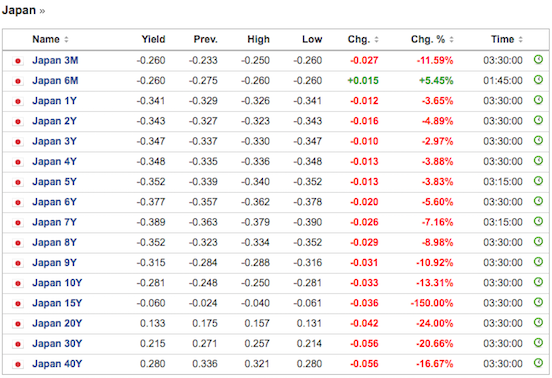
Interestingly, Japanese bonds are now raging higher, which is pushing yields even further into negative territory. Might I add this is, by definition, deflationary.

Japan

Comments »

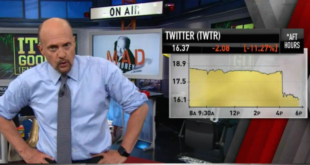
Cramer to @Jack: Pick a Dog, Square or Twitter

This evening on Maddening Money, Cramer discussed how it’s okay for growth to be non-existent and how ‘good enough’ is enough to propel stocks to record highs. He was laying on his Orwellian propaganda good and heavy this evening. Then he discussed the disappointments in the market and touched on  a point that is rarely discussed, regarding Twitter.

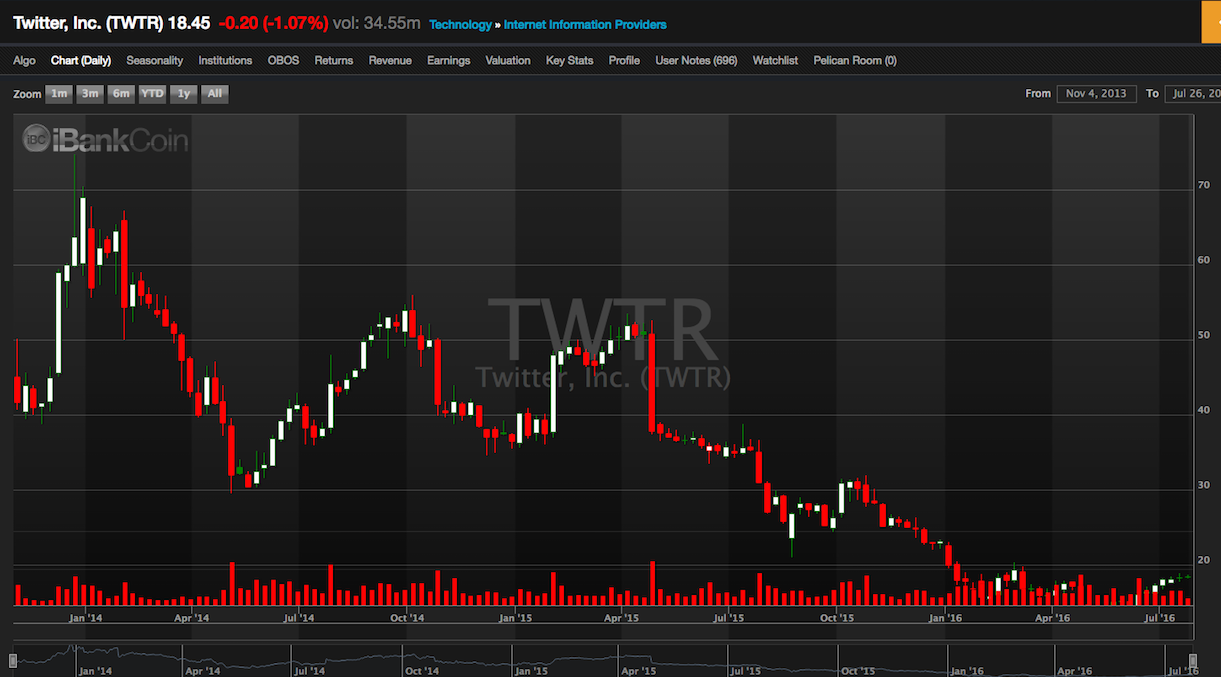
The CEO, Jackard Dorsey, is presiding over not one but two companies, into the ground. Year to date, both TWTR and SQ are maligned with large losses, in excess of 20%. Since Jackard took over the role as CEO of Twitter, the shares are down 55%.

Cramer makes a valid point, when he states “it is time for Jack Dorsey to pick Twitter or Square. It’s bad enough  he’s CEO of one underperforming company, but to be CEO of two troubled entities. Please, one or the other, but not both.”


Comments »

$AAPL Beats, Guides Higher, Reveals Lackluster Growth and Margins

Tim Cook did it again, sort of. The company posted better than expected results, and even guided up. Margins were a little soft. But who really gives a shit about that?

From a layman’s viewpoint, those iPhone sales are looking awfully PCish, coming in at 40.4, down from 47.5 last year. Growth has slowed to the point that this is now a financial engineering company, one that will benefit from cost cuts. Apple is the new Dell.

  • Reports Q3 (Jun) earnings of $1.42 per share, $0.04 better than the Capital IQ Consensus of $1.38; revenues fell 14.6% year/year to $42.36 bln vs the $42.1 bln Capital IQ Consensus; gross margins of 38.0% vs 37.9% ests vs 39.7% last year.
  • iPhones 40.4 mln vs 40.2 mln ests vs 47.5 mln last year.
    • iPads 9.95 mln vs 8.7 mln ests vs 10.9 mln last year.
    • Macs 4.2 mln vs 4.6 mln ests vs 4.4 mln last year.
  • Americas rev -11%; Europe -7%; China -33%; Asia/Pac -20%.
  • Co issues upside guidance for Q4, sees Q4 revs of $45.5-47.5 bln vs. $45.8 bln Capital IQ Consensus Estimate; gross margin 37.5-38% vs. 38.3% ests.

Shares are higher in the after hours by 5%.

Comments »

Twitter Shaves Q3 Guidance; Shares Collapse in the After Hours

Any way you slice it, these numbers were an abomination. They aren’t adding new users, even with their fake bot creating machines. The company just guided revenues down by an astounding $90 million and they’re far from being free cash flow positive. One must ask the question: is @Jack the one to lead this company?

The bottom line is this: On June the 10th, 2015, the day Jack Dorsey took over Twitter as CEO, the share price was $36.85. Right now, in the after hours, the stock is trading at $16.70 (-10.5%), down 53% since his reign of terror began.

TWTR


  • Reports Q2 (Jun) earnings of $0.13 per share, $0.04 better than the Capital IQ Consensus of $0.09; revenues rose 19.9% year/year to $602 mln vs the $607.41 mln Capital IQ Consensus.
  • MAUs
    • Average monthly active users (MAUs) were 313 million for Q2, up 3% year-over-year and compared to 310 million in the previous quarter.
    • Average U.S. MAUs were 66 million for Q2, up 1% year-over-year and compared to 65 million in the previous quarter.
    • Average international MAUs were 247 million for Q2, up 4% year-over-year and compared to 245 million in the previous quarter.
    • Mobile MAUs represented 82% of total MAUs.
  • Revenue Breakdown
    • Advertising revenue totaled $535 million, an increase of 18% year-over-year.
    • Mobile advertising revenue was 89% of total advertising revenue.
    • Data licensing and other revenue totaled $67 million, an increase of 35% year-over-year.
    • U.S. revenue totaled $361 million, an increase of 12% year-over-year.
    • International revenue totaled $241 million, an increase of 33% year-over-year.
  • Ad Engagements
    • Total ad engagements were up 226% year-over-year.
    • Cost per engagement (CPE) was down 64% year-over-year.
  • Co issues downside guidance for Q3, sees Q3 revs of $590-610 mln vs. $681.34 mln Capital IQ Consensus Estimate.
  • For Q3: 
    • Adjusted EBITDA to be in the range of $135 to $150 million;
    • Stock-based compensation expense to be in the range of $165 to $175 million.
  • For FY 2016 expect:
    • Capital expenditures to be $300 to $375 million (Prior $300-425 mln);
    • Adjusted EBITDA margin in the range of 26-27% (Prior 25-27%).

Comments »

Can Jack Save Twitter?

Some believe Jack Dorsey, CEO of Twitter, is the second coming of Marissa Mayer. Others believe he’s a tech and marketing genius, biding his time, waiting to strike the market with a white hot number that will send Twitter spiraling higher. Very recently, Jack’s good name was maligned for a sundry of free speech concerns. However, speech isn’t necessarily free, as the very apparatus by which this freedom is used is to serve money.

Let’s see if Jack can make some money for his shareholders.

Earnings pending.

Comments »

$ADI ACQUIRES $LLTC for $14.8 BILLION, OR $60 Per Share

The renaissance in the world of semiconductor stocks is clearly upon us. After years of struggle and being beguiled by profit margins and the idiosyncracies of Apple, investors have ceased to care and have bid up the sector to fantastic levels. Analog devices is taking advantage of suchness, and has decided to acquire a lowly competitor for the pedestrian sum of $14.8b.

The co’s announced that they have entered into a definitive agreement under which Analog Devices will acquire Linear Technology in a cash and stock transaction that values the combined enterprise at approximately $30 billion. Upon completion of the acquisition, Analog Devices will be the premier global analog technology company with approximately $5 billion in anticipated annual revenues.

  • Under the terms of the agreement, Linear Technology shareholders will receive $46.00 per share in cash and 0.2321 of a share of Analog Devices common stock for each share of Linear Technology common stock they hold at the closing of the transaction. The transaction values Linear Technology at approximately $60.00 per share, representing an equity value for Linear Technology of approximately $14.8 billion
  • The transaction is expected to be immediately accretive to Analog Devices’ non-GAAP EPS and free cash flow. Analog Devices expects to achieve $150 million of annualized run-rate cost synergies within 18 months post transaction close
  • Closing of the transaction is expected by the end of the first half of calendar year 2017

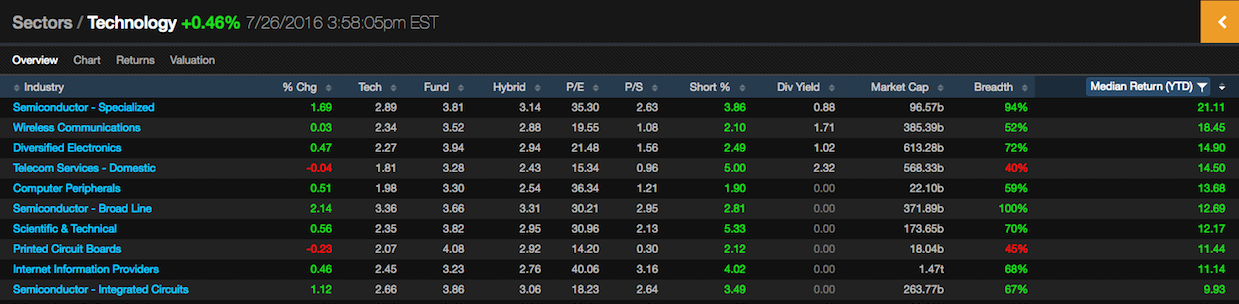
YTD, semis have been, by far, the best performing stocks in the tech sector.

Semis

Comments »

CNBC Host Attacks Peter Schiff for His Bonds

Only in the world of finance is this remotely interesting. They were having a heated debate about the Fed and how Peter Schiff believed there was no way in red hell they’d hike rates again, until Scott Nation stepped in with soviet era styled propaganda, maligning one of Peter Schiff’s bondless bond funds.

S. Nation discussed how fucked up Schiff’s dystopian world view was, as we suck the tarmac off all time, record, highs, and they were having a very cordial back and forth, with Schiff repeating his end of days jargon etc. Then Mr. Nation upped the rhetoric and totally shit on his underperforming bond fund.

You best diversify your bonds, Peter.

Comments »

Stifel Downgrades 11 Restaurant Stocks, Says Recession is Coming Soon

Paul Westra from Stifel didn’t just downgrade a bunch of eateries today. He’s predicting an absolute, terrifying, doom in the US economy. He cites restaurant stocks as the singular bellwether for the retail consumer. With comps heading lower, it can mean just 1 thing: recession.

image

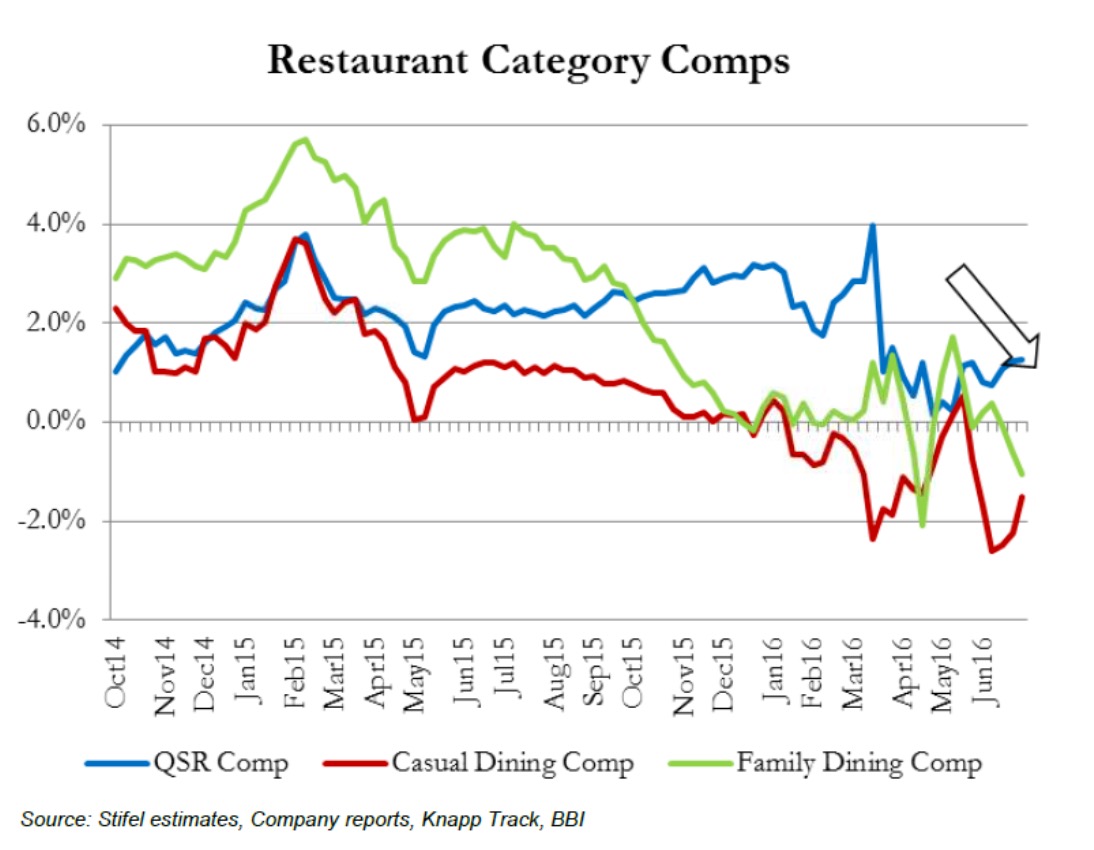
“Today, we adopt a bearish outlook for restaurants as we confidently believe that, at a minimum, the simultaneous -150 basis points to -200bps deceleration of restaurant industry comps across all categories during the second quarter within our most recent Stifel Sales Survey reflects the start of a U.S. Restaurant Recession,” Westra and his team said in a note.

This doesn’t just bode ill for restaurants, but could point to trouble across the economy as a whole. A downturn in dining could be implying a U.S. recession as soon as early 2017, he said, since “restaurants have historically led the market lower during the three to six-month periods prior to the start of the prior three U.S. recessions,” Westra adds.

Since he isn’t singling out one particular area of the industry, he is downgrading shares of 11 different companies including Chipotle Mexican Grill Inc., Darden Restaurants Inc., The Cheesecake Factory Inc. and Zoe’s Kitchen Inc. According to his research, industry peers are slowing down across all sub-industries. Here’s a chart with quick-service restaurants (QSR), casual dining and family dining.

A few things are at play here. Maybe it’s all the civil unrest, fear of a neighborly head chopping terrorist attack or something worse. Personally, I believe Americans have transcended food and can sustain themselves off the blood of their enemies alone. All of these predictions of doom only feed into this clamoring for more blood, as markets, tirelessly, climb higher. Very soon, the good folks over at CMG will launch a catapult attack on the Stifel HQ, infecting them with a barbarous strain of ecoli, shutting their pie holes for good.

Comments »