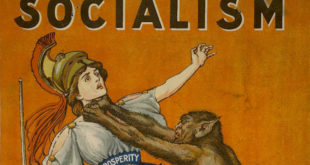
You’d expect an advisory firm to shit on index ETFs in a report saying they’re worse than Marxism. Index ETFs have only grown in popularity thanks to the underperformance of professional asset managers. There is, however, a much graver threat to our form of crony capitalism that is rarely discussed, one that the eggheads from Bernstein skipped over.
In a note titled “The Silent Road to Serfdom: Why Passive Investing is Worse Than Marxism,” a team led by Head of Global Quantitative and European Equity Strategy Inigo Fraser-Jenkins, says that politicians and regulators need to be cognizant of the social case for active management in the investment industry.
“A supposedly capitalist economy where the only investment is passive is worse than either a centrally planned economy or an economy with active market led capital management,” they write.
Fraser-Jenkins notes that the rise of indexing should theoretically entail that stocks tend to move in the same direction more often (though such a simple relationship isn’t necessarily borne out by the data), and cites research indicating that “if the correlation of stocks increases then that impedes the efficient allocation of capital. That is, there isn’t as big of a difference in capital expenditures on a sector by sector basis than what would be expected based on relative profit growth.
The social function of active management, in a capitalist society, is that it seeks to direct capital to its most productive end, facilitating sustainable job creation and a rise in the aggregate standard of living. And rather than be guided by the Invisible Hand and profit motive, capital allocation under Marxism is conducted by an oh-so-visible hand aimed at producing use-values that satisfy each member of the society’s needs. Seen through this lens, passive management is somewhat tantamount to a nihilistic approach to capital allocation.
“The commonality between both active market management and the Marxist approach is that in both cases there are a set of agents trying – at least in principle – to optimize the flows of capital in the real economy,” writes Fraser-Jenkins.
Bernstein’s team isn’t asking for governments to bail out active managers, but merely advises that lawmakers and regulators “may wish to consider the broader benefits of a functioning active asset management industry to society as a whole so that when policy initiatives are undertaken they do not explicitly undermine active management.”
Let’s talk about Serfdom, Fraser-Jenkins. While SPY or QQQ ETFs might muddy the waters, lumping in great companies with shitty ones, there is a much greater, invidious, force out there that is misallocating capital on an unprecedented and monumental scale. It’s called QUANTITATIVE EASING.
I discussed this last night, in a missive against the BOJ. The ETFs are merely the vehicle towards the socialization of markets. QE, or the creation of money for the explicit purpose of manipulating markets, is the fuel.
There cannot be a market if the game is rigged. With the ECB and the BOJ artificially causing yields to drop, we are bearing witness to a melt up in equities, driven by passive investments in major ETFs, as investors search for yield. In Japan, their schemes are far more advanced and egregious, as previously noted. While the existence of index ETFs might be inconvenient for the asset management industry, its deleterious effects on capitalism pales in comparison to the degenerate central bank schemes of QE.
Get real Bernstein.
Comments »