iBankCoin
Home / 2016 / May / 24 (page 2)

Daily Archives: May 24, 2016

Snapchat Raises New Capital at 70x Sales

Snapchat is a cool app. All of the brainless kids love it. Therefore, venture capitalists are free to affix any valuation they feel is appropriate to it. After all, it’s the next big thing.

So, they raised new money at a $22 billion valuation. According to re/code, Snapshit will do $300-350 million in revenues for 2016, placing their price to sales ratio just about 70x. To put this into perspective, Facebook is trading about 20x and at the highest peak of the social media bubble, Twitter and others might’ve touched down at around 30x. But, for the most part, 20x sales is super bubble territory.

Because the first social media bubble worked out so well, investors figured Snapshit could be worth whatever they wanted it to be worth. For now, 70x sales will suffice.

This new financing, we understand, is a follow-on to the $175 million Series F round led by Fidelity. Snapchat was said to be valued at $16 billion in that round, flat on the year before. However, filings from earlier this month and embedded below, uncovered for us by market analysts VC Experts, show that the Series F was expanded.

Based on a share price of $30.72 per share — which VC Experts tells us was the value disclosed in an earlier Fidelity Fund filing related to its Snapchat investment — and assuming all of the authorized shares are issued, the more recent valuation could be as high as $22.7 billion. Authorized shares do not always all convert to issued shares, but this gives us a range that fits in with what we’ve heard about the $20 billion valuation.

Expanding the Series F with a Series FP, as it’s described in the document below, would also fit in with a description we’ve heard more than once about Snapchat’s fundraising: The startup is “always raising” on a “rolling” basis, partly because investors are so interested.

“They get offers all the time,” one investor close to the company said. “And once you start to grow on this path, many people come to give you money. You don’t know how to value the company, so the best way to do that is to do some kind of rolling funding. When you have a hot company and many people are approaching you, you do a market of discovery.”

Besides Fidelity, other existing investors in the company include Alibaba, which led its Series E; Benchmark (Series A lead); Coatue Management (Series C lead); General Catalyst; IVP (Series B lead); Saudi investment group Kingdom Holding Company; KPCB (Series B lead); Lightspeed (Snapchat’s earliest and most constant investor); SV Angel; WeChat owner Tencent and Yahoo. We hear that many existing investors are looking to participate in this new round, including Spark Capital

Ooh, the Saudi Prince from Kingdom Holdings is an investor, alongside a sundry of Chinese investors, such as Tencent and Alibaba. What can go wrong?

Comments »
Best Buy Beats Estimates, Warns on Bottom Line

Anyone need a good phonograph…from China. If so, BBY is your place. Ever notice how utterly lost this company is, especially when getting lost inside of their stores of antiquated electronics?

Best Buy just reported decent numbers, but warned for their bottom line going forward.

The company reported solid comps for appliances and a 23% spike in online sales. However, mobile phones, services and computers were abysmal. Most importantly, the companies main source of earnings improvement lies in their share repurchases. They’re blaming Japan’s earthquake for their earnings warning, but slightly offset by their absurd buybacks.

image

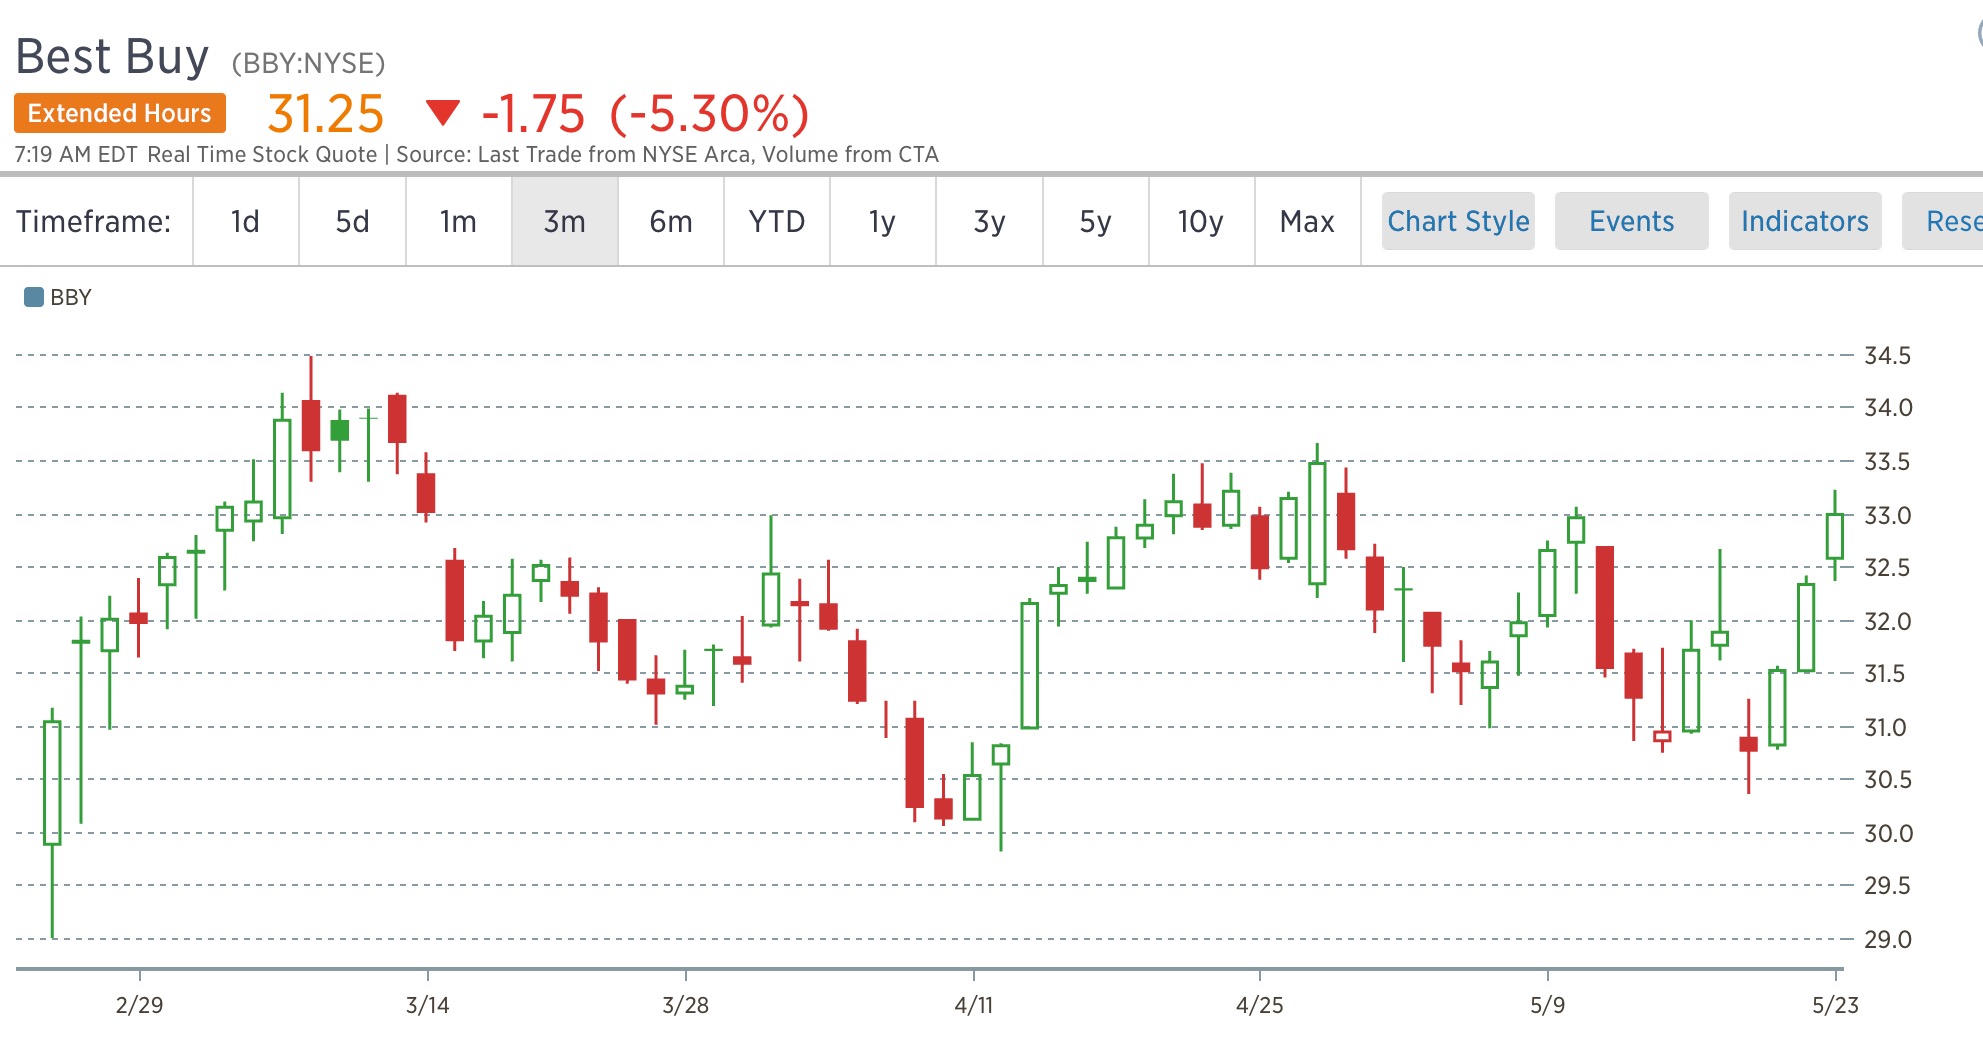
07:11 | BBY | (33.00)
Best Buy beats by $0.09, beats on revs; guides Q2 EPS below consensus, revs above consensus; reaffirms FY17 guidance; CFO Sharon McCollam to step down; Strategic Growth Officer Corie Barry named new CFO

Reports Q1 (Apr) earnings of $0.44 per share, excluding non-recurring items, $0.09 better than the Capital IQ Consensus of $0.35; revenues fell 1.3% year/year to $8.44 bln vs the $8.3 bln Capital IQ Consensus.

Comparable sales were essentially flat (-0.1%) vs. (2)-(1%) guidance against a backdrop where the NPD-reported categories were down 1.9%.

From a merchandising perspective, comparable sales growth in health & wearables, home theater, major appliances and computing was offset by declines in mobile phones, tablets and gaming. As expected, television sales related to the shift of the Super Bowl into Q1 FY17 positively impacted the Domestic segment by ~70 basis points. The company also saw continued revenue declines in services due to investments in services pricing and the reduction of frequency of claims on extended warranties which has reduced repair revenue.

Consumer electronics comps +5.6%; computing and phones -3.5%; entertainment -11.6%; appliances +14.3%; services -10.7%.
Domestic online revenue of $832 million increased 23.9% on a comparable basis primarily due to higher conversion rates and increased traffic. As a percentage of total Domestic revenue, online revenue increased 210 basis points to 10.6% versus 8.5% last year.

Co issues guidance for Q2, sees EPS of $0.38-0.42, excluding non-recurring items, vs. $0.50 Capital IQ Consensus Estimate; sees Q2 revs of $8.35-8.45 bln vs. $8.31 bln Capital IQ Consensus Estimate.

“In line with our original expectations, there are two factors impacting our year-over-year non-GAAP EPS guidance for the second quarter. First, we are expecting an approximate $0.03 net negative impact from the lapping of the periodic profit sharing benefit from our services plan portfolio that we received in the second quarter of last year. Second, we are expecting an approximate $0.06 negative impact from the carryover of last September’s services pricing investment. In addition, in digital imaging, we are now expecting an approximate $0.03 to $0.04 negative impact due to the April 2016 earthquake in Japan, which is impacting inventory availability in this high-margin category. Combined, these are putting $0.12 to $0.13 of pressure on Q2 FY17, which will be partially offset by an approximate $0.04 benefit from share repurchases.”

“We are reaffirming our previously provided full year financial outlook which includes ~flat revenue and non-GAAP operating income, with non-GAAP EPS growth [consensus +3.2%] driven by share repurchases. Although we are reporting better-than-expected results today, we are not raising our full year outlook as the first quarter represents less than 15% of full year earnings and at this stage we have no new material information as it relates to product launches throughout the year.”

Sharon McCollam, the company’s chief administrative and chief financial officer, will be stepping down on June 14, 2016. McCollam will remain with the company in an advisory capacity until the end of the fiscal year, January 28, 2017, to ensure a seamless transition. Corie Barry, a 16-year veteran of Best Buy and its current chief strategic growth officer, will become the company’s chief financial officer at the conclusion of Best Buy’s annual shareholder meeting, being held on June 14.

In lieu of these numbers, Citi downgraded BBY to neutral.

Comments »

Iron Ore Falls to March Lows

It truly is collapsing, but I didn’t want to give any of you heart attacks before tomorrow’s trade. It might prevent some of you from liquidating your portfolios and causing an even greater decline.

Iron ore represents China in all of its grave depravity. Now we have the price dropping to the lowest point since March the 3rd, at the same time copper keeps dropping too. There is a discernible cause for panic amongst China bulls. By extension, all of you should panic too.

“There’s little doubt that the iron ore price will sink below $50 a ton as seaborne supply is rising while the Chinese steel mills will reduce purchases,” Ren Jiaojiao, an analyst at Maike Futures Co., said by phone from Xi’an on Tuesday. Inventories at China’s ports — which topped 100 million tons last week — may increase further, according to Ren.

“The run-up in April was fueled partly by purchases from steel mills ramping up production to capture the exceptionally-high profit margin,” said Ren. But that margin is now “quickly contracting, so mills are adjusting to the new situation by depleting their raw material inventories first. They will also adopt a hand-to-mouth strategy in purchases later because of anticipation of higher supply at the ports.”

Ore with 62 percent content sank 6.7 percent to $51.22 a dry metric ton on Monday, the lowest since March 3, according to Metal Bulletin Ltd. After surging 23 percent last month as China’s ill-fated frenzy gathered pace, the price has tumbled by the same amount so far in May. Futures in Dalian fell as much as 2.6 percent on Tuesday, while the SGX AsiaClear contract was little changed.

Citigroup Inc. said in a report on Tuesday it remained bearish on iron ore, forecasting persistent oversupply on rising output from the top miners as well as Gina Rinehart’s Roy Hill project. At the same time, weaker steel prices will encourage mills to restrain output and keep ore holdings low, it said.

“Oversupply should extend into the rest of 2016,” Citigroup said, predicting that prices will average $47 a ton this year. “Weaker steel prices should incentivize mills to decrease utilization rates and maintain low iron ore inventories, putting pressures on Chinese iron ore imports.

Talking about iron ore and how doom is beckoning gets boring sfter a while. Not before long, the cat calls shrieking from this bloggery must be backed up with actual calamity. Don’t worry lads, recession is an assured outcome. Give it a chance. You might like it.

Comments »