iBankCoin

Greenlight Capital Taking Another Beatdown

When last updated, Greenlight Capital reported a year to date loss of 16.3%. However, judging by his positions and deepening losses in some of his top holdings, one has to wonder how deep can the rabbit hole go?

Greenlight


NOTE: Apple, which isn’t listed above, was his top holding in recent filings.

Greenlight Capital was up 19% in 2013 and 8% in 2014, so this year’s losses aren’t exactly typical. Nothing about 2015 is typical, with traditional correlations and trends being tossed into Sesame Streets garbage can for Oscar to fiddle with. Nevertheless, I think it’s important to accentuate the losses of industry professionals, like Ackman and Einhorn, to paint an accurate picture of just how difficult 2015 has been. Judging by the YTD status of the major indices, one would think it was a boring year.

Pffff.

Comments »

I AM BEING ACK, ACK, ACK ATTACKED

This fucking PAH position has become an albatross around my neck. Thanks to my faith in William Albert Ackman, I am being dismantled in this fucking PAH position. His losses deepen in VRX, daily, and anything related to Ack is getting shredded. This is a horrendous year, a comeuppance if you will, for the hot shot hedge fund manager. Guys like Einhorn, Ackman and Paulson are having their lunches eaten for them. It’s as if Gordon Gekko himself was gunning for them, trying to send them mail COD.

Thank God I am in COST, otherwise my book would be suffering the fate of 10,000 hells right now, as my SHAK, PAH, FCX, CNC positions melt away like a candle in an inferno. This market fucking sucks.

That being said, I am merely positioned wrong, so I can’t get too upset over my childish stupidity. My SBNY position is ripping mammaries straight off the torsos of anyone in its path. The smart trade, ahead of the jobs numbers, was short commodities, long banks. I’ve said it here 1,001 times: when rates go up, banks will rally, due to the steepening of the yield curve.

What did I do?

I bet on Bill “Fucking” Ackman.

FML

Comments »

European Bond Yields Sink Deeper into Negative Territory

Say what you want about this environment, how fucked up it is with western government saddled with insurmountable amounts of debt, fueled by QE. But what the western bankers have accomplished here is nothing short of a miracle.

By hook and crook, they’ve convinced the world is lend them money, bullshit economies with fucked up demographic trends, and PAY THEM for the pleasure of doing so.

Imagine taking out a mortgage and the bank paid you for lending you money. Sounds bizaare, no?

Theoretically, the more these countries borrow, the more they stand to make. The profits from these exploits can, in fact, be used to pay down the debt. Talk about fuckery on a largess scale.

Here is a chart of all the European 2yr bond yields. It truly is something to behold.

image

Food for thought, mostly all of those countries have better borrowing costs than the U.S., whosr 2 yr bond yields stand at 0.86%. With European QE in full retard mode, yields have been diving lower, pretty consistently. It’s very possible that 10yr yields will soon be negative too.

Alas, the wonders of being a central banker.

Comments »

The Theranos Drama Just Thickened, in a Big Way

The WSJ is out with another expose on Theranos, their favorite whipping pole in a seemingly endless field of privtely held whipping poles.

The crux of the issue is the fact that Theranos’ main pitch product, the tiny little prick of blood being able to replace drawing tubes from the arm, is 100% horseshit.

Now it’s being revealed that Safeway is taking a serious L on a joint venture they had planned, which begs the question: what the fuck were they thinking?

Safeway Inc. spent about $350 million to build clinics in more than 800 of its supermarkets to offer blood tests by startup Theranos Inc.

But the tests never began, the clinics are now used largely for flu shots and travel-related vaccines, and the two companies have been negotiating to officially dissolve their partnership, according to people familiar with the matter.

Current and former Safeway executives said Theranos missed deadlines for the blood-testing rollout. They also said several Safeway executives questioned the accuracy of results Theranos gave to Safeway employees tested at a clinic in the supermarket chain’s headquarters in Pleasanton, Calif.

Safeway was a big growth opportunity for Theranos, based in Palo Alto, Calif. The project, code-named “T-Rex” at Safeway, hasn’t been publicly disclosed by either company but goes back to at least 2011.

The deal was struck before Theranos announced in 2013 a different partnership to offer blood tests to the public through Walgreens drugstores. Safeway signed on as the exclusive supermarket provider of Theranos tests, and Safeway built clinics in roughly half of its stores at the time, one former executive said.

Walgreens Boots Alliance Inc. won’t open any new Theranos blood-testing centers beyond the current 41 until Theranos resolves questions about its technology raised by an article in The Wall Street Journal last month, according to a Walgreens official.

That article reported that the proprietary lab instrument developed by Theranos as the anchor of its growth strategy handled just a small fraction of the tests sold to consumers at the end of 2014, according to people familiar with the matter. The article also said some of the startup’s former employees were leery about the machine’s accuracy.

The valuation of Theranos, started by Elizabeth Holmes in 2003 when she was 19 and dropped out of Stanford University, jumped to $9 billion last year.

“T-Rex” was rooted in Mr. Burd’s enthusiasm for health-care innovation, according to the former Safeway executives. They said he managed the partnership directly with Ms. Holmes. Mr. Burd declined to comment, citing a nondisclosure agreement. He retired in May 2013.

The plan called for Safeway to build upscale clinics that would house Theranos’s blood analyzers and provide patients with rapid test results, according to current and former Safeway executives.

The $350 million price tag was equivalent to more than half of Safeway’s net income of $596.5 million in 2012. Safeway had revenue of $44.21 billion. Safeway also invested more than $10 million in Theranos, one former Safeway executive said.

Theranos often drew the same employee’s blood twice, first with blood from a finger prick and then the traditional method of a needle in the arm, according to one former Safeway executive.

The former executive said he worried that Theranos’s finger-prick process was still a work in progress. “If the technology is fully developed, why would you need to do a venipuncture?” this person said, using the term for a traditional blood draw.

One Safeway executive got a frighteningly high result from Theranos on a test to gauge his prostate-specific antigen, according to two former Safeway executives. They said the test suggested that the executive had prostate cancer. Retesting by another lab came back normal.

Theranos also backed away from putting its blood analyzers in Safeway’s clinics so patients could get the results quickly, the current and former executives said.

Instead, Theranos said blood samples collected at Safeway would have to be shipped to a central lab for analysis, according to the former executives.

By early 2013, some stores in California had hired phlebotomists, or the technicians who specialize in drawing blood, according to the current and former Safeway executives.

But Theranos kept delaying the rollout of its blood-testing services, those people said.

Mr. Burd retired the next month. After that, Theranos’s Ms. Holmes stopped interacting with Safeway executives and delegated the handling of the relationship to Theranos’s president and chief operating officer, Sunny Balwani, according to the former Safeway executives.

T-rex? Are these people out of their fucking minds? One must wonder if these fat hogged male executives were simply smitten by the young Miss Holmes, a woman with no medical credentials, claiming to have revolutionaized the process of testing blood.

Actually, the person who claimed to revolutionize it, who worked for her, committed suicide a few years back. But I guess that’s not really relevant information.

Good luck to the VCs who got into Theranos in the last round!

Comments »

Cramer Buys 100k $TST; Is TheStreet a Buy?

I know most of you will dismiss the fact that Jim bought some TST stock, thinking he’s emotionally attached to it. Truth is, this is a bold statement by Jim, buying the stock of his horrendously mismanaged website.

Being intimately familiar with the business of operating a website and subscription services, I can tell you TST is nothing short of a goldmine.

Revenues aren’t growing at TST, according to recent reports. Subscription revenues, which make up 80% of revenues, have been flat. Media revenues, which is basically ads, were flat as well.

Nevertheless, Jim is buying the stock. Why?

image

As you can see by the income statement, there is nothing awe inspiring here. It’s your run of the mill, boring grind lower to an eventual watery grave.

Why the fuck is SG&A so high? This company has shitty margins and that should/could be fixed.

image

Revenues appear to be higher; but they’re not. It’s due to an acquisition of a company called MDL. What does MDL do? Who gives a shit? They aren’t growing. Why is TST buying companies that aren’t growing? This is absurd.

image

Why is TheStreet.com a goldmine? Traffic. It’s a top 1,000 site in the country, valued at just $54 million. Shit, Wall Street values TST at a little more than 1x sales and BusinessInsider just sold for 9x sales. If I were in charge over there, I’d fucking cull the dead weight. Just because someone is getting traffic and drawing in revenues, that’s not good enough to keep him/her. If revenues aren’t growing, and the talent isn’t hustling on social media to draw in subs, they should be fired. Cramer should use his celebrity status to draw in real talent, younger talent, who can bring excitement to TheStreet again.

Hate it or love it, TheStreet.com is an icon in financial journalism and it’s shameful that its share price is under 2 bucks, after 6 years in a bull market.

As stated by their income statement, ad revenue isn’t the problem here, it’s subscription services. My guess: TST has thwarted any and all opportunities to properly manage their social media channels, draw in new eyeballs, and redeuce turnover, thanks to the low quality of their talent.
image

Although much of their traffic is superfluous, I’d kill for an Alexa ranking like this.
image

Look at the website design for TheStreet.com. If you had a store and 80% of your sales derived from the sale of tires, would you flood your store with wrenches and hide the tires? That might not be the best analogy in the world; but what TST is doing by flooding their front page with a bunch of shit, is catering to ad revenues and trying to maximize page views, while minimizing the importance of subscription revenues.

More than that, the page is too cluttered, confusing, and it has no energy. I know they have a very good biotech guy over there, who kills it. But, aside from him, they have a bunch of ham and eggers on there, like Doug Kass and Helen Meisler.

No offense intended to any of them. But the methods and model TST has followed, almost with a religious lunatic fervor, isn’t working. Why not try something new?
image

TST has over 200,000 followers on Twitter, which is great. But there’s hardly any engagement, if at all, on Twitter. With all of those followers, you mean to tell me you couldn’t get 1 person to RT or fav an article? Either those followers are bought, or their content is 100% shit. People do not care.
image

Lastly, I want to bring up StockTwits and how TST is failing miserably there. Howard Lindzon built a great commnunity there, one that has lots of growth, energy and is a significant source of referral traffic for iBankCoin.

Cramer hasn’t posted anything on StockTwits since 2012. And, to boot, I have more followers than him there, which is ridiculous, considering his foot print.

image

How do I have twice is followers?

image

And look at this shit. TST floods StockTwits with links and don’t even bother to have them titled. If you saw these links, would you click on them? With the amount of overhead at TheStreet.com, you’d think they’d dedicate a few responsible people to manage their social media platforms.
image

The root problems at TST runs very, very deep. They’re dependent upon aging gurus to keep the company afloat. Any idea how many Exodus subscriptions I could sell if afforded the footprint and traffic of TST?

A fuckload.

Comments »

JP Morgan Hack Attack News Results in Sharply Lower Cyber Security Stocks

Make no mistake, the sheen is off the cyber-security sector, as the shares of PANW, CYBR, FEYE, FTNT, SPLK and CUDA swoon to new recent lows. Over the past 3 months, the median return for Exodus‘ internet security sector is -14%.

Today, indictments were doled out for a group of nefarious individuals who profited, mightily, off hacking the JP Morgan banking system.

U.S. prosecutors on Tuesday unveiled criminal charges against three men accused of running a sprawling computer hacking and fraud scheme that included a huge attack against JPMorgan Chase & Co and generated hundreds of millions of dollars of illegal profit.

Gery Shalon, Joshua Samuel Aaron and Ziv Orenstein, all from Israel, were charged in a 23-count indictment with alleged crimes targeting 12 companies, including nine financial services companies and media outlets including The Wall Street Journal.

Prosecutors said the enterprise dated from 2007, and caused the exposure of personal information belonging to more than 100 million people.

“By any measure, the data breaches at these firms were breathtaking in scope and in size,” and signal a “brave new world of hacking for profit,” U.S. Attorney Preet Bharara said at a press conference in Manhattan.

The alleged enterprise included pumping up stock prices, online casinos, payment processing for criminals, an illegal bitcoin exchange, and the laundering of money through at least 75 shell companies and accounts around the world.

If this news was released 6 months ago, shares of internet security stocks would’ve been off to the races. It’s somewhat disheartening to see these stocks mired in the mud of bearshit, since their growth prospects and investor appeal are second to none in the tech space.

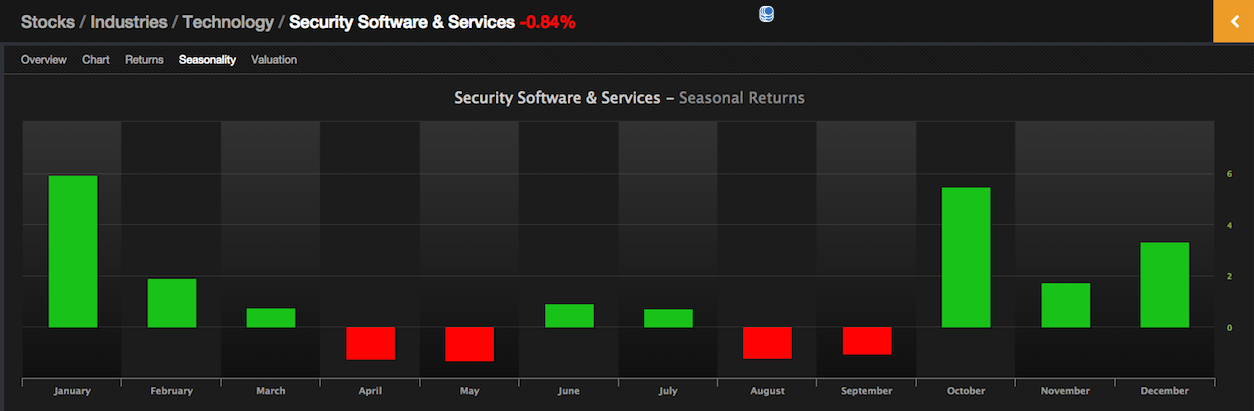
According to seasonality stats, internet security stocks perform best in the months from October-January.

security

I have a long term position in PANW, with a cost basis in the $80’s. It’s a wonderful company, growing revenues at 50% per annum. However, they’re unprofitable and one earnings slip up can cause the shares to drop, precipitously, effectively abandoning all hope for this sector.

Bulls will point towards an actual earnings per share, positive free cash flow as signs of a healthy company. However, if you look at the balance sheet, the company grossed a touch over $200 million in profits last quarter, but spent $191 mill in G&A. Another $50 million was spent on R&D, leaving the company with a $45 million net income loss.

This is fucking bullshit, essentially. The company is managed like a fucking iced cream truck and isn’t focused on the bottom line. This is the primary problem with these high beta software names today: they’re solely fixated on growth and market share, all the while investors get burned at the cross long their shares. Hopefully, some of these “hot shot” CEOs will be fired soon and operators will replace them, producing net income for long abused shareholders.

PANW is scheduled to report earnings on 11/23, looking for “a profit of 32 cents per share.”

Comments »

This Market Has Sponge Bob Muscles

Earlier today, Exodus flagged oversold, which coincided with a sharp bounce in the broader indices. Even still, this market is 100% horseshit, as our algorithms have decreased in value for 5 consecutive days.

Bear in mind, there are some amongst us who trade tapes like this better than others. As it so happens, you are fortunate enough to have one employed on this site. The Option Addict has been firing on all cylinders and is now taking reservations for his 5 day mini boot camp. I strongly advise you to take him up on this gracious offer and give us your monies.

My largest position is COST. Its been my largest holding, by a factor of 2, for several weeks now. Normally, I do not weight into mega caps like this. I do not run billions of dollars and I tend to gravitate towards high beta. Nevertheless, it’s important to know when you’ve been dispatched and abused by an evil tape. I shot out from a carnivale cannon with long dicked (extra Tyrone) gains earlier this year and have flailed in the wind since then. During this recent respite in stocks over the past month, I made a conscious effort to protect my 20% gains and avoid another meltdown.

Some of my favorite holdings, albeit smaller, are behaving in your typical, ruinous, fashion. Shares of PAH, SHAK, JAZZ and FCX are giving me nothing but fits now, which sort of elates me in an odd way, happy that I was prescient enough to see my own short comings and position into larger cap stocks, like COST and CNC, to offset this fuckery.

Wade through this muck, gents. The market isn’t nearly as strong as it looks, or as easy as The Option Addict makes it look. We’ll most likely mark time from now until year end, ebbing and flowing with extraordinary levels of fuckery. I expect the market to be annihilated during the first two weeks of January.

Comments »

Fidelity Writes Down Snapchat Stake by 25%

I don’t understand why they’d do such a thing. I mean, isn’t Snapchat the coolest thing to hit idiot teenagers since acne cream?

Wut, the co izn’t worth $20 billion ne moar bcuz they don’t make ne revenews?

Fidelity, a fund manager which invested in the creator of the mobile app for sending disappearing photos and videos, marked down its stake in Snapchat by 25 percent to $34.5 million in the third quarter, according to data from Morningstar on Tuesday. Snapchat had raised cash from investors at a $16 billi o n valuation earlier this year, a person familiar with the matter said in May. The Financial Times earlier reported the writedown.

Fidelity is reassessing its stake in Snapchat amid increasing anxiety in Silicon Valley that some privately funded companies may not live up to their lofty valuations. Other startups, including Dropbox Inc., have had their values adjusted downward by mutual funds in recent months. Last week, Square Inc. said it was seeking a market capitalization for its initial public offering that was significantly lower than its private-company valuation.

The era of the unicorn is over. Fuck the millennials and to hell with privately held crap, overhyped by Frederick Wilson. Very soon, programmers will be in the streets with tinned cups, begging for stock options.

Comments »

$MNK Rallies After Citron’s CNBC Interview

Let’s kill all price gougers. That’s pretty much the short thesis for gunning after these drug companies. Aside from medicine, humans need clothes to survive too, no?

How about we build a short thesis on JWN; because Nordstrom is fucking price gouging like a motherfucker. Do you know who else is price gouging?

EVERY FUCKING COMPANY ON THE FACE OF THE PLANET.

I believe MSFT has gross margins of 97%. That’s pretty rich.

Ever been to a TIF or a DKS? Some of those prices, I gotta say, are fucking high.

Let’s not even get into the restaurants. As a member of your planet and person who needs sustenance to survive, I take exception, mind you, to the prices of burritos at CMG and hamburgers at SHAK and motherfucking coffee at SBUX.

God damn it; why can’t everything be on the MCD dollar menu?

My son is in college now. And, I must admit, I am growing somewhat suspicious of the prices of his books. I find myself spending upwards of $1k per semester for text books and I find myself awfully suspcious of PRICE GOUGING at his college.

I’ll be keeping an eye on them.

Do any of you own NYC or San Fran real estate?

(flails cane wildly in the air, screaming “price gougers”)

This is wholly and utterly ridiculous.

MNK’s shares have spiked around 8 points since this interview.

NOTE: Left said his short in VRX is “significantly scaled down” and had several positive things to say about its CEO. Does anyone else find it odd that Citron has backed off VRX so quickly, especially after Ackman became very vocal about it?

Comments »

China’s Single’s Day Sales Surpass Cyber Monday’s Sales in 30 Minutes

Last year, the United Steaks consumed at a rapid pace, preferring the online venue on Cyber Monday ($2.2 bill in sales) to shop to their gluttonous heart’s delight. However, all of our shopping was eclipsed by China’s imaginary holiday event called “single’s day”, a day hijacked and promoted as a holiday by the CEO of BABA, Jack Ma, within 30 fucking minutes.

image

Last year, Alibaba hosted $9.3bn worth of transactions on its online stores, after consumers spent $2bn in the first hour alone.
This year, Singles Day is expected to smash through those records.
IDC, the market research firm, predicts that Alibaba’s sales during this day could reach 87bn yuan, or $13.7bn.

Jack Ma is an evil genius villain. He hijacked this little known college originated holiday, spawned from demographic fuckery, which is the net result from decades of idiotic one child policy in China.

Via Wikipedia

Singles’ Day or Bachelors’ Day was initially celebrated at various universities in Nanjing during the 1990s, and originated from Nanjing University in 1993.[citation needed] It got the name “Singles’ Day” because the date consists of four “one”s. These college students have since graduated, and carried the university tradition into society. Singles’ Day has been largely popularized in the internet era and is now observed by youth in several regions outside China as well.

Why is BABA lower today? I believe people are still fainting over last year’s big fade, which saw BABA top out and burn out after single’s day; because, well, it’s all downhill from here.

image

The scale of this event is awe-inspiring. It paints a vivid picture of how powerful a true Chinese middle class could be for retail. It’s the reason we still tolerate Chinese stocks, despite the fact that most of them have proven to be outright scams.

UPDATE: BABA has surpassed $5 billion in sales within 90 minutes, more than double our Cyber Monday.

image

Comments »