iBankCoin

The Fed Cried Wolf and Lost; Yen Rips Higher On Fed Inaction

This is utterly and fantastically ridiculous. The Fed and their overpaid talking heads have been menacing the markets for months, threatening the world with the specter of a rate hike. Everyone knew that they were full of shit. But because they were so consistent with their menace, people started to believe maybe they were serious, them and their dot plot. Lo and behold, one little bad jobs number and the Fed surrendered everything they believed in.

The Fed Dot plot that was released last year, a plot and a scheme of sheer stupidity, is now at 3%–down from the original target of 4.25%.

The result of all of these eggs being smeared on their faces is the yen gaining by 0.55%% vs the dollar. The euro higher by 0.7% v the dollar. Gold is up 0.4% and bond yields are dropping and crude is down 0.5%

Equities are churning and have gone nowhere.

Bottom line: All eyes should be on the Yen. The Fed has become singularly irrelevant and are a joke, unlike the Bearded Fed of Dr. Benjamin Bernanke. On a more serious matter, watch those negative interest rates dive deeper.

ALL EYES ON THE YEN.

Comments »

FED DOES NOTHING WITH RATES, STRIKES A MORE DOVISH TONE

Shocker: the Fed is on hold. Moreover, they only expect two interest rate hikes for 2016, instead of 3. It’s worth noting, two rate hikes is two hikes too many.

Markets are slightly higher following the inaction.

The Yen is climbing against the dollar again, much to the chagrin of the BOJ, higher by 0.4%.

The euro is higher by 0.6% v the dollar.

Gold is higher by 0.45%

Crude is down 0.3%.

TLT is up 0.7%

Comments »

Deutsche Bank Likens a Negative Bund Yield to The Red Wedding From Game of Thrones

Deutsche Bank analyst Jim Reid is still flabbergasted, astonished even, over the German Bund going negative for the first time ever. To prove his fixation, he produced his chart of bund yields dating back to the ‘who gives a shit days’ of 1807.

bund

He blames a financial system that is indelibly broken and without wheels for this occurrence. Moreover, STAGNATION will likely preside over much of the western world until the fucking lunatics inside of these central banks stop propping up bonds with their playdoh money.

“Although there has been a creeping inevitability on this for several days now, this landmark remains a truly remarkable event. If one wanted a simple indicator to reflect a broken financial system then this would be a strong candidate,” wrote Deutsche Bank’s Jim Reid, in his Wednesday morning missive.

Reid puts the benchmark bund yield’s break below zero in the same league as “the moon landing, JFK’s assassination, John Lennon’s shooting, maybe even the Red Wedding episode from Game of Thrones.”

“It’s incredible when you think that the central bank responsible for the inflation rate in Germany has a target of (just below) 2% per year,” Reid wrote, reflecting on the chart. “Let us stress that until governments/central banks change policy, yields are likely stay at ultra-low levels due to secular stagnation-type themes and the overwhelming amount of QE hoovering up bonds. However it still reflects a broken financial system.”

On a side note, how dare he evoke The Red Wedding while John Snow’s fate to recapture the north lies in the balance.

Shameful.

Comments »

Retail Stocks Rip Higher on Bullish Commentary

An analyst from Cleveland Research had some positive things to say about Kohls and retail in general today.

Warmer weather helped same-store sales improve by a “decent amount” in late May and early June, analyst Matthew Delly said Wednesday in a note. While Cleveland Research is cautious on Kohl’s for the long term, the brightening trends could help Kohl’s meet analysts’ consensus projections for the current quarter.

Moreover, there’s a retail conference taking place today at Piper Jaffrey. The notes out of JC Penney were very bullish.

Via Briefing.com

11:20 | JCP | (8.63 +0.61)
J. C. Penney at Piper Jaffray Conf.
Memorial Day weekend was positive; feel good about position.
Discretionary spending is being hampered by uncertain macro.
Appliances:

JCP will not own appliance inventory, just what’s on display.
Appliance floor space took over worst performing segments… Appliances are significantly more profitable

Major competitor is donating share in appliances — likely a reference to Sears (SHLD) as HD, LOW and BBY are all doing well in the space.

Now that JCP is gonna sells washer and dryer combos to seniors, all is well.

JWN had something to say about recent trends too.

Multiple factors driving softness in retail, which started ~mid-Aug 2015: Shift in consumer spending towards housing and away from apparel, somewhat cyclical. No new fashion trend. E-commerce also taking share.

Online offerings are doing well (now 20% mix).
Now learning about how to be more profitable in e-commence
Growing off price/online.

Committed to investing in technology, the ‘new mall’.
Co cut inventory plans.

Competitor’s marketing has become transnational, JWN not interested in that.

Close to one million phone numbers in new loyalty program in less than one month.

Flagship Michigan Ave (Chicago) store as robust as ever (co installed a bar on the second floor).
Trunk Club is doing well.

Nordstrom Rack/Haute Look is a great clearance channel. Targeting 270 Rack locations (down from 300) by 2020 due to expansion in online. Rack model is flexible and attractive, attracts people to JWN brand.

Testing economic partnership with Tesla (TSLA) in one store, with a Model X on display (attempt to drive traffic).
Excited about oppties ahead.

Couple that with the fact the sector had been extremely oversold and you’ve got a rally on your hands.

I noted yesterday in Exodus that the overbought/oversold oscillator was very oversold.

image

image

The mall is still dead, though.

Comments »

Scourge of the Earth Gets 2 Years in Prison For Facebook Spam

If it was up to me, I’d execute this person via dick guillotine. However, it’s worth noting, I would not be doing the ‘handling’, so to say.

This fucker accessed 500,000 accounts and sent 27 million spam messages. The fuck.

Federal prosecutors say a Las Vegas man has been sentenced to 2 ½ years in prison for sending more than 27 million spam messages to Facebook users and disobeying a court order not to access Facebook.

Federal prosecutors say Tuesday a federal judge in San Jose, California on Monday also ordered 47-year-old Sanford Wallace to pay $310,000 in restitution.

Last year Wallace admitted to accessing about 500,000 Facebook accounts and sending unsolicited ads disguised as friend posts over a three-month span.

I hope he gets spammed 27 million times in prison.

Comments »

Michael Milken’s Family Office is Now a Hedge Fund and is Accepting New Money

The former prison inmate, Michael Milken, is going to open his family office of $2 billion of personal and family funds to the public, so it can become a hedge fund.

How wonderful.

Silver Rock Chief Investment Officer Carl Meyer, a former Citigroup Inc. executive, will control the new firm and have a staff of about 10 executives, the newspaper said. Until recently, the family office was based in the same building as Mr. Milken’s office in Santa Monica, California, but the executives leased new space in Los Angeles when they formed an independent entity on March 25, according to the Journal.

The executives had been managing more than $2 billion for Milken and his family in junk bonds and distressed loans, along with stocks, the Journal said. The firm has run into challenges recently because of poorly timed energy investments and Milken’s insistence to hold a large cash allocation, according to the newspaper.

Don’t worry, Milken will not be managing the fund or have anything to do with it, according to Carl Meyer. Oh, and that last sentence that says the family office fund has sucked balls due to shitty energy investments and Michael’s insistence that the fund hold a large cash position should be ignored by all those interested in sending money to this new venture.

Comments »

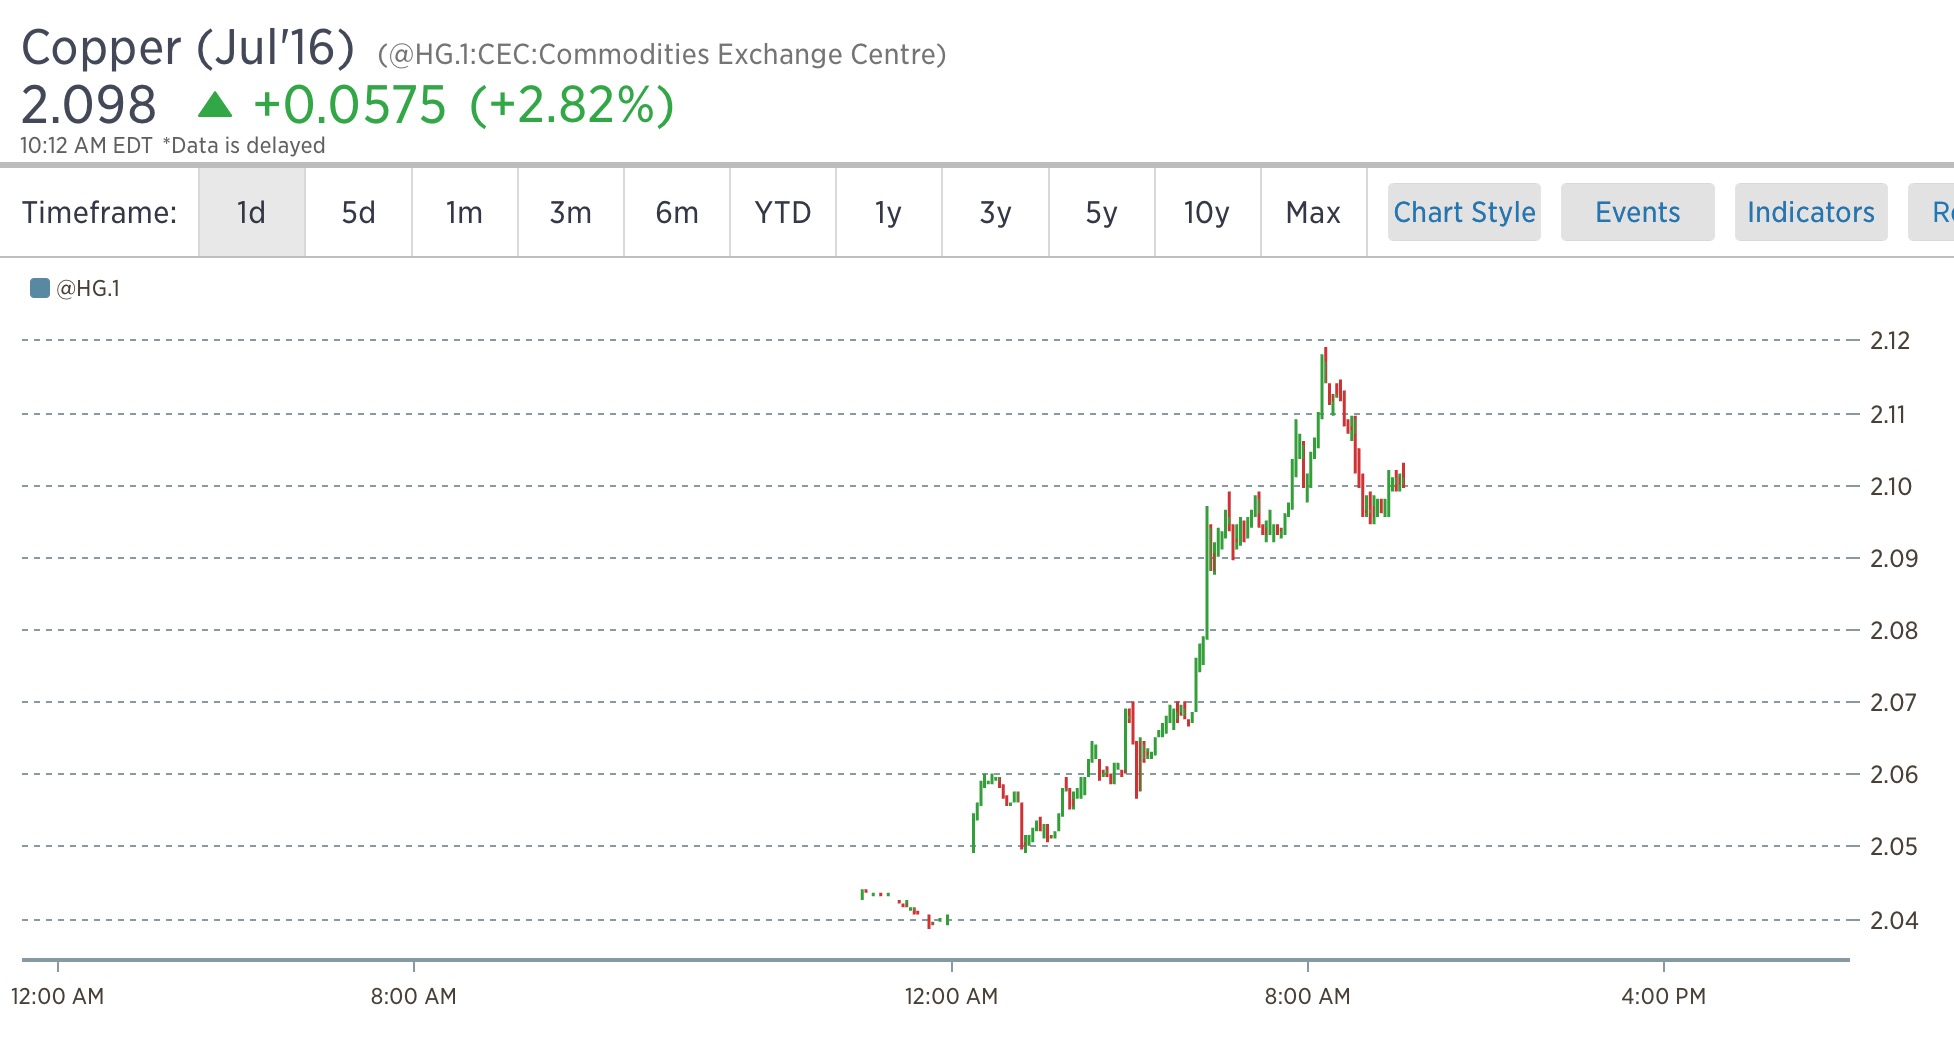
Copper Spikes After Shanghai Advance

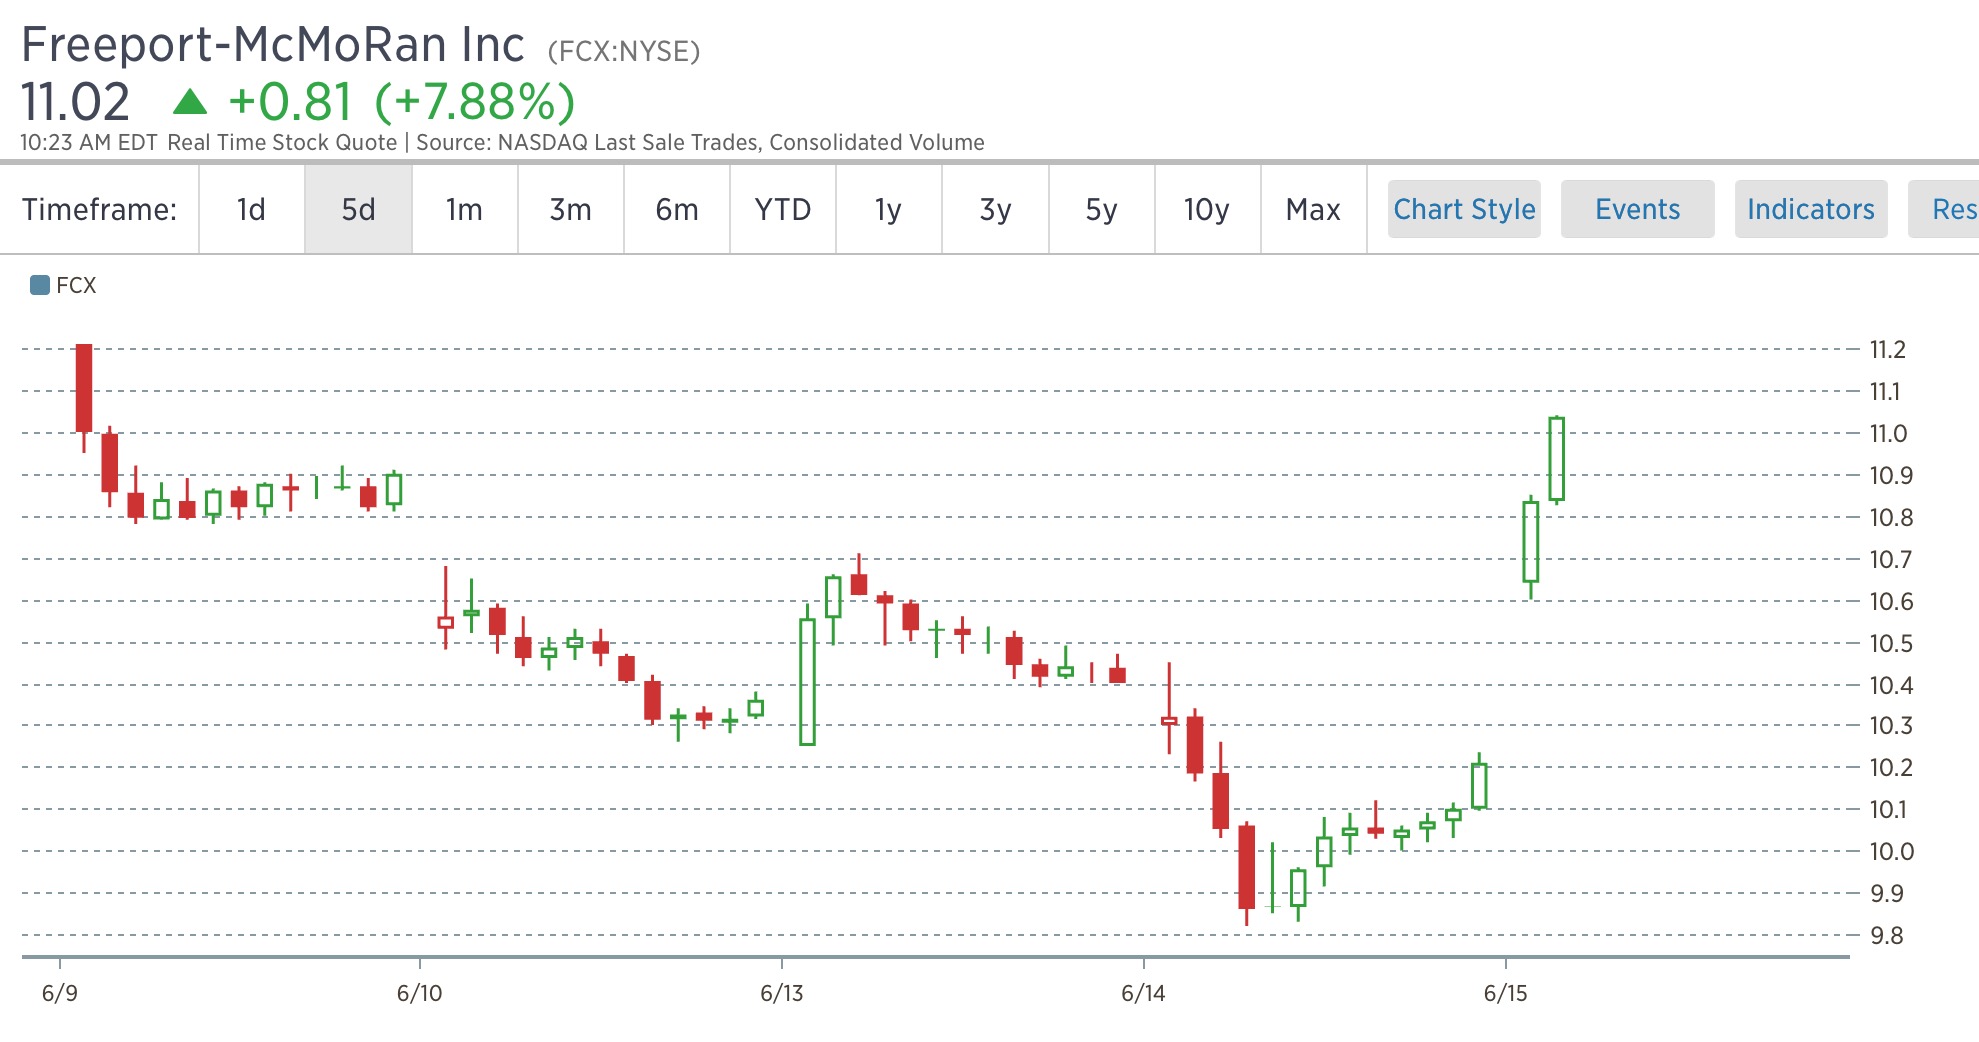
The ultimate leveraged bet on China is copper. The most prolific copper company with lots of upside leverage is FCX. Ergo and henceforth, the best way to play a resurgence in China is through FCX.

Last night the Shanghai traded higher, in a very government controlled sort of way–after being rejected by the MSCI for inclusion into its benchmark.

Today, the price of copper is whipsawing higher, which in turn is forcibly crushing the skulls of all those short FCX.

image

image

I can’t endorse a long term position in FCX, especially with the outlook for China so grim. However, for a trade, it might run for a few days, maybe more. This whole BREXIT scare mongering has ‘trap’ written all over it for shorts. Do not think for a second that central banks aren’t plotting and scheming, scheming and plotting, to cause another frenzied move to the upside.

Comments »

How Unreasonable is a $TWTR Takeover?

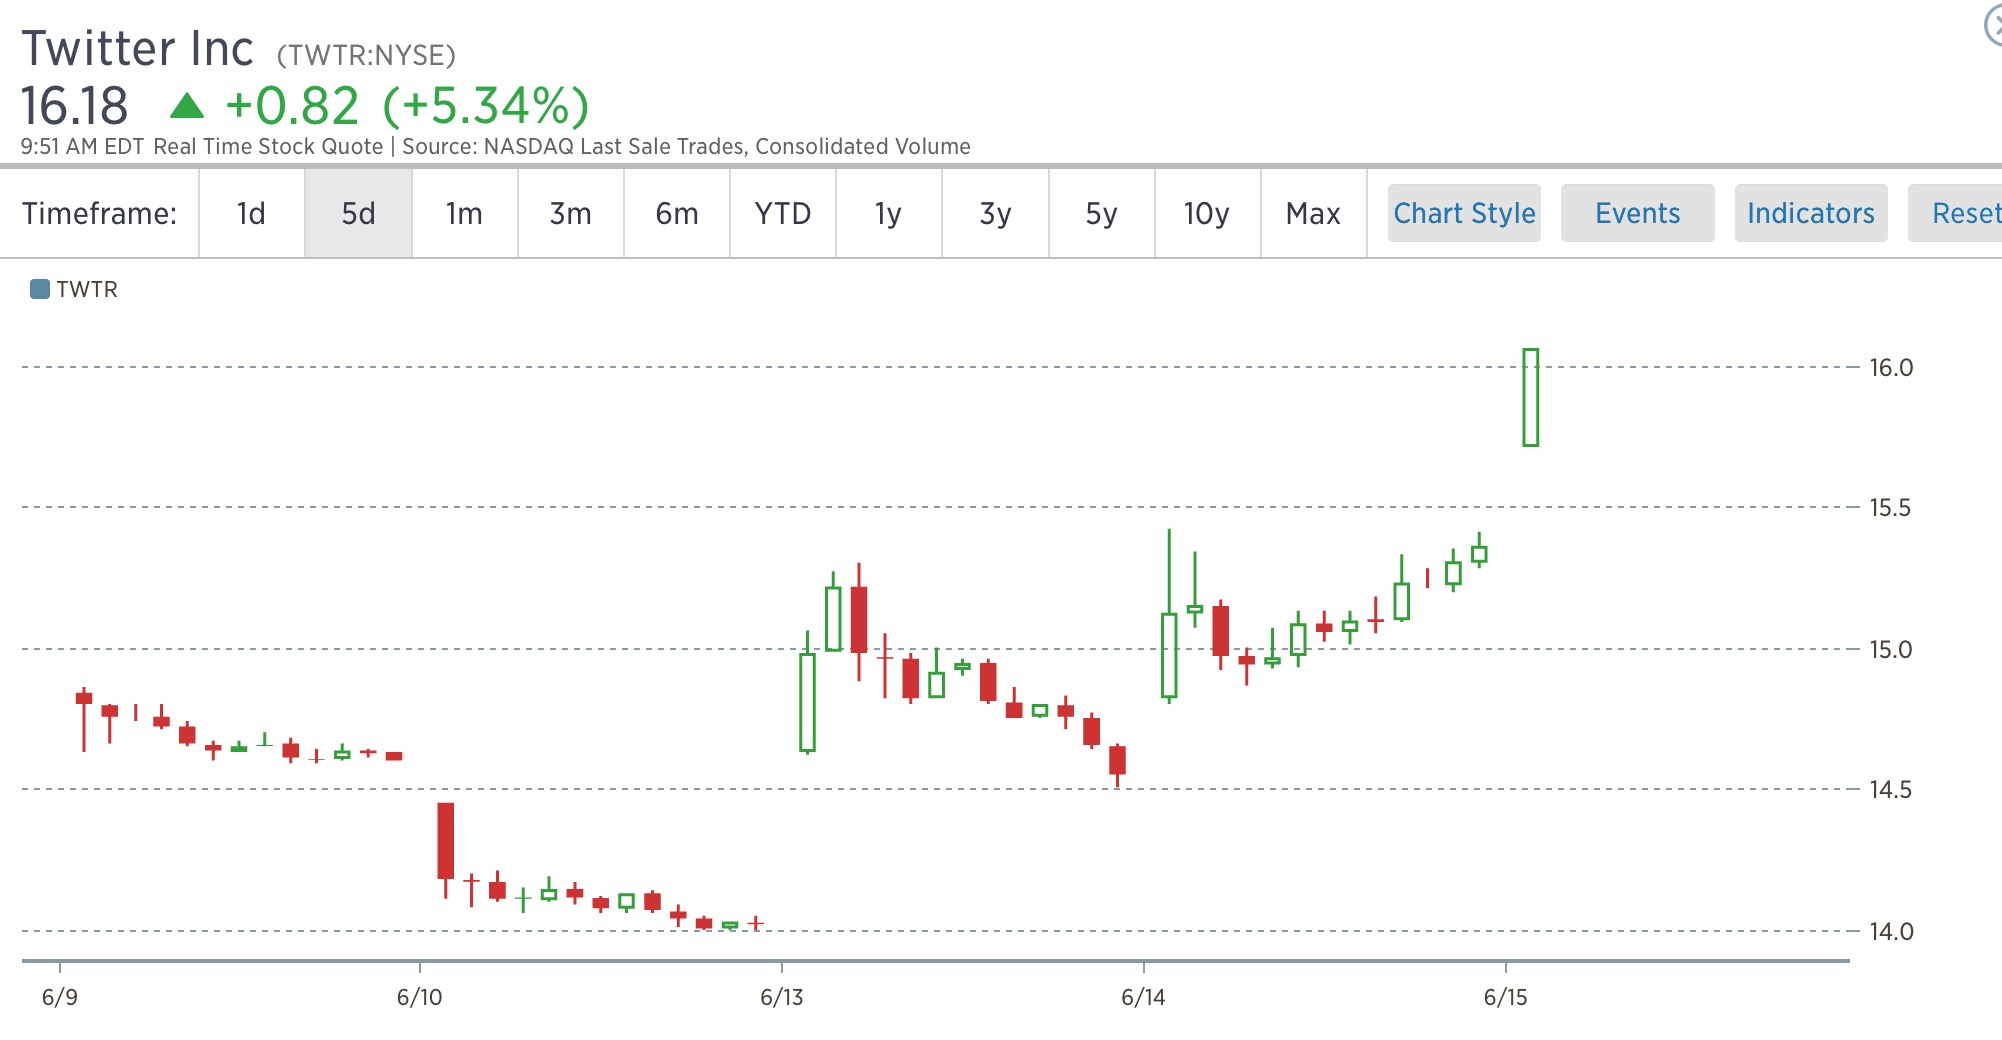
Shares of TWTR are higher again this morning. The takeover rumors have been circulating ever since the MSFT for LNKD deal was announced. Most people that I know scoff at Twitter when presented with the idea that someone might want to buy them. The general reaction is ‘why would anyone want to buy a money loser like Twitter?’
image

I can answer that question with another one.

Why do really rich people want to buy newspaper companies?

Answer: for power, influence and prestige.

Love or hate Twitter, it is the news super highway, the ultimate real time denizen for anything noteworthy happening in the world. Whenever a crisis hits, I go to Twitter to find real time information. As a resource, it’s invaluable, truly.

The valuation?

It’s actually not too bad.

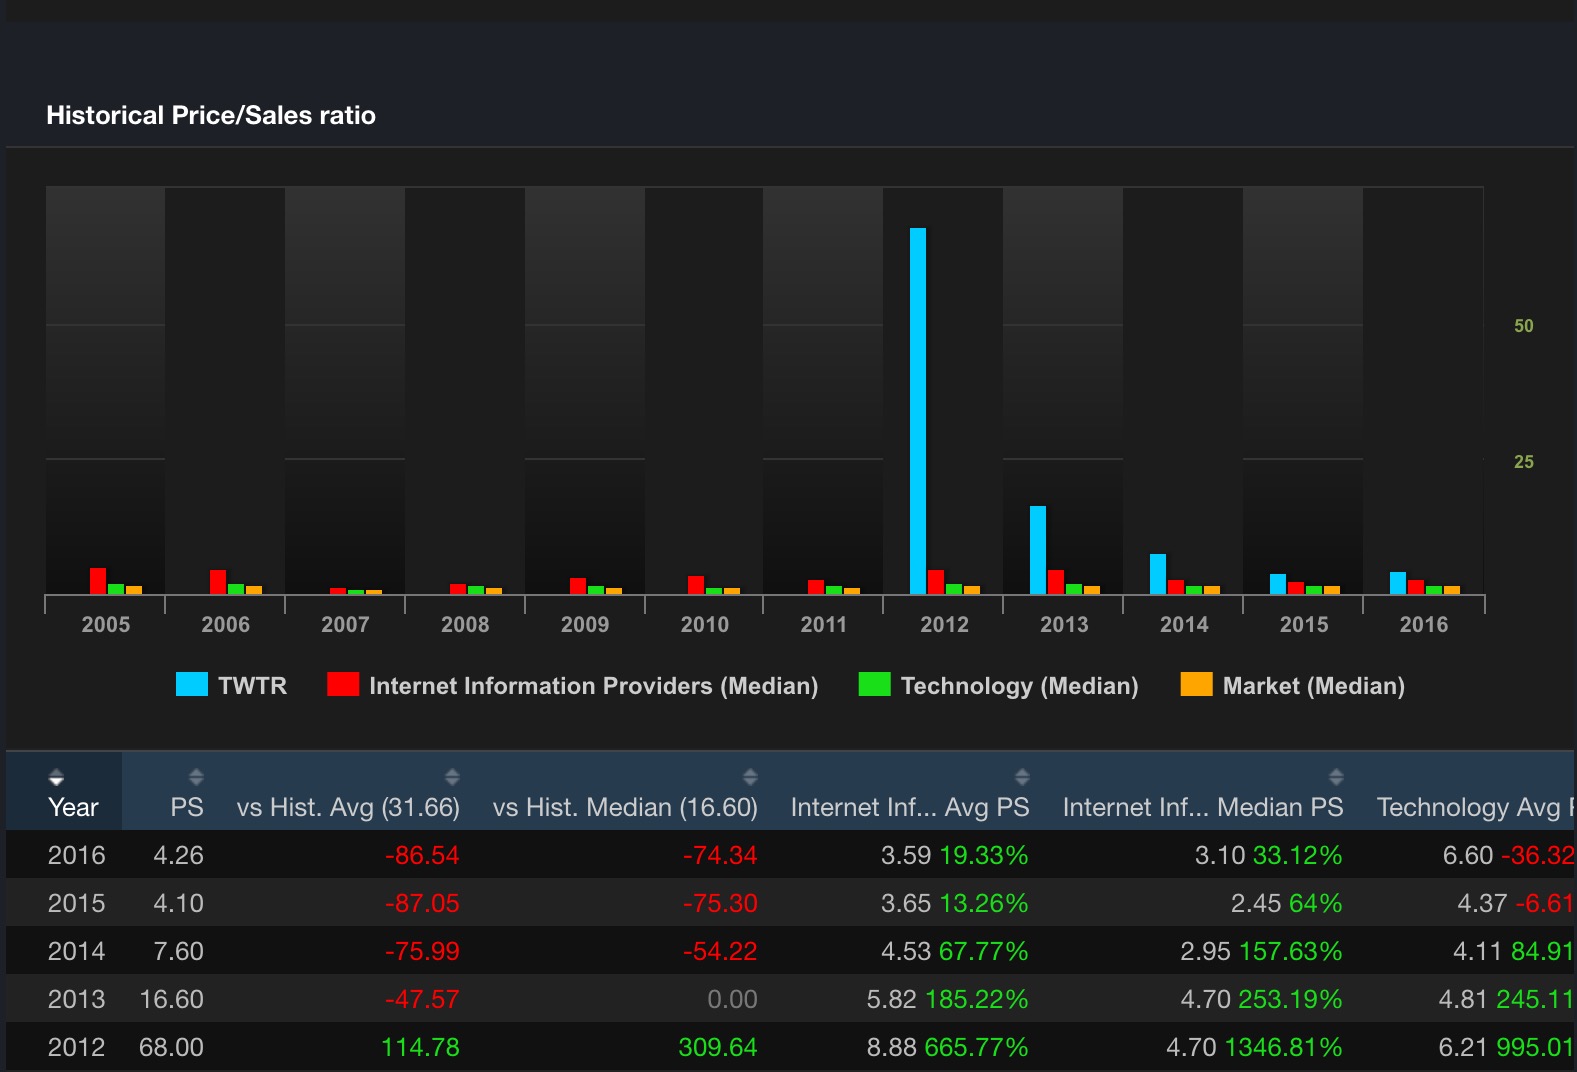
The stock is trading a touch over 4x sales. Typically, growth stocks of note trade upwards of 10x.

image

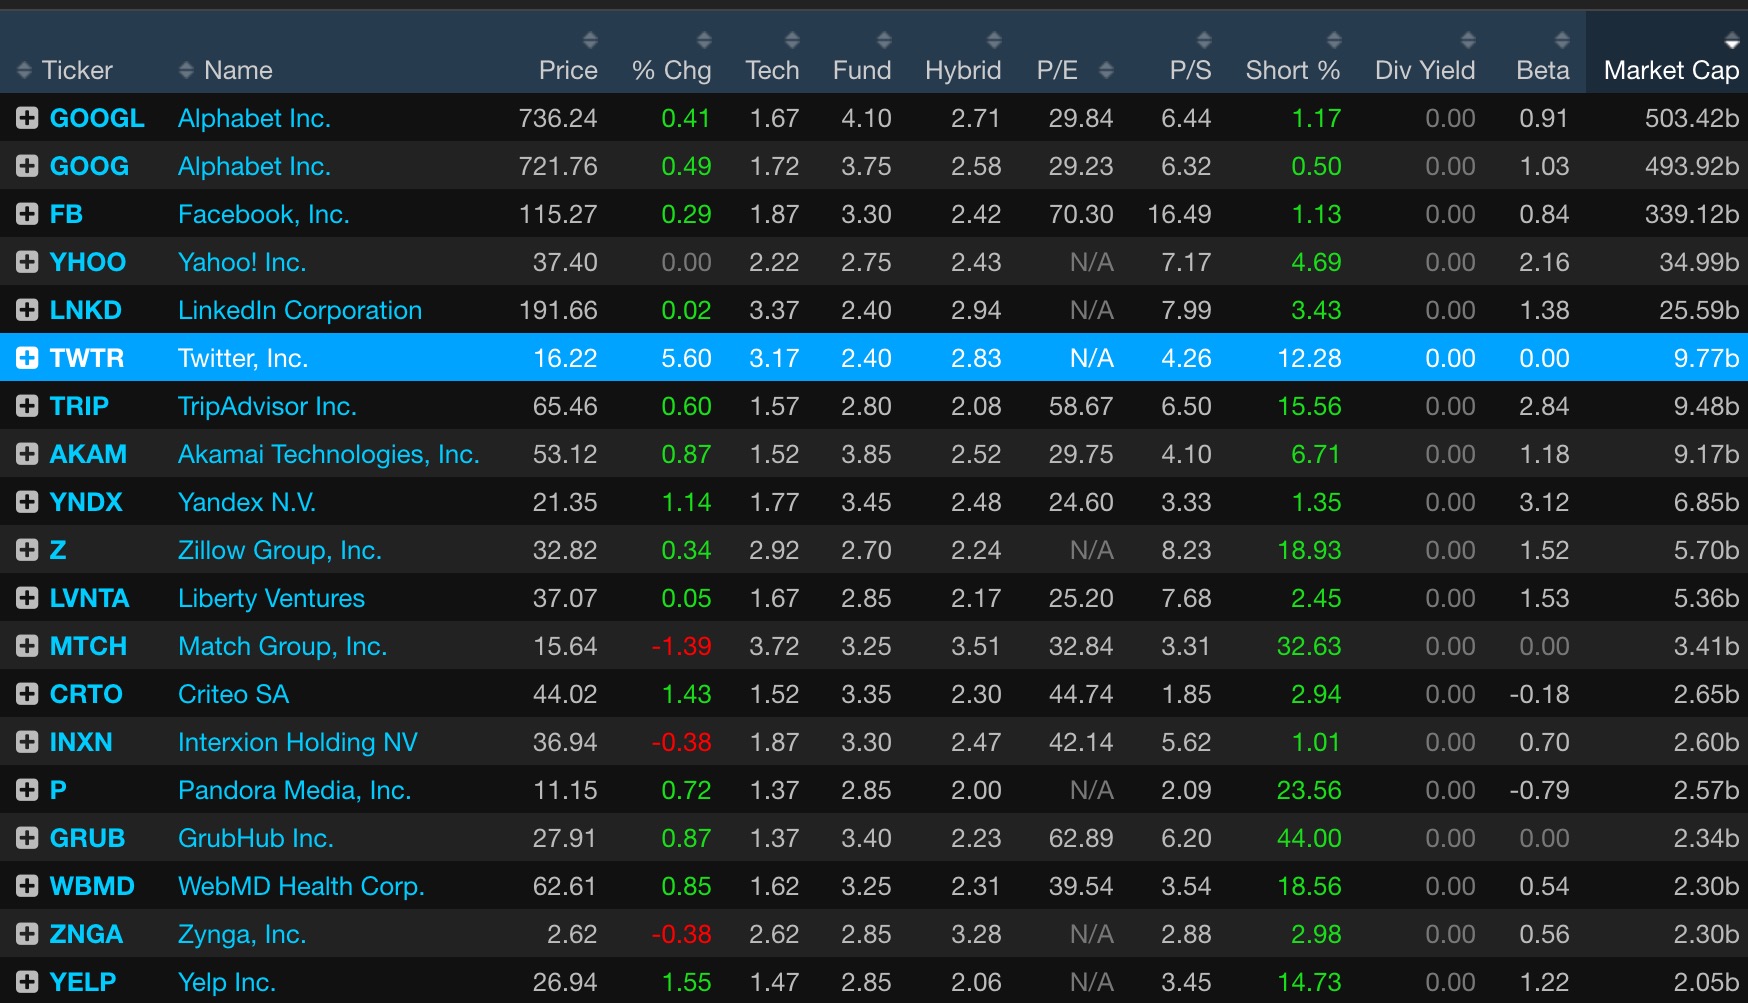
As you can see, relative to its peer group, the stock is cheap. Note how LNKD got bought out at around 8x sales. Data provided by the indomitable Exodus. Give it a try.

image

The only other stock in social media that is more attractive than TWTR now, in my opinion, is YELP. But I’m biased and have loved Yelp from day 1.

I don’t think anyone would be surprised to see TWTR catch a bid for around $30-35 per share, given its potential. Just because the morons who operate it now can’t figure out how to monetize it doesn’t mean someone else won’t figure it out.

Comments »

NYT Publishes Skeptical Missive on $NFLX

The article was like 100,000 words strong. I wanted to blow my brains out for even beginning to read the damned thing. In summary, the New York Times article doesn’t have the balls to outright say Netflix is a huge disaster waiting to happen, because the world of streaming teevee and movies is unpredictable. However, they did make note of NFLX’s absurd $1 billion negative cash flow and dependence on debt markets to keep the charade going.

Here’s a snippet.

One of the most prominent Netflix skeptics is Michael Pachter, a research analyst at Wedbush Securities, a Los Angeles-based investment bank. In his view, Netflix’s true advantage in the beginning was that it had the entire game to itself, and the networks, not realizing how valuable streaming rights would be, practically gave them away. He had a “buy” on the stock from 2007 to 2010, he told me. But, he added, referring to those years when Netflix had streaming all to itself, “If it’s too good to be true, then it will attract competition.”

Now, he said, the networks and studios are charging higher fees for their shows, forcing up Netflix’s costs. Netflix doesn’t own most of the shows that it buys or commissions, like “House of Cards,” so it has to pay more when it renews a popular show. In addition to the money it now spends on content, it also has more than $12 billion in future obligations for shows it has ordered. The only way it can pay for all of that is to continue adding subscribers and raise subscription rates. And even then, Pachter says, the networks will extract a piece of any extra revenue Netflix generates. “It is naïve to think that Netflix can raise its price by $2 a month and keep all the upside,” he said. “I defy you to look at any form of content where the distributor raises prices and the supplier doesn’t get more. That’s the dumbest thing I ever heard.

“Netflix,” Pachter concluded, “is caught in an arms race they invented.” He compared Netflix to a rat racing on a wheel, staying ahead only by going faster and faster and spending more and more: As its costs continue to go up, it needs to constantly generate more subscribers to stay ahead of others.

And if that doesn’t happen? If subscriber growth were to stall, for instance, then Wall Street would stop treating it as a growth stock, and its price would start falling. Slower growth would also increase the cost of taking on more debt to pay for its shows. The company would be forced to either raise subscription prices even higher or cut back on those content costs or do both, which could slow subscriber growth even further. Netflix’s virtuous circle — subscriber growth and content expenditures driving each other — would become a vicious circle instead.

Personally, I watch several Netflix shows. I watch House of Cards, Peaky Blinders, Marco Polo and I’ve watched Sherlock and Luther through it, though I believe they’re both BBC owned shows. I’m not paying attention to the balance sheet now, mainly because I haven’t really cared. But I do recall when NFLX got smoked several years ago, after they errantly hiked prices and the stock plunged. For a while there, it looked like the company was facing bankruptcy.

Hopefully they can keep growing and learn to balance their budget. Otherwise, they might Blockbuster themselves within the next decade.

Comments »