iBankCoin
Home / 2016 / July (page 5)

Monthly Archives: July 2016

Can Jack Save Twitter?

Some believe Jack Dorsey, CEO of Twitter, is the second coming of Marissa Mayer. Others believe he’s a tech and marketing genius, biding his time, waiting to strike the market with a white hot number that will send Twitter spiraling higher. Very recently, Jack’s good name was maligned for a sundry of free speech concerns. However, speech isn’t necessarily free, as the very apparatus by which this freedom is used is to serve money.

Let’s see if Jack can make some money for his shareholders.

Earnings pending.

Comments »

$ADI ACQUIRES $LLTC for $14.8 BILLION, OR $60 Per Share

The renaissance in the world of semiconductor stocks is clearly upon us. After years of struggle and being beguiled by profit margins and the idiosyncracies of Apple, investors have ceased to care and have bid up the sector to fantastic levels. Analog devices is taking advantage of suchness, and has decided to acquire a lowly competitor for the pedestrian sum of $14.8b.

The co’s announced that they have entered into a definitive agreement under which Analog Devices will acquire Linear Technology in a cash and stock transaction that values the combined enterprise at approximately $30 billion. Upon completion of the acquisition, Analog Devices will be the premier global analog technology company with approximately $5 billion in anticipated annual revenues.

  • Under the terms of the agreement, Linear Technology shareholders will receive $46.00 per share in cash and 0.2321 of a share of Analog Devices common stock for each share of Linear Technology common stock they hold at the closing of the transaction. The transaction values Linear Technology at approximately $60.00 per share, representing an equity value for Linear Technology of approximately $14.8 billion
  • The transaction is expected to be immediately accretive to Analog Devices’ non-GAAP EPS and free cash flow. Analog Devices expects to achieve $150 million of annualized run-rate cost synergies within 18 months post transaction close
  • Closing of the transaction is expected by the end of the first half of calendar year 2017

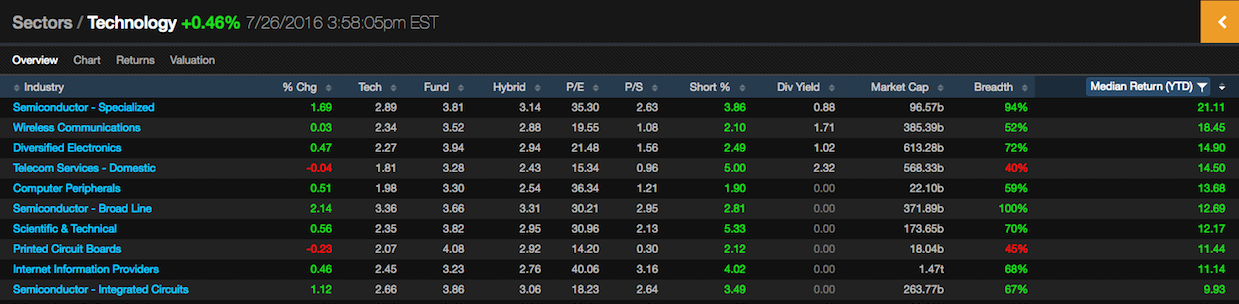
YTD, semis have been, by far, the best performing stocks in the tech sector.

Semis

Comments »

CNBC Host Attacks Peter Schiff for His Bonds

Only in the world of finance is this remotely interesting. They were having a heated debate about the Fed and how Peter Schiff believed there was no way in red hell they’d hike rates again, until Scott Nation stepped in with soviet era styled propaganda, maligning one of Peter Schiff’s bondless bond funds.

S. Nation discussed how fucked up Schiff’s dystopian world view was, as we suck the tarmac off all time, record, highs, and they were having a very cordial back and forth, with Schiff repeating his end of days jargon etc. Then Mr. Nation upped the rhetoric and totally shit on his underperforming bond fund.

You best diversify your bonds, Peter.

Comments »

Stifel Downgrades 11 Restaurant Stocks, Says Recession is Coming Soon

Paul Westra from Stifel didn’t just downgrade a bunch of eateries today. He’s predicting an absolute, terrifying, doom in the US economy. He cites restaurant stocks as the singular bellwether for the retail consumer. With comps heading lower, it can mean just 1 thing: recession.

image

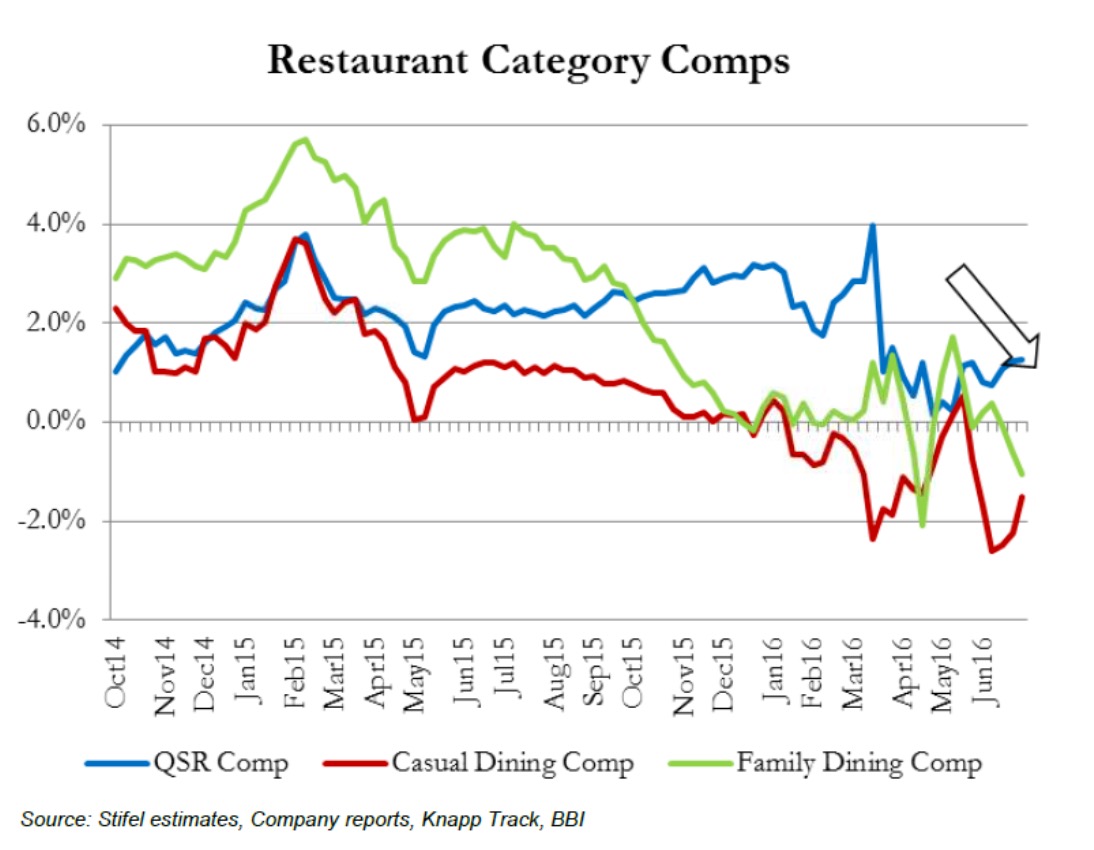
“Today, we adopt a bearish outlook for restaurants as we confidently believe that, at a minimum, the simultaneous -150 basis points to -200bps deceleration of restaurant industry comps across all categories during the second quarter within our most recent Stifel Sales Survey reflects the start of a U.S. Restaurant Recession,” Westra and his team said in a note.

This doesn’t just bode ill for restaurants, but could point to trouble across the economy as a whole. A downturn in dining could be implying a U.S. recession as soon as early 2017, he said, since “restaurants have historically led the market lower during the three to six-month periods prior to the start of the prior three U.S. recessions,” Westra adds.

Since he isn’t singling out one particular area of the industry, he is downgrading shares of 11 different companies including Chipotle Mexican Grill Inc., Darden Restaurants Inc., The Cheesecake Factory Inc. and Zoe’s Kitchen Inc. According to his research, industry peers are slowing down across all sub-industries. Here’s a chart with quick-service restaurants (QSR), casual dining and family dining.

A few things are at play here. Maybe it’s all the civil unrest, fear of a neighborly head chopping terrorist attack or something worse. Personally, I believe Americans have transcended food and can sustain themselves off the blood of their enemies alone. All of these predictions of doom only feed into this clamoring for more blood, as markets, tirelessly, climb higher. Very soon, the good folks over at CMG will launch a catapult attack on the Stifel HQ, infecting them with a barbarous strain of ecoli, shutting their pie holes for good.

Comments »

Shares of $MBLY Clown Slapped After Losing $TSLA as a Client

This has been rumored for some time now. Naturally, Andrew Left from Citron was right again.

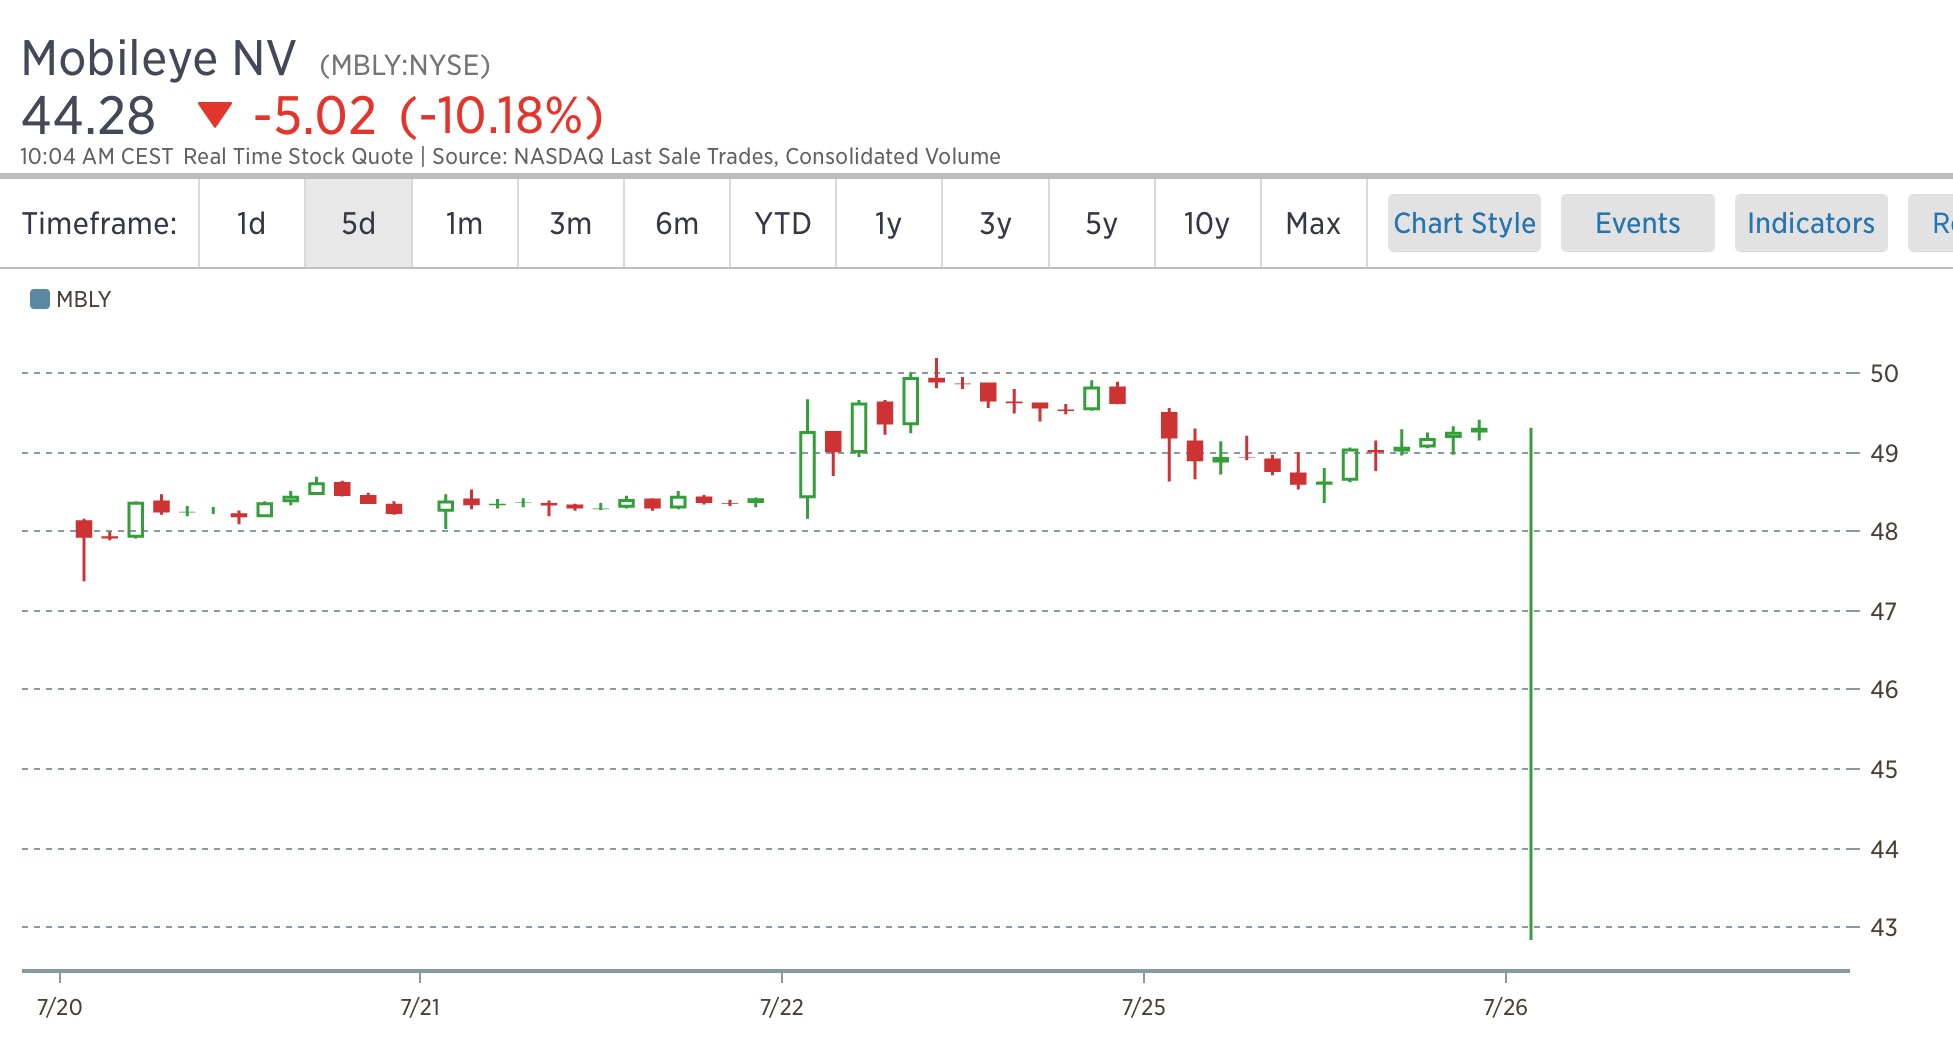
The bigger story here is why the fuck does anyone care about losing Tesla as a client? They represent just 2% of MBLY’s business and the company just beat and guided estimates up.

image

It’s like the world is operating without brains. You drop this poor stock by 10%+ after losing a very minor customer, while ignoring the stellar results just posted?

Comments »

Japanese Yen Rises Most Since BREXIT

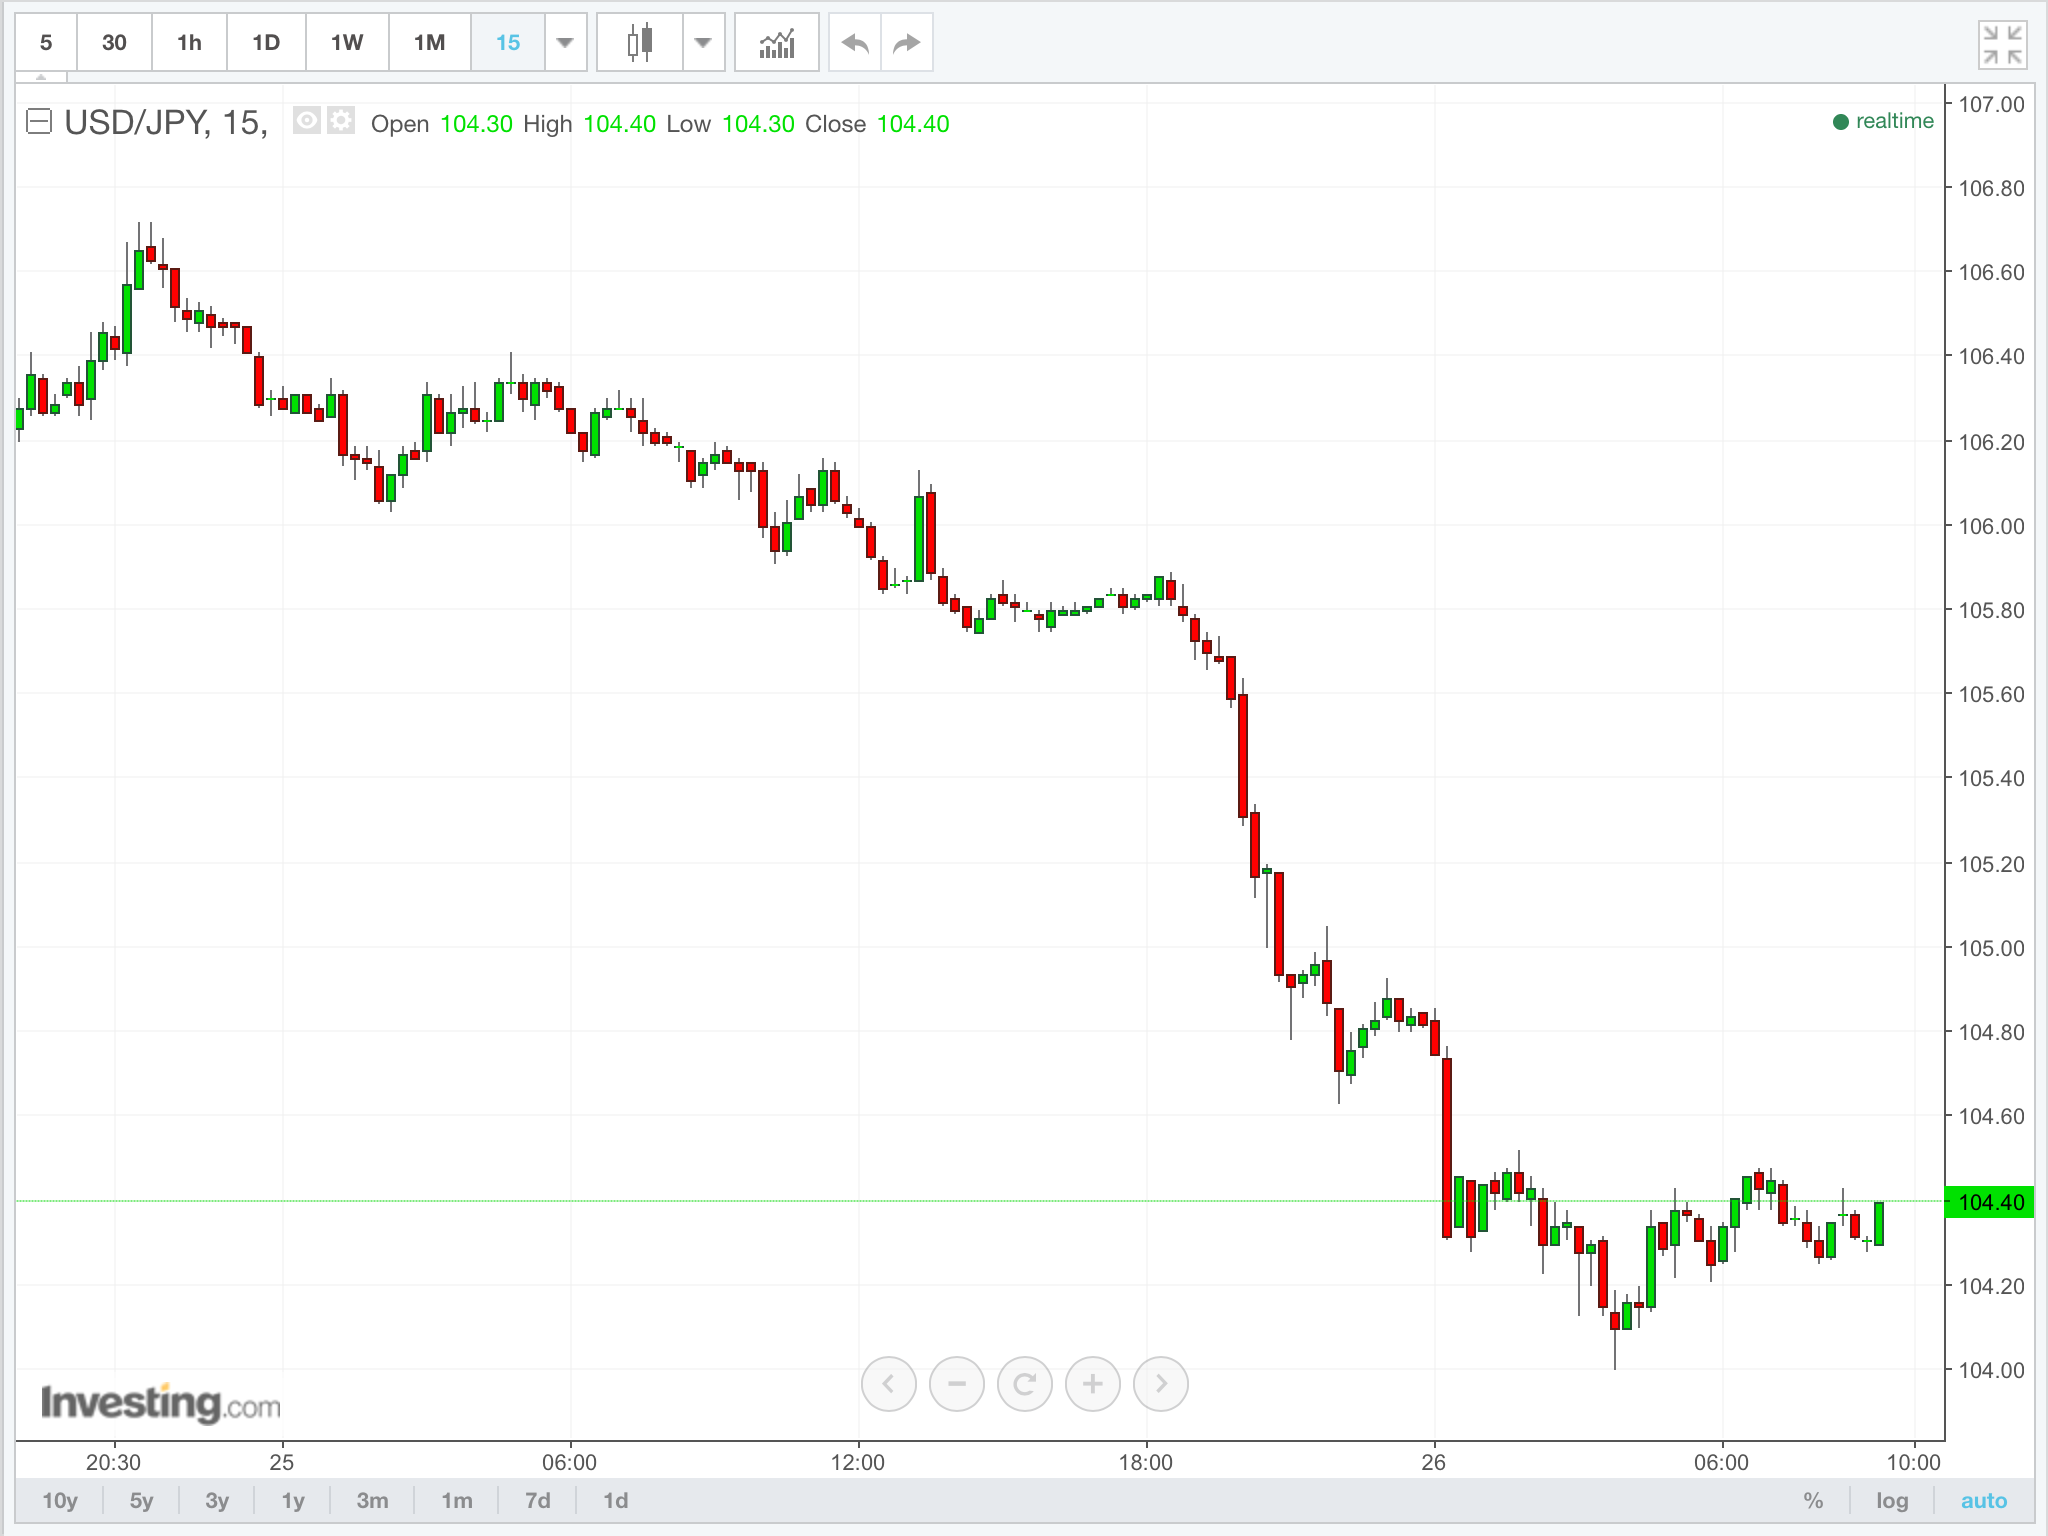
Nothing to see here little froggies. The yen is higher by 1.4% and crude is down again, now at 3 month lows. But markets have barely budged, as bulls beg for a reason to get long.

The spike in the yen, a traditional risk off asset, is the largest increase since the BREXIT vote, when the world was ending.

image

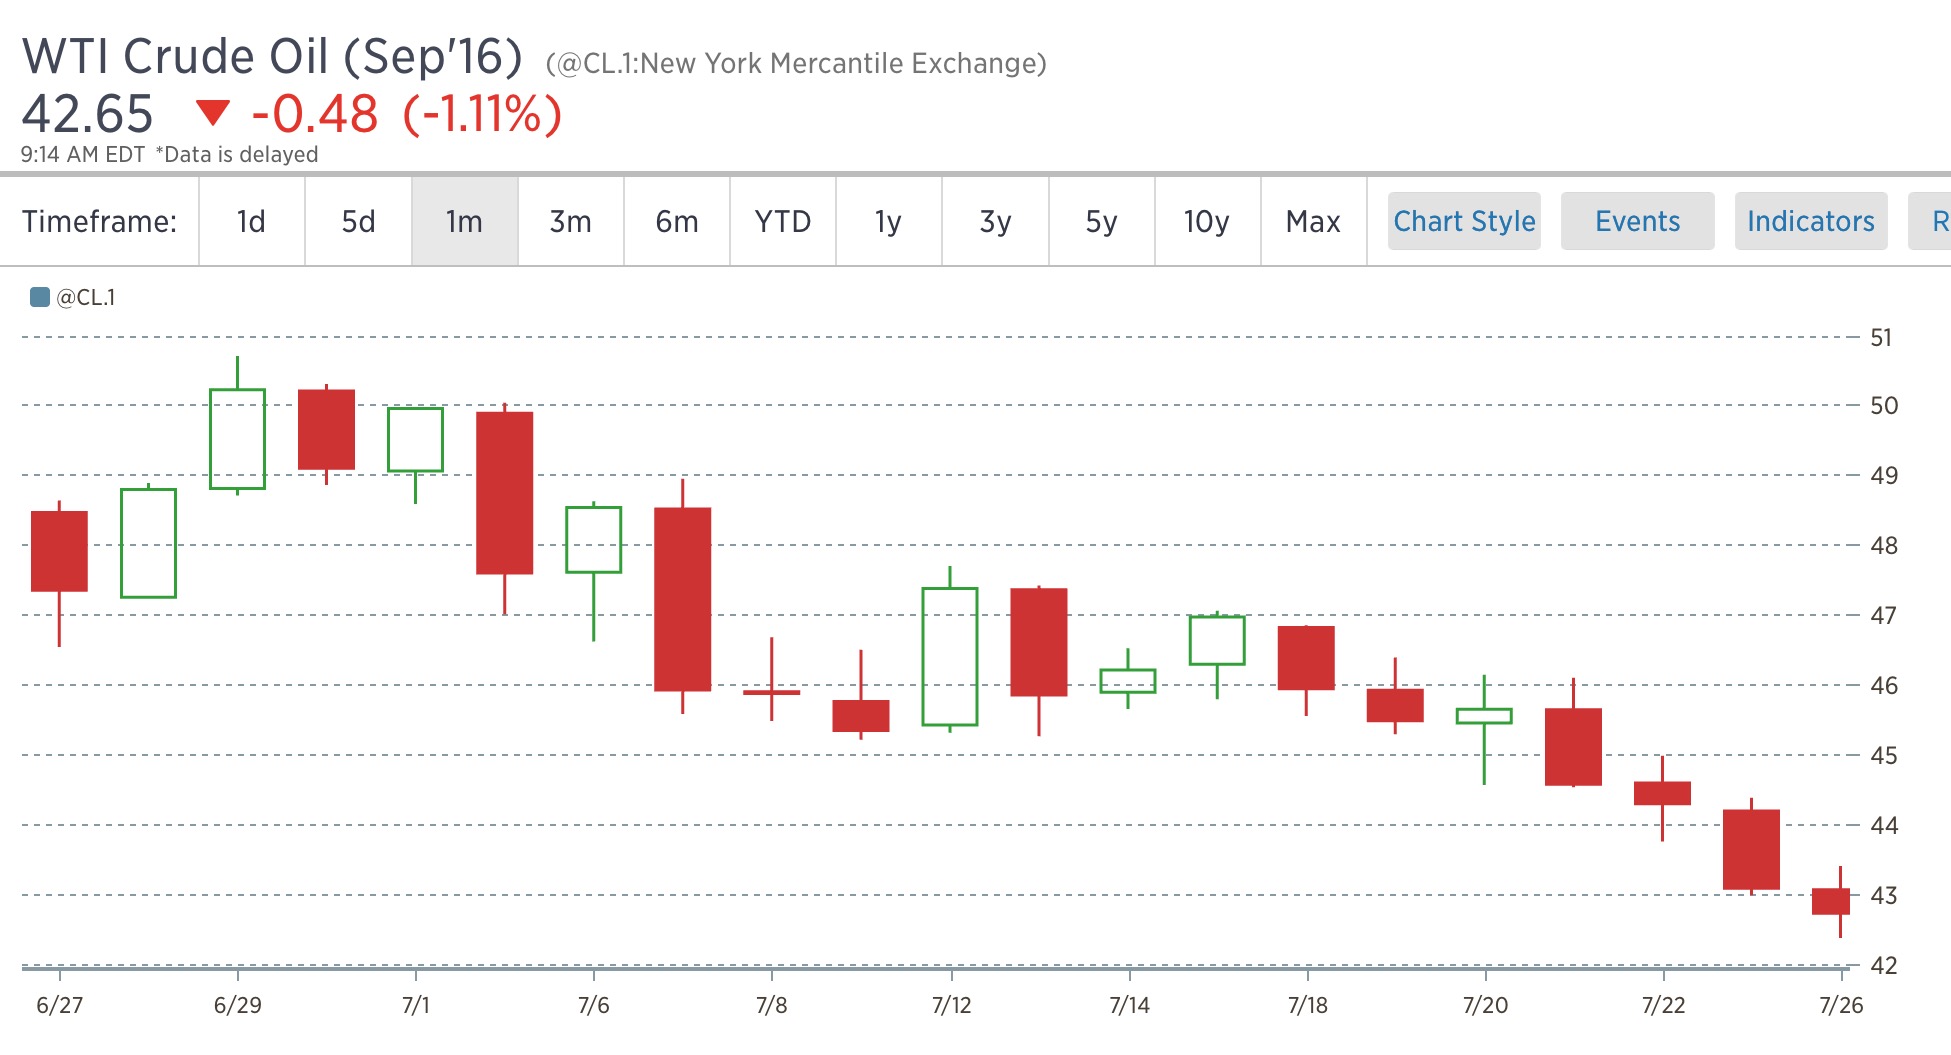
Crude oil is lower, now at 3 month lows.

image

In order to catch up, crude stocks need to fall by another 7%.

Look, we’re a whisper away from record highs. All of the hatred for the market stems from the fact that it is rigged, sort of like the elections, but indelibly worse.

The pin action in both yen and crude is reason enough to sit up and pay attention.

FYI: For those of you unfamiliar, 12631 has merged back into Exodus. Services that cost $918 per annum now cost just $459 and now everything is under 1 roof.

Comments »

Huge Piker at Amundi Likes Treasuries: Board Le Ark

The Global Head of Fixed Income at Amundi, Eric Bard, believes U.S. treasuries will continue to outperform, directly conflicting what the rocket scientists at Blackrock said today. The rationale for this ballsy call is slower than usual economic growth, which will, naturally, apply pressure onto asset prices. The same shit that’s been happening for the past two years.

“Markets are under pressure of slower economic growth, slow inflation,” Brard said. “We have a lot of inflows going into the U.S. market. We will see continuing flows in the coming months. This is good for U.S. Treasuries.”

Bard believes yields for the 10yr will drop ‘well below 1.5%’ in the not too distant future.

Oh, he also manages $1.2t.

Comments »

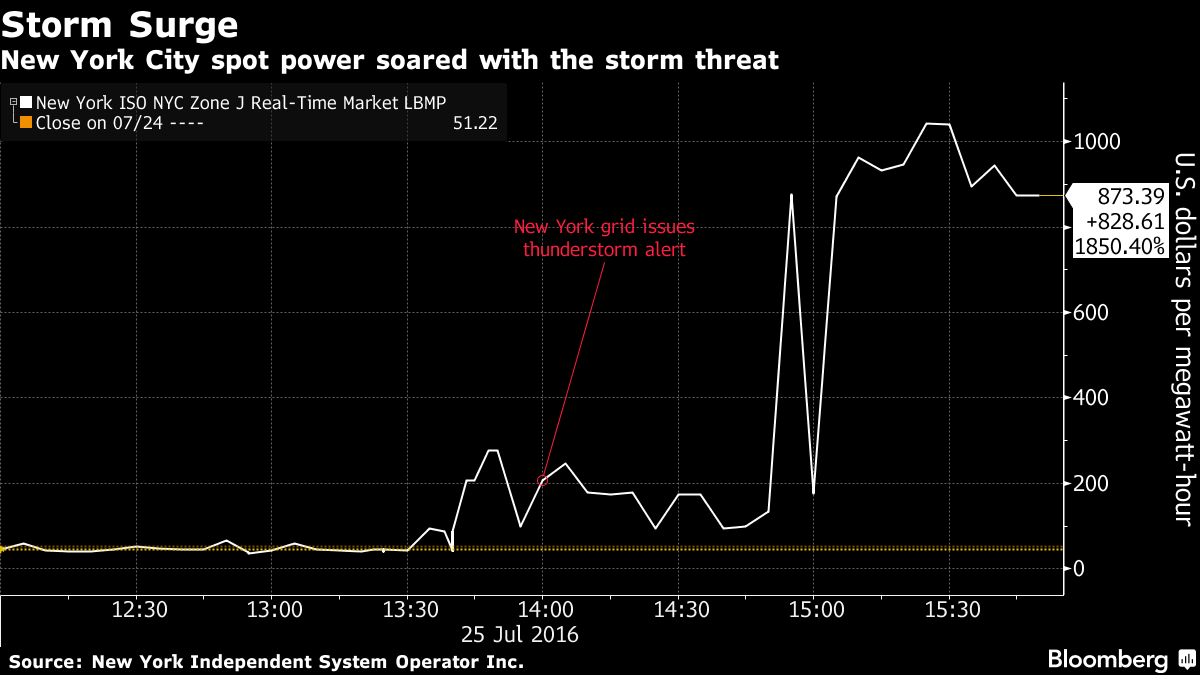
Spot Electricity Prices in NYC Just Surged 1,800% Due to Thunderstorm

This fuckery is so large, I am beyond words. Apparently, the good folks in NYC will be paying for their luxurious air conditioners. It’s quite all right, frankly. New Yorkers are exceedingly wealthy and can afford such trivial spikes in price.

energy

Spot electricity catapulted to $1,042.37 a megawatt-hour at 3:25 p.m., from less than $50 earlier in the day. The agency that oversees New York’s power system issued an alert in advance of the storm that cut the amount of electricity allowed to be carried across transmission lines feeding the city, energy data provider Genscape Inc. said.

Usually, starting up local generation can quickly ease price spikes. New York, however, is on day five of a heat wave that’s expected to last through Thursday, and backup oil-fired plants in the city are already online to help power air conditioners. So curtailing supplies is adding sparks to a power market that had, until Monday, been humming along quietly as New Yorkers boiled with the rising temperatures.

Comments »

Gary Vay-Ner-Chuk Discusses How You’re All Doomed, Especially Fake Entrepreneurs, in the Coming Storm

I’ve been meaning to share this for the past few days, but got distracted. I don’t know Gary, aside from his awesome wine videos, but I’m a fan. Since then, he’s built a kick ass ad agency and now travels the world to discuss the social renaissance that is upon us.

But not all roads are paved with gold, on the way towards paradise. Gary is calling for a 2000-2001 like collapse in the VC funded world of asshole private companies who have no idea how to book a profit. It is a great listen, well worth your 20 minutes.

Comments »

Pricing Power Continues to Erode at $GILD, Company Misses and Guides Down

This stock is a huge piece of shit. Clearly, there are pricing issues with their drug portfolio, especially for HCV.
GILD

Without putting this quarter under a microscope, I think it’s a fair analysis to assume any drug company who make a living off gouging American patients are in danger of missing numbers, in the foreseeable future.

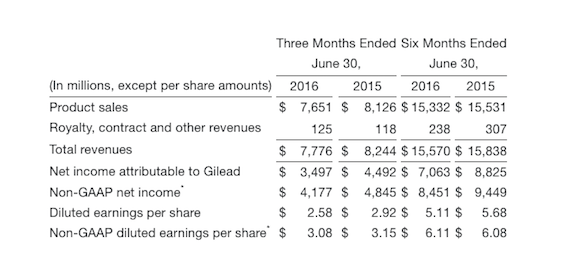
The company missed on revenues and guided lower. This has been a value trap for some time now. At some point, apathy will take hold and shareholders will revolt.

Reports Q2 (Jun) earnings of $3.08 per share, excluding non-recurring items, $0.07 better than the Capital IQ Consensus of $3.01; revenues fell 5.7% year/year to $7.78 bln vs the $7.8 bln Capital IQ Consensus.

Antiviral product sales, which include products in Gilead’s HIV and liver disease areas, were $7.1 billion for the second quarter of 2016 compared to $7.6 billion for the same period in 2015. HIV and other antiviral product sales were $3.1 billion compared to $2.7 billion for the same period in 2015.

HCV product sales, which consist of Harvoni, Sovaldi and Epclusa, were $4.0 bln (below estimates of ~$4.1 bln) compared to $4.9 billion last year, primarily due to a decline in sales of Harvoni; US HCV $2.25 bln vs. $2.1 bln ests.

Co issues guidance for FY16, lowers net product sales to $29.5-30.5 bln from $30-31 bln; reaffirms adj. gross margin 88-90%; raises R&D, lowers SG&A.
As of June 30, 2016, Gilead had $24.6 billion of cash, cash equivalents and marketable securities compared to $21.3 billion as of March 31, 2016. Cash flow from operating activities was $4.9 billion for the quarter.

During the second quarter and the first six months of 2016, Gilead utilized $1.0 billion and $9.0 billion on stock repurchases, respectively.

The stock is lower by 3.5% in the after hours.

As per conference call.

Updated FY16 Guidance:
Lowered net product sales guidance range to between $29.5-30.5 bln (prior $30-31 bln reiterated April 28)
Reiterated product gross margin guidance between 88-90%

Increased R & D expense guidance to $3.6-3.8 bln (prior $3.3-3.6 bln reiterated on April 28)
Lowered SG&A expense guidance range to between $3.1-3.3 bln (prior $3.3-3.6 bln reiterated on April 28)
The change in guidance from 1Q16 was primarily driven by patient flows & payer flows, did not change US prices, notes a ‘successful’ program from VA, more heavily discounted payers impacted results

Amount of people treated with a Sofosbuvir-Based Regimen +116.8% y/y to over 1 mln patients

Since the beginning of the year, access has improved, almost all major commercial payers have been joining Medicare and the VA.
When asked to provide color on Hepatitis B product developments:
2 compounds in clinical development, a vaccine in the later stages of being evaluated in non-surpressed patients, in the later stages of being evaluated in hep B patients, those data have been released & did not show any activity, doesn’t have high hopes this compound will work.

Notes the TLR seven agonist is just finishing the first cohort, co is currently initiating study, hopes to have the presentation by the extract deadline.
Pursuing three approaches to hepatitis B, one is adding another mechanism to the nucleotides because there is the observation that this might be undetectable
Sees little change in their Medicaid biz, notes public payers were about 45% of total, driven by VA
Estimates that 3 mln individuals remain affected with HCV in the U.S., approximately half of whom are diagnosed.

Expects sequential decrease in cash flow in the second half of the year, less focused on share repurchases in second half of year after a ‘very aggressive’ 1Q16 buyback

Comments »