iBankCoin
Home / 2016 / July (page 4)

Monthly Archives: July 2016

DOWN GOES OIL

An inventory build of 1.7m barrels v expectations of a 2.25m draw is to blame for today’s rout. Frankly speaking, this decline has been pervasive for several months now. Wall Street has been ignoring the pressures on crude, in exchange for cocaine rallies. Truth be told, we’re at 3 month lows, off by 12% for the month and the sector looks both bleak and dreadful.

image

Humans are a simple creature. Oil hits $39 and the fucking hounds from hell will be unleashed upon stocks. In the meantime, enjoy your pastoral views.

Comments »

FBI’s Comey: A ‘Diaspora’ of Terrorist Attacks to Strike the West Soon

They’re preparing us for more attacks, so that it seems normal. This is classic military conditioning, training the populous to accept a standard of living less than ideal because, well, there isn’t anything we can do about it.

Director Comey is out with startling words today, in reference to a swath of new attacks he sees coming to both Europe and the United States.

“At some point there’s going to be a terrorist diaspora out of Syria like we’ve never seen before,” Comey said Wednesday at a cybersecurity conference in New York.

“This is an order of magnitude greater than anything we’ve ever seen before,” he said, comparing the potential to previous attacks directed or inspired by the group. “We saw the future of this threat in Brussels and in Paris

I’d say this bodes poorly for restaurant stocks.

Comments »

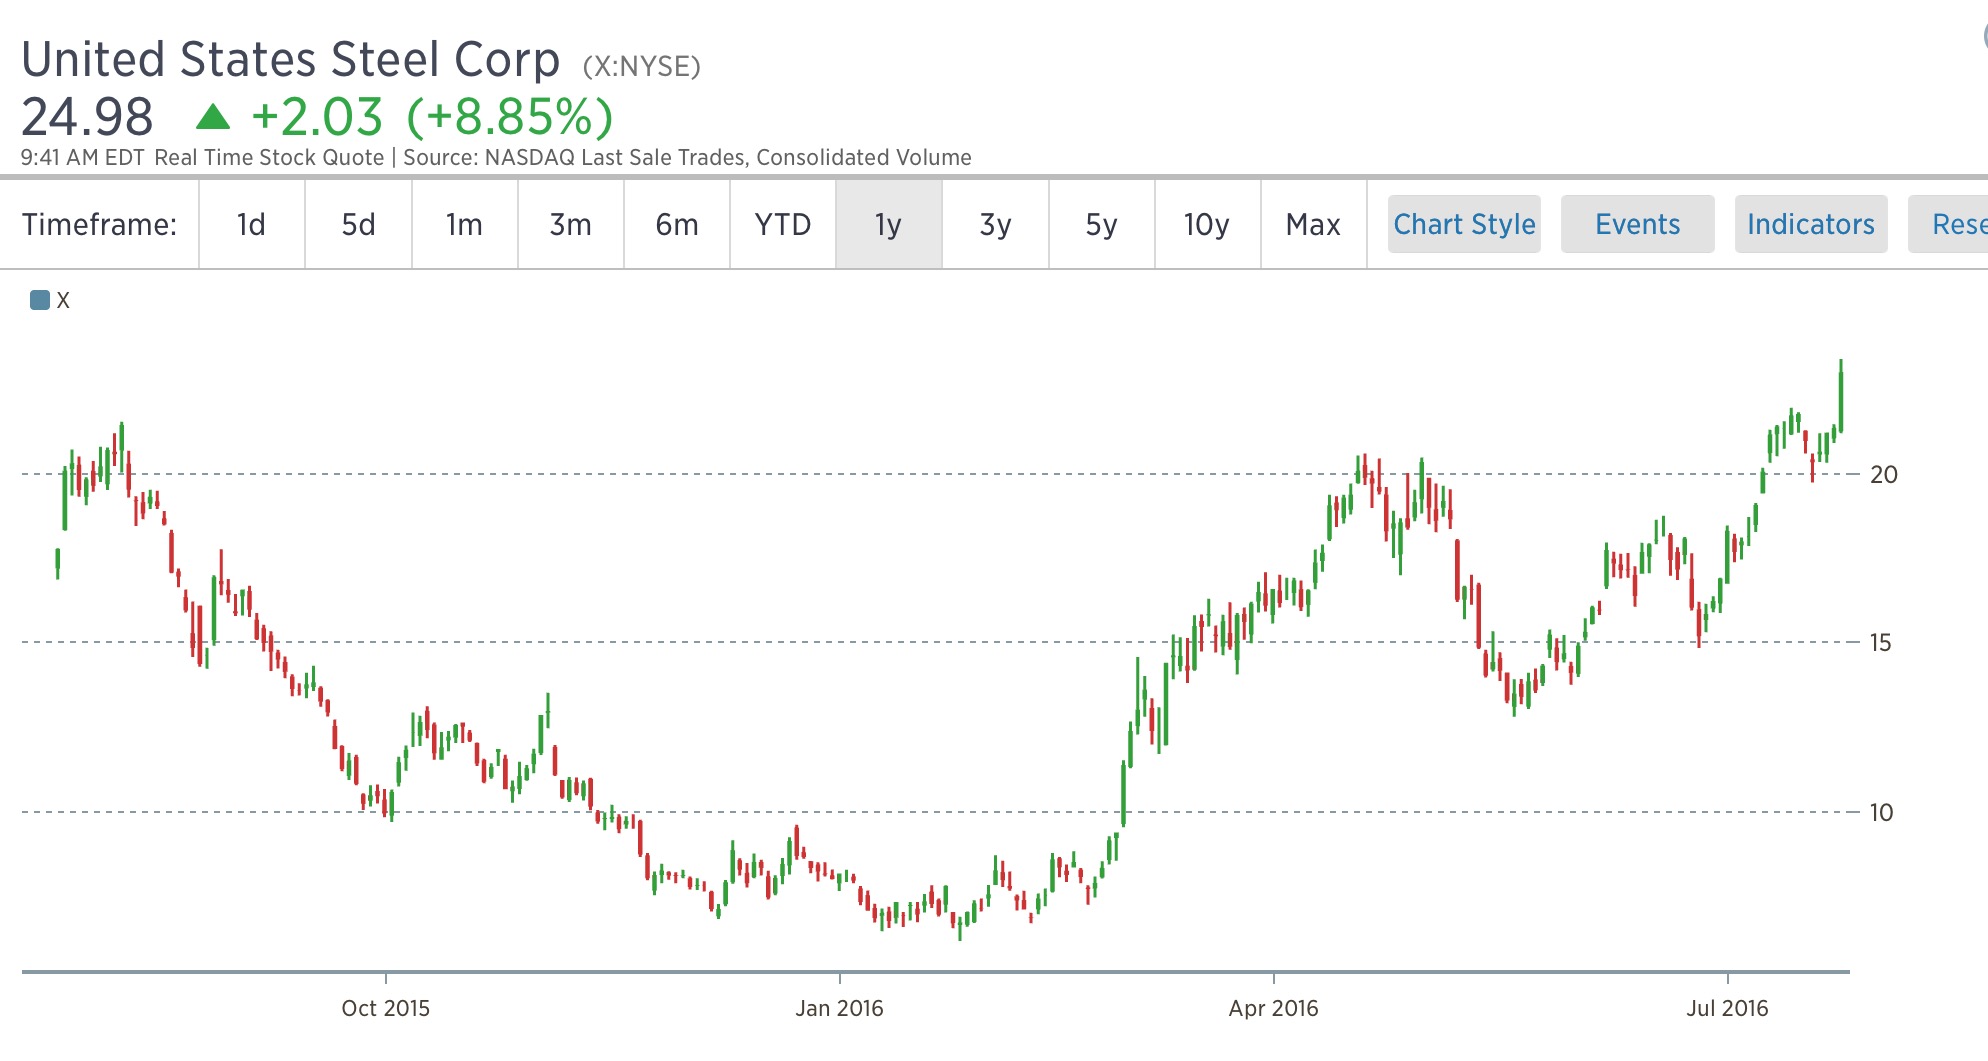
U.S. Steel Surges to Fresh 52 Week Highs on Positive Outlook

This is my singular high risk pick in Exodus and one of the 15 GARP stocks that I’ve chosen for the 2nd half of 2016. In my estimation, this is the best way to play a Trump presidency, as his policies proposed will directly benefit companies like X.

Shares are crushing higher after the company beat estimates and offered some positive guidance.

“The significant improvements we have made to our earnings power through our Carnegie Way transformation will become more apparent as market prices recover from the very low levels at the end of 2015. While we began to realize some benefit from recent price increases in the second quarter, we will see better average realized prices, primarily in our Flat-Rolled and European segments, in the second half of the year. Our Carnegie Way journey continues to create improvements in our business model that will enable us to be profitable across the business cycle.”

image

Any move against Chinese dumping or surge in polls for Trump will breathe new life into X. On the flip side, should Hillary rise in the polls, this might lose some of its gusto.

Comments »

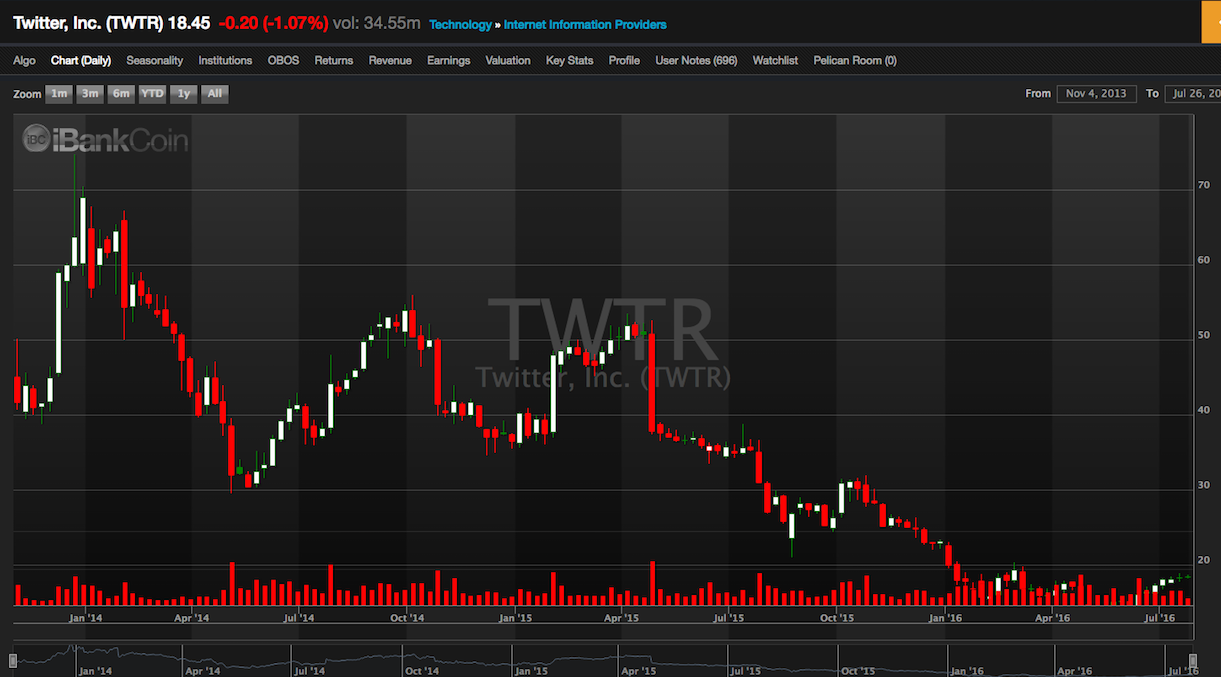
Wall Street Repudiates @Jack; Shares of $TWTR Reel Lower Amidst Flurry of Downgrades

Multiple firms are stepping aside on TWTR this morning and downgrading the stocks, following yesterday’s earnings disappointment. The overall hope is that live events will propel free cash flow and make Twitter great again. However, most analysts believe management is complacent and comfortable with the status quo, one that is okay with tepid new user growth.

As such, shares are reeling and will likely continue to struggle until next quarter.

image


27-Jul-16 07:28 ET | TWTR | (18.45 )
Twitter downgraded to Hold from Buy at Cantor Fitzgerald following earnings

27-Jul-16 06:53 ET | TWTR | (18.45 )
Twitter target lowered to $17 from $20 at RBC Capital Mkts — “#MissAndLower”
Firm noted rev of $602MM missed Street at $608MM, importantly with Ad Rev of $534MM below ests of $540MM. But EBITDA of $175MM (29% Margin) was above Street expectations at $154MM. TWTR Q3 Rev guide of $590-610MM was about 14% below the Street at the mid-pt; EBITDA disappointed, too (18% below Street at mid-pt). Ad Pricing pressure seems to be a significant factor, which syncs with the Twitter advertiser challenges firm has detected in their survey work. They remain cautious on co’s ability to show meaningful user growth in the NT, but mgmt sounded confident in product & marketing improvements.

Axiom Capital downgrades TWTR to Hold from Buy and lowers their tgt to $16 from $18 following the Q2 report. In late May, with the shares at ~$13 and near their bear case valuation scenario, firm viewed the risk-reward of owning the shares at that level as favorable, with news events in the quarter presumably driving usage, live events and Periscope driving engagement and ad growth, and M&A potential driving the stock toward their previous $18 price target, which the stock met heading into the earnings results. However, firm was disappointed by the continued weak user growth (+3% YoY, +3M MAUs), the miss on advertising revs, and the guidance materially below their 3Q ests, implying O&O advertising growth in the HSD. Mgmt cited increased competition for social media ad budgets, a continuation of lower advertiser demand, and ad pricing at a premium to other platforms. These headwinds are expected to persist and there is very little visibility into the timing of O&O advertising growth re-acceleration. Co’s saving grace, and quite frankly its last stand, is live events/Periscope which should in theory drive up engagement and drive advertising to the platform. They are optimistic on live events but firm is unsure if this will be enough at this time to offset the current challenges. As a result they are moving to the sidelines.

Wedbush lowers their TWTR tgt to $14 from $20 following earnings. Firm notes co remains “the place to go” for live broadcast, but mgmt appears complacent about the status quo and unfocused on the lack of user growth. Until co is focused on attracting new users, driving increased use by its existing users, and demonstrating its value proposition to people who don’t use the service, firm expects it to grow very slowly. They think that its service is too complicated and difficult to use for the average Internet user despite multiple changes. They attribute recent share price appreciation to speculation that co may be acquired, but in their view, there is no clear-cut potential buyer

Canaccord Genuity downgrades TWTR to Hold from Buy and lowers their tgt to $16 from $20 following earnings. Firm notes, “We are late to downgrade the stock, and we think downside is fairly limited, but for us the character of the potential turnaround has changed over the past two quarters from “fix the product and revenue will follow” to “build a live mobile video business.” While we believe the company has a good chance of achieving this, it will likely take several quarters to know. Twitter could still be an attractive acquisition, and we view this as significant upside risk, but for now we believe fundamentals will be sufficiently challenged to move to the sidelines.”

Comments »

Third Point Posts 4.6% Return in Q2, Led By High Yield Energy Bets

Dan Loeb, aka Mr. Pink_esq, booked a huge return for the second quarter, reversing his short bets in the energy sector and getting long over $1b–into the teeth of CHK bankruptcy rumors.

Loeb conducted all of these acts of heroism and financial winship in the month of February, a time when most managers were soiling themselves, neck deep in losses.

He sold out of AMGN, mainly because it bored him and continues to hold large bets in both AGN and BAX, which is his largest holding.

“The year’s positive performance reflects contributions from nearly all of the strategies we employ; the top five winners include a constructive long equity position, a sovereign debt investment, high-yield debt investments in energy companies, an event-driven long position, and a short equity position in the pharmaceutical industry,” Third Point said.

Third Point has played 2016 like a fine tuned violin this year, almost perfect. God willing they will flail and then implode in the quarters to come.

Comments »

NIKKEI SOARS ON REPORTS OF MASSIVE STIMULUS PACKAGE

The yen is plummeting this evening on rumors that Japan will undertake a massive 27t yen stimulus package, which is 5x the amount previously discussed. The Yen is currently trading 105.86 vs the dollar, down 1.17%. The NIKKEI is responding, in kind, higher by more than 2.2%

These fucked up rumors of degeneracy include the launch of a comical 50yr bond, 13t in low interest loans (also comical) and an explicit intent to cause inflation, which is the most comical of them all.

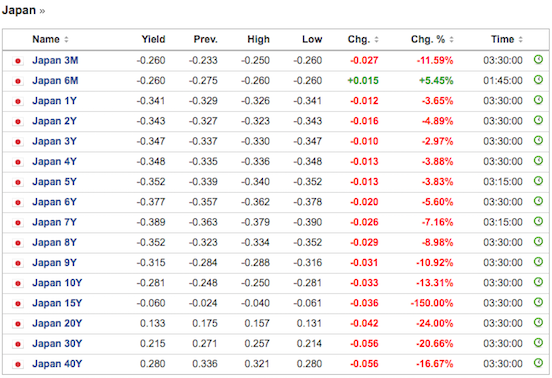
Interestingly, Japanese bonds are now raging higher, which is pushing yields even further into negative territory. Might I add this is, by definition, deflationary.

Japan

Comments »

Cramer to @Jack: Pick a Dog, Square or Twitter

This evening on Maddening Money, Cramer discussed how it’s okay for growth to be non-existent and how ‘good enough’ is enough to propel stocks to record highs. He was laying on his Orwellian propaganda good and heavy this evening. Then he discussed the disappointments in the market and touched on  a point that is rarely discussed, regarding Twitter.

The CEO, Jackard Dorsey, is presiding over not one but two companies, into the ground. Year to date, both TWTR and SQ are maligned with large losses, in excess of 20%. Since Jackard took over the role as CEO of Twitter, the shares are down 55%.

Cramer makes a valid point, when he states “it is time for Jack Dorsey to pick Twitter or Square. It’s bad enough  he’s CEO of one underperforming company, but to be CEO of two troubled entities. Please, one or the other, but not both.”


Comments »

$AAPL Beats, Guides Higher, Reveals Lackluster Growth and Margins

Tim Cook did it again, sort of. The company posted better than expected results, and even guided up. Margins were a little soft. But who really gives a shit about that?

From a layman’s viewpoint, those iPhone sales are looking awfully PCish, coming in at 40.4, down from 47.5 last year. Growth has slowed to the point that this is now a financial engineering company, one that will benefit from cost cuts. Apple is the new Dell.

  • Reports Q3 (Jun) earnings of $1.42 per share, $0.04 better than the Capital IQ Consensus of $1.38; revenues fell 14.6% year/year to $42.36 bln vs the $42.1 bln Capital IQ Consensus; gross margins of 38.0% vs 37.9% ests vs 39.7% last year.
  • iPhones 40.4 mln vs 40.2 mln ests vs 47.5 mln last year.
    • iPads 9.95 mln vs 8.7 mln ests vs 10.9 mln last year.
    • Macs 4.2 mln vs 4.6 mln ests vs 4.4 mln last year.
  • Americas rev -11%; Europe -7%; China -33%; Asia/Pac -20%.
  • Co issues upside guidance for Q4, sees Q4 revs of $45.5-47.5 bln vs. $45.8 bln Capital IQ Consensus Estimate; gross margin 37.5-38% vs. 38.3% ests.

Shares are higher in the after hours by 5%.

Comments »

Twitter Shaves Q3 Guidance; Shares Collapse in the After Hours

Any way you slice it, these numbers were an abomination. They aren’t adding new users, even with their fake bot creating machines. The company just guided revenues down by an astounding $90 million and they’re far from being free cash flow positive. One must ask the question: is @Jack the one to lead this company?

The bottom line is this: On June the 10th, 2015, the day Jack Dorsey took over Twitter as CEO, the share price was $36.85. Right now, in the after hours, the stock is trading at $16.70 (-10.5%), down 53% since his reign of terror began.

TWTR


  • Reports Q2 (Jun) earnings of $0.13 per share, $0.04 better than the Capital IQ Consensus of $0.09; revenues rose 19.9% year/year to $602 mln vs the $607.41 mln Capital IQ Consensus.
  • MAUs
    • Average monthly active users (MAUs) were 313 million for Q2, up 3% year-over-year and compared to 310 million in the previous quarter.
    • Average U.S. MAUs were 66 million for Q2, up 1% year-over-year and compared to 65 million in the previous quarter.
    • Average international MAUs were 247 million for Q2, up 4% year-over-year and compared to 245 million in the previous quarter.
    • Mobile MAUs represented 82% of total MAUs.
  • Revenue Breakdown
    • Advertising revenue totaled $535 million, an increase of 18% year-over-year.
    • Mobile advertising revenue was 89% of total advertising revenue.
    • Data licensing and other revenue totaled $67 million, an increase of 35% year-over-year.
    • U.S. revenue totaled $361 million, an increase of 12% year-over-year.
    • International revenue totaled $241 million, an increase of 33% year-over-year.
  • Ad Engagements
    • Total ad engagements were up 226% year-over-year.
    • Cost per engagement (CPE) was down 64% year-over-year.
  • Co issues downside guidance for Q3, sees Q3 revs of $590-610 mln vs. $681.34 mln Capital IQ Consensus Estimate.
  • For Q3: 
    • Adjusted EBITDA to be in the range of $135 to $150 million;
    • Stock-based compensation expense to be in the range of $165 to $175 million.
  • For FY 2016 expect:
    • Capital expenditures to be $300 to $375 million (Prior $300-425 mln);
    • Adjusted EBITDA margin in the range of 26-27% (Prior 25-27%).

Comments »