I think you should take an hour and listen to the $NVDA conference call to really grasp what is happening here. I know the stock is down 7% in the AHs because margins dropped from 78% to 75%, but please. This is the most important company in the world and it isn’t even close.
Here is the co discussing how AI is collapsing computing costs because the speed to run programs are operating at 50x the speed of normal applications.
The company also discussed how their “sovereign AI” business is now in the billions and growing rapidly. The CEO expressly mentioned how the “next trillion” in AI rollouts would build upon the first and increase productivity and margins. This is all super bullish, not only for $NVDA, but the entire Fortune 500 complex. We are talking about AI actually REDUCING energy expenses due to rapidity of programs. This stock should be bought on dips.
The second story of note are barnstormer earnings at $AFRM. I will have more to say about this tomorrow, as I intend to listen to the call before I sleep.
Affirm beats by $0.34, beats on revs; guides Q1 revs above consensus (31.58 -0.93)Reports Q4 (Jun) loss of $0.14 per share, $0.34 better than the FactSet Consensus of ($0.48); revenues rose 47.9% year/year to $659.2 mln vs the $603.67 mln FactSet Consensus.Gross Merchandise Volume (GMV) grew 31% year over year to $7.2 billion and significantly outpaced overall e-commerce growth. Transactions on the Affirm network grew 42% year over year to 24.7 million in FQ4’24, and 15% sequentially vs. FQ3’24 Co issues upside guidance for Q1, sees Q1 revs of $640-670 mln vs. $625.04 mln FactSet Consensus.GMV of $7.1-7.4 bln. Adjusted operating margin of 14-16%
Incredible, and bullish for retail.
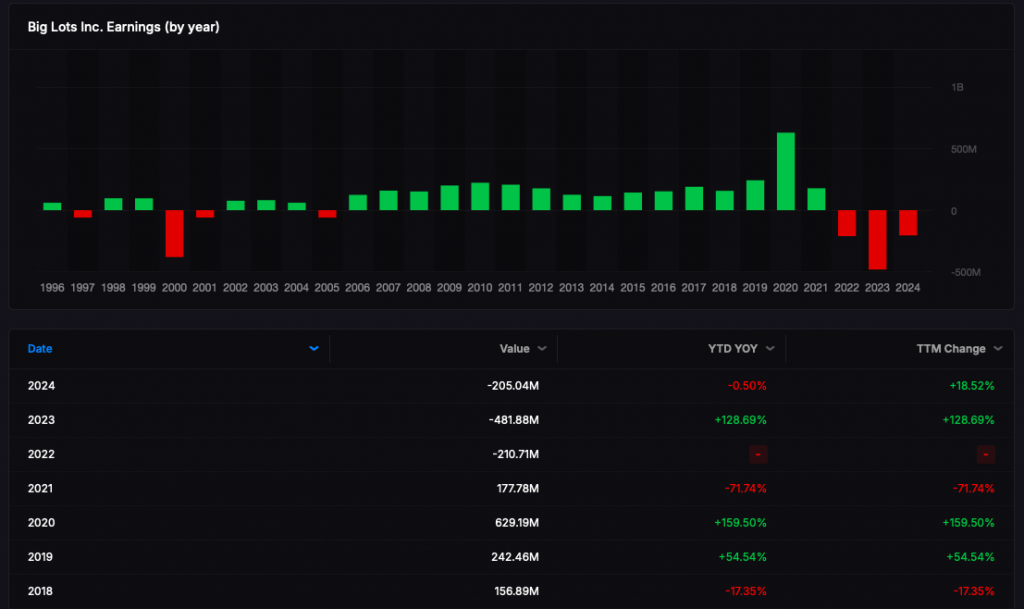
Last is the bankruptcy rumors at $BIG and it is a teachable lesson. The stock was just $60 a few years ago and operated discount stores profitably for decades and employed over 10,000 people and now it’s a zero. Why? For whatever reason in 2018 the company decided to leverage up the balance sheet and take on debt.
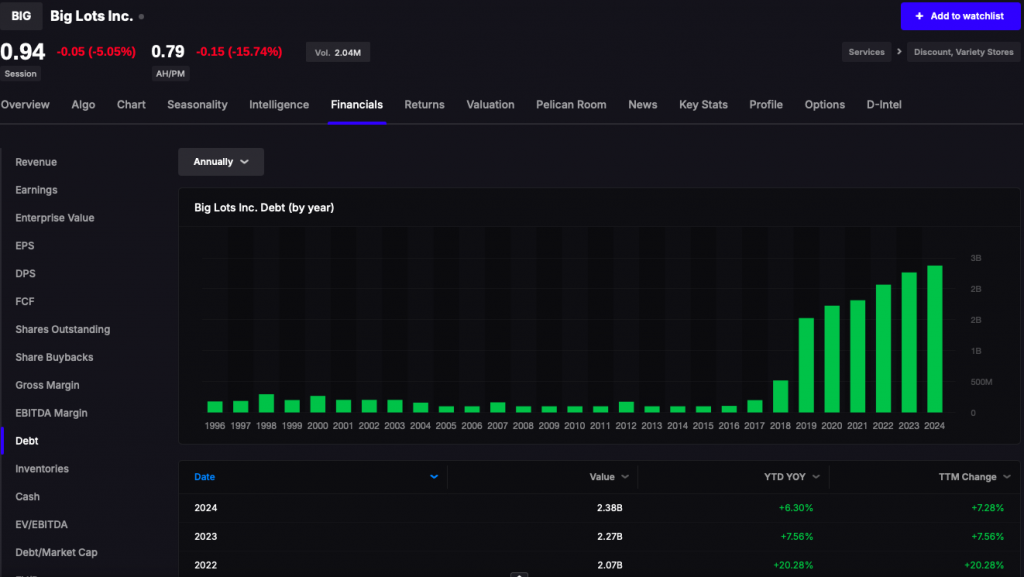
All it took was 3 bad years and it’s game set match for an iconic discount retailer. The lesson is, stop being fucking greedy and don’t take sojourns into debt and attempt to scale retarded discount stores.
So why did Biglots do this? The answer is always the same: NEW CEO!
In 2018 the company appointed Bruce Thorn as CEO and his plan for the company, similar to what RON JOHNSON did to JC Penny may years ago with Bill Ackman, was to transform Biglots into a chic retailer.
In 2018, Big Lots took on a significant amount of debt primarily to fund its strategic initiatives, including store renovations and expansions. The company aimed to enhance its store experiences and remodel existing locations to drive sales growth. Additionally, the debt helped support their growth strategies, such as expanding their store base and investing in supply chain improvements.
The company’s decision to take on this debt was part of a broader effort to position itself for long-term success amid a competitive retail environment. However, such debt can also increase financial risk, making it crucial for the company to effectively manage its cash flows and execute its strategies successfully to ensure it can meet its debt obligations and achieve its growth targets.
The results? FLOP