iBankCoin
Home / 2016 (page 241)

Yearly Archives: 2016

$CAT WARNS

Sales declined in all segments in every part of the world. In other words, every aspect of CAT’s business sucks, yet you monsters keep bidding up the stock.

Shares are off by a pedestrian 2.2% in the pre. Don’t worry, CAT will ‘cost save’ some more by replacing annoying humans with fucking robots.

image

Via briefing.com

Reports Q1 (Mar) earnings of $0.67 per share, ex-items, $0.01 worse than the Capital IQ Consensus of $0.68; revenues fell 25.5% year/year to $9.46 bln vs the $9.45 bln Capital IQ Consensus.

Co guided Q1 EPS $0.65-0.70 vs. $0.95 consensus on March 17
“While first-quarter results were about as we expected, sales and profit were well below the first quarter of 2015. Sales declined across the company with substantial reductions in construction, oil and gas, mining and rail. While many of the industries we serve are challenged, we remain focused on what we can control: the quality of our products, our market position, safety in our facilities and continued restructuring and cost reduction. In fact, our period costs and variable manufacturing costs in the quarter were nearly $500 million lower than the first quarter of 2015,” said Caterpillar Chairman and Chief Executive Officer Doug

The decrease was primarily due to lower sales volume. While sales for both new equipment and aftermarket parts declined in all segments, most of the decrease was for new equipment. The unfavorable impact of price realization and currency also contributed to the decline

Sales declined in all regions. Sales decreased in all segments.
Overall machine market position better i n Q1 of 2016 than this point last year; continues to improve in China. Focus remains on quality, safety and cost reduction

Co lowers EPS guidance for FY16 to $3.70, ex-items, vs. $3.60 Capital IQ Consensus Estimate, from $4.00; lowers FY16 revs guidance to $40-42 bln vs. $41.08 bln Capital IQ Consensus Estimate, down from $40-44 bln

The decline in the midpoint of the sales and revenues outlook range is a result of several factors that, while not individually large in the context of the outlook, collectively add up to about $1 billion

Those factors include lower transportation sales (rail, marine and the ending of production of on-highway vocational trucks), lower mining sales and weaker price realization than previously expected.
Comments »

$XON Responds to ‘False and Misleading’ Seeking Alpha Report; Cites Hedge Fund with an Ax to Grind as Source

Intrexon is  trying to kill the messenger and not the message, which,  in my opinion, is a mistake. Believe me, no one is a bigger Randall J. ‘Fucking’ Kirk fan than me. But blaming evil hedge funds for shorting your stock and taking a short position against you, one day after your stock plunged by 25%, probably isn’t what shareholders want to hear.

They want fire and brimstone. This is subterfuge.

In this case, however, Intrexon is providing this update given the inaccuracy of the report’s content, the stated intent of the publisher to issue several more spurious reports in the coming days, and information received last night regarding the erroneous publication
Yesterday evening, Intrexon received a draft report, dated Dec 2015, which contained similarly inaccurate claims and strikingly similar language, in some parts identical words, to that used in yesterday’s report. Moreover, Intrexon received information that the source of the report was a particular hedge fund seeking to discredit Intrexon. The hedge fund, according to our information, desired to take a short position in the company’s stock, was seeking a willing publisher of its report on the company, and intended to benefit from trading activity caused thereby
Based on this information, Intrexon believes that it is the target of a campaign to manipulate trading in the company’s securities, interfere with the company’s business operations, and destroy the reputation of the company and its chairman and CEO
Intrexon, with the advice of counsel, is taking appropriate steps in light of these developments

The stock is up a smidge in pre-market trading.

Comments »

Goldman: Iron Ore Prices to Drop 50% From Current Levels

I know. No one cares about this at all. It’s sort of like not caring about where oxygen comes from. We all just take it for granted. We go outside and commit heinous acts and expect that oxygen to be there for us, in order to propel us forward. The same thing happens with iron ore and steel.

Goldman is looking for it to be halved…from current levels.

“We think this market will go back to $35 during the fourth quarter,” analyst Christian Lelong said in an interview. That’s 50 percent below Thursday’s close of $70.46 a dry metric ton, the highest level since January 2015. “Our expectation is the oversupply in the iron ore market will return.”

Iron ore has surged in 2016 in sharp contrast to the previous three years, when a slowing Chinese economy hurt prices and too much supply chased too little demand. This year, policy makers in China have talked up growth and added stimulus, presiding over a revival in the property market that’s boosted the outlook for steel consumption. Still, burgeoning supply and stalling demand growth may once again drag prices down, according to Goldman.

QuickTake Iron Ore

“Going into the second half of the year, what are you going to need to absorb all that iron ore supply?” New York-based Lelong said by phone from London on Thursday. “It’s going to be very hard to have strong enough demand growth in the Chinese steel sector to keep things in balance.”

Armageddon.

Comments »

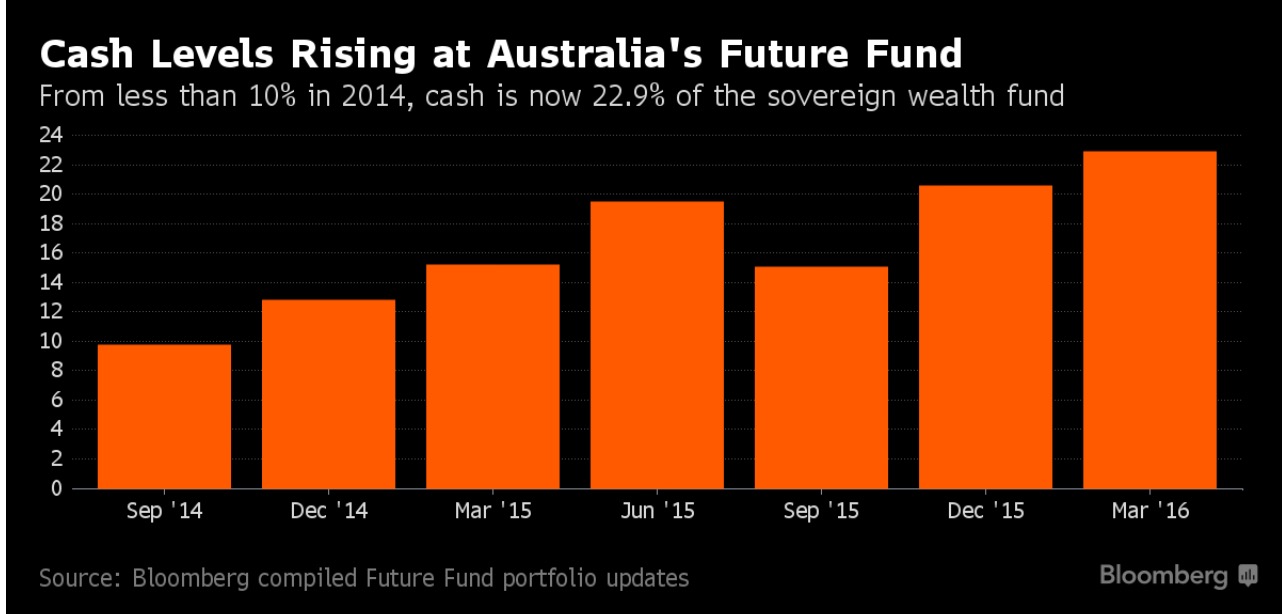
Australia’s $90 Billion Soverign Wealth Fund Ups Cash Position to 25%

This beer swillers from down under are too busy playing with the kangaroos than to manage money in this market.

Australia’s sovereign wealth fund is famous for investing like cowards. They’ve doubled the fund since 2006 by attaining a pathetic 7% annual return by practicing a conservative form of investing.

image

That conservatism just went nuclear bomb shelter 25% cash, waiting for the fucking planet to tilt and then explode.

“We see prospective returns on risk at a lower level than in the immediate past years,” said Peter Costello, chairman of the fund and the nation’s former treasurer. “We are also conscious that monetary authorities, having stimulated so much, have less flexibility now to respond to future weakness. Given this, we have less risk in the Future Fund than we would under more normal circumstances.”

Comments »

Kerrisdale Capital Raises $100 mill for Single Short Idea

The pitch is simple.

Give us $100 million to sell short a stock that we will first publish on our blog, effectively guaranteeing any early investors an instant profit.

“We raised a meaningful amount of capital (in) a very short timeframe, so clearly we struck a chord within the alternatives community,” Adrangi wrote in an email to investors Wednesday reviewed by Reuters.
“We’ve taken a company that’s worth north of $10 (billion), and we’ve endeavored to get everyone to understand the insights we have about it,” Adrangi added in the note.

Kerrisdale is one of the many bearshitter websites that go spastic frenzied against a singular stock, issuing scathing reports that scare the shit out of longs and draw in a cadre of blood sucking vampires to pile in short upon seeing their reports. The result is usually a sharply lower share price on the day the report is published, which, by extension, is a round about way to front run.

This special short idea will be unveiled in May, at which time all of the capital would’ve been allocated towards seeing its decline, naturally.

Comments »

$AMD Up Huge in After-Hours on Massive Beat and Guide Higher

Is AMD back? Does it matter at this point, seeing that INTC had humiliated them over the past decade?

Nevertheless, these numbers out tonight are very impressive and should propel the stock, in a significant way, tomorrow and beyond.

  • Reports Q1 (Mar) loss of $0.12 per share, excluding non-recurring items, $0.01 better than the Capital IQ Consensus of ($0.13); revenues fell 19.2% year/year to $832 mln vs the $818.41 mln Capital IQ Consensus.
  • Gross margin of 32 percent, up 2 percentage points sequentially, due primarily to a richer product mix and the mix of revenue between business segments.

Margins up, big top and bottom line beats. On top of that, the company just guided up in a big way.

Advanced Micro sees Q2 rev +12-18% QoQ to ~$932-982 mln vs $889.66 mln Capital IQ Consensus Estimate 

AMD is higher by 20% in the after-hours at a fresh 52 week high.

Comments »

$SAM Misses and Warns; Stock Roundly Pummeled in After-Hours

The competition in the swill sector has taken its toll on the firebrand Sam Adams Brewing company. While the disgusting beer over at BUD continues to sell like hot-cakes, the halfway decent beer at SAM is under significant pressure by the thousands of innovative and aggressive craft beer operators.

Via Briefing.com

  • Reports Q1 (Mar) earnings of $0.53 per share, $0.44 worse than the Capital IQ Consensus of $0.97; revenues fell 5.4% year/year to $188.8 mln vs the $198.15 mln Capital IQ Consensus, due to a decline in core shipments of 6%, partially offset by price increases.
  • Co issues downside guidance for FY16, sees EPS of $6.50-7.30 vs. $7.83 Capital IQ Consensus Estimate.
  • Underlying the Company’s current 2016 projection are the following 53-week full-year estimates and targets:
    • Depletions and shipments percentage change at between minus 4% and plus 2%.
    • Price increases of between 1% and 2%. Gross margin of between 51% and 53%.
    • Increased investment in advertising, promotional and selling expenses of between zero and $10 million, a decrease from the previously communicated estimate of between $10 million and $20 million.
    • Estimated capital spending of between $50 million and $70 million, which will be mostly spent in our breweries to support future growth and product innovation and to drive efficiencies and cost reductions.
  • “We believe Samuel Adams has lost share due to the increased competition and continued growth of drinker interest in variety and innovation. During the quarter, we rolled out new beers, including Samuel Adams Nitro White Ale, Samuel Adams Nitro IPA, Samuel Adams Nitro Coffee Stout and Samuel Adams Rebel Grapefruit IPA. These beers have started slowly, but their momentum continues to build. We believe that we are well positioned to meet the longer term challenges of this competitive environment, through the quality of our beers, our innovation capability and our sales execution strength, coupled with our strong financial position that enables us to invest in growing our brands.”

The stock is down 8% in the after-hours session.

Comments »

$GOOGL, $MSFT, $SBUX Sharply Lower on Earnings Miss

Alphabet is diving lower by 6% in the aftet-hours on an earnings shortfall, on both the top and bottom line.

Q1 $7.50 vs $7.96 Capital IQ Consensus Estimate; revs $20.26 bln vs $20.38 bln Capital IQ Consensus Estimate

MSFT is lower by 4% on an earnings miss too.

Microsoft prelim Q3 $0.62 vs $0.64 Capital IQ Consensus Estimate; revs $22.08 bln vs $22.11 bln Capital IQ Consensus Estimate

To top off the trifecta, SBUX is down 3.5% on a revenue shortfall.

Starbucks prelim Q2 $0.39 vs $0.39 Capital IQ Consensus Estimate; revs $4.99 bln vs $5.03 bln Capital IQ Consensus Estimate

All three of these stocks were priced to perfection. It’s not a surprise to see these stocks trade down on any sign of weakness. Let’s see if the conference calls can firm up the price action.

NOTE: Visa missed as well and is slightly lower in after-hours. The company cited material weakness in emerging markets.

Comments »

Western Civilization is the Enemy at Stanford University

When you spend 50k per annum to educate a child, one would expect the institution that is receiving such monies to have the common courtesy to explain to their students the virtues of western society and why we’ve thrived above all over the past two thousand years.

A petition was set out to reinstall Western Society courses and Stanford and it was vilified to a degree that would make any hard-nosed dictator or fascist throughout history beam with pride.

I am sure there are several of you who will support the insanity by the illiberal left at Stanford, who, if given to their own biases, would have their heads cut off by the very people they endeavor to empower. Nothing about the current fringe element of the left is liberal. It’s the exact opposite. These people are intolerant, snap-chatting, morons, who scream and yell all day long about the evils of western society, while at the same time ignore the abhorrent behavior and lack of rights by inferior societies abroad. They ignore the fact that women are treated less than dogs in these societies and instead point towards wage disparities and other gender gaps that need fixing here. While western societies aren’t perfect and have many flaws, they are, by far, superior in all aspects to eastern societies– who are intolerant, bigoted and racist like you would not believe.

Comments »

Moody’s: Angels Fall at the Fastest Pace Since Financial Crisis

We’re reading a lot of headlines these days about ‘the first time this has happened since 2008’, yet markets are needling all time highs. In a report out by Moody’s, analyzing the credit downgrades of investment grade paper, the firm cites an alarming number of high quality paper being downgraded. The rate of decline from which companies lost investment grade status had, hitherto, not been seen since the dark days of 2008.

Moody’s is anticipating a further denigration of credit to continue in the not-so-distant future.

Last quarter, a total of 34 companies moved into that so-called crossover zone, for a total of 72 as of March 31. Of those, 59 are potential fallen angels (rated Baa3 on review for downgrade or with a negative outlook) compared with only 13 potential “rising stars” (Ba1 on review for upgrade or with a positive outlook).

Listed among the potential fallen angels are Barrick Gold Corp., Noble Energy Inc. and Ambev SA, the only Brazilian issuer that retains an investment-grade rating, according to Moody’s. Lear Corp. is among the potential rising stars.

Total debt for those potential fallen angels was $265 billion as of March 31, with non-U.S. issuers representing 80 percent of the total, Moody’s said. That’s up from $234 billion at the close of 2015.

None of this can take away from the profits enjoyed by market participants over the past two months. However, and most importantly, it’s paramount that you remember recent history and how a small crisis can easily bubble over into something much larger.

After starting 2008 with a 6% decline, markets rallied, in a ferocious manner, up until June of that year before succumbing to a selling frenzy that will be remembered forever, as a thing of legend. The odds of predicting another crisis to the exact month or week is extremely low. Nonetheless, we are seeing a repetition of warning signs, almost like a carbon copy from 2008, that demands attention. Otherwise, we’re nothing more than a class of morons–unable to learn from one’s history.

Comments »