iBankCoin
Home / 2016 (page 220)

Yearly Archives: 2016

Bass: Hong Kong Real Estate Collapse Worse Than 1997

For those of you who were either too drunk or stupid in 1997 to understand what happened to the Hong Kong real estate market in 1997, just know that it ravaged the economy and led to a 70% drop in prices over a 6 year period. It wasn’t until G. Bush II sold out America to foreign interests, buoying China to first world status, that the Hong Kong market was able to enjoy a rebound and eventual bubble.

Kyle Bass, from Hayman Capital, said during today’s SALT conference circle jerk of industry assholes that Hong Kong was going to face a worse fate than 1997. Perhaps 70% is too light for Kyle. Maybe he’s looking for a 100% drop in re prices?

“Hong Kong’s in a worse position than it was in prior to the ’97 crisis today,” Bass said at the SkyBridge Alternatives Conference in Las Vegas on Wednesday. He said credit in Asian emerging markets has grown “recklessly,” citing Malaysia and Thailand.

“China may be able to not tell the truth about specific output levels, or GDP figures — they might be able to fudge those numbers for a while,” Bass said at Wednesday’s conference. “But their trading partners kind of tell the truth, and you’re already seeing what’s happening in their primary trading partners.”

The Chinese credit system, according to Bass, is “one of the biggest macro imbalances the world has ever seen.” The fund manager said China is already experiencing a “hard landing as we speak.” He said he isn’t a “permanent bear” on China, instead describing himself as a pragmatist.

Bass, who’s widely known for his hardcore bearish views on Japan, and other places in the orient, was especially morgue-like in his demeanor today, saying ‘I feel like we’re in March/April 2007 in terms of equity and credit markets.’

Time will tell.

Comments »

Restaurant Stocks Were Rocked Today, as America Thins Out

After Wendy’s warned and Macy’s spelled doom for the retail sector, anything related to discretionary spending sold off hard. Truth be told, restaurant stocks aren’t really discretionary anymore, as Americans give up the avocation of home cooking in favor of microwavable sandwiches from SBUX.

In my view, any significant sell off in restaurant stocks is a buying opp. Amongst the best chains who do not poison their patrons with fecal matter are WING, SHAK, DNKN, SBUX, ZOES, DPZ and PNRA. I refuse to include MCD on moral grounds.

Over the past three months, the best performers in the space were ARCO, KKD, ZOES, RICK, QSR, PBPB, BOJA, PZZA and YUM.

Notice how all of the shit eateries are outperforming? I view this as a revolt away from health-conscious eateries, thanks to the CMG scare. However, my view is that this is more of a Wall Street rebellion, by money managing retards, than Main Street patrons. It’s not like people are heading out and asking for ‘moar GMOs’ in their sandwiches. Additionally, the nation is adopting healthier habits, not deleterious ones. Therefore, the spread between quality restaurants and beakless chickens is at recent highs–offering an opportunity for patient, long term, investors of American gluttony.

Here are today’s losers in the space, courtesy of Exodus.

eat

Comments »

Pershing Square’s Q1 2016 Letter to Investors, The Bill Ackman 50th Birthday Edition

I guess he’s been doing this for a while–issuing investor letters on his birthday. By the looks of VRX today, I’m guessing he’d rather go for a swim, somewhere nice, than deal with clients today.

Nevertheless, it is my duty, as an ardent believer in Montauk Bill’s financial prowess, to report on such ongoings. Truth be told, I am only hard on Bill because he makes it easy. The whole ‘I’m gonna fix JCP fiasco’ was the beginning of my ire. It was solidified when he traded on insider info, via VRX’s bid for AGN, and got away with it.

After that, Bill clown-raped himself with the HLF short and subsequent torching of several billions of dollars in VRX. Alas, we are here, with Le Fly critiquing the Q1 Pershing Square letter to shareholders, on Bill’s 50th birthday.

Net of fees, Pershing is flat since 2012, off by 18% this year.
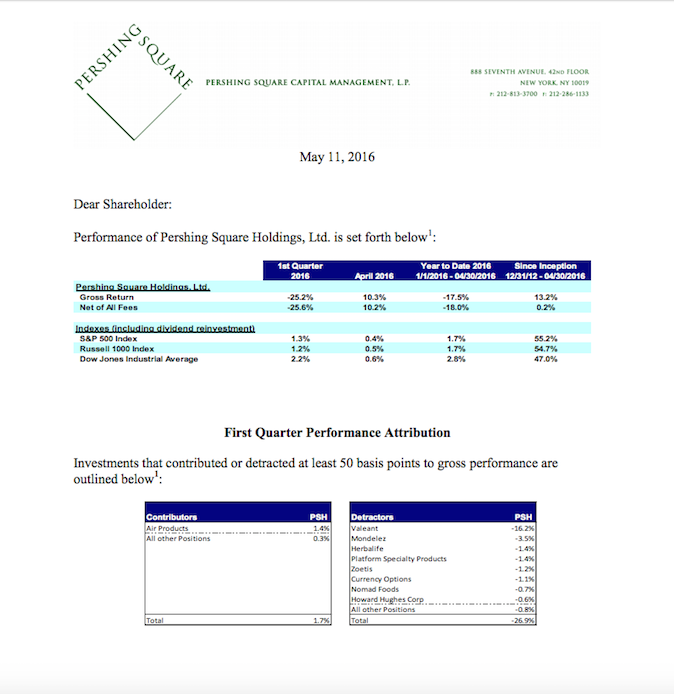
pershing

Bill’s take on VRX

Valeant (VRX)
We have made material progress at Valeant since our last communication. Shortly after Steve
Fraidin and I joined the board in March, the company launched a search process for a new CEO.
On May 2nd, Joe Papa, formerly the Chairman and CEO of Perrigo (NYSE: PRGO), joined
Valeant as its Chairman and CEO. We believe that Joe is an ideal choice for Valeant as he has
extensive senior leadership experience in all aspects of the pharmaceutical industry, a strong
reputation for integrity, and an excellent track record at Perrigo as reflected by the company’s
24% compounded annual return to shareholders during his tenure. Joe is passionate about the
opportunity for value creation at Valeant, and we are excited to have him on board.

Valeant filed its 10-K as expected on April 29th, eliminating any potential default under its
existing credit agreements. Other than the previously reported $58 million revenue restatement
from Q4 2014, there were no other restatements required in the company’s audited statements.
As this was likely one of the most carefully audited financial statements ever, this should serve
to comfort investors as to the integrity of the company’s financial statements.

Valeant will have a largely new board slate for the upcoming annual meeting in June. Two of
the company’s legacy directors will remain on the board – Bob Power and Bob Ingram, the
company’s former Chairman. Over the past six weeks, the current board led by Bob Ingram has
worked very effectively despite difficult circumstances. We are extremely appreciative of the
board’s hard work and commitment to the company, and for the two Bobs’ willingness to
continue to serve going forward.

The new board of Valeant will be comprised of CEO Joe Papa, Bob Ingram and Bob Power, the
four directors who joined in March – Tom Ross, Fred Eshelman, Steve Fraidin and myself – Rob
Hale, a representative of ValueAct, and three new directors who will join at the annual meeting.
The new board will have ample shareholder representation, substantial executive level
pharmaceutical industry expertise, and accounting expertise, as well as a practicing
dermatologist.

There is much work to do at Valeant, which, among other issues, includes restoring the
dermatology business to growth while working out transition issues with its new Walgreens
distribution arrangement, accelerating the growth of Salix, Valeant’s gastrointestinal business,
and reducing the company’s debt through free cash flow generation and the potential sale of noncore
assets. We believe that Valeant has some of the best and most durable assets in the
pharmaceutical industry, which do not require aggressive pricing in order to generate growth and
substantial free cash flow. It will take time for Valeant to regain its stakeholders’ trust. We
believe that this will occur over time as the company delivers several new quarters of results and
continues to fulfill its commitments to shareholders, patients, doctors, and the community at
large. Over time under Joe’s leadership, we expect the market to rerate Valeant to a substantially
higher valuation reflective of its underlying business.
ackman

Yeah, happy bday Bill.

Comments »

Poof! Yesterday’s Gains are Gone

Markets reeled today. After they reeled, they reeled some more. There are many reasons to be worried about your stock portfolio, which is most likely filled with complete shit. The Japanese Yen continues to fireball higher, in spite of NIRP. Because of NIRP, european banks are beguiled by losses and they’re mounting.

Here in the states, our consumer, which was once the lifeforce of the market, is missing in action. Every once in a while he emerges out from the crevasse to rear his gluttonous head. Judging by recent earnings reports, he’a dead.

Stocks raced lower today, shedding 200. The Nasdaq fuckery is real. Shares of AAPL are down 26% over the past year. There are hardly worthwhile endeavors in the tech space anymore.

As the tumult and chaos reign over the land, a quiet soliloquy, almost of an ingenious musical nature, ebbs and flows without pause. It floats over the flooded landscape, filled with the species of this world, so that when the pain recedes, we can start this world again–but without the fuckery and the chicanery.

The ark floats.

Comments »

The Mall is Dead

We discussed this topic in detail yesterday and many of you had some great comments, in regards to where the discretionary spending has gone.

My favorite is yoga pants, clearly an albatross in the retail space, especially for makers of jeans.

My post was especially prescient, as the balance of the retail sector is being annihilated today, off the faces of stark warnings out of FOSL and M.

BEHOLD the carnage.

image

image

image

image

image

image

image

I was thinking about where my spending has gone up over the past decade, in an effort to try to justify this dislocation.

Here are some brief personal spending notes.

-everyone in family now owns an iPhone. Monthly cost $350.
-health insurance has risen from $1,200 to $1,700 per mo
-organic food costs have risen. Monthly grocery bill is around $3k.
-I collect stuff now (books, newspapers, vinyl records). Monthly expense of around $250.
-cable bill has risen, presently around $300 per mo
-Netflix: $7.99
-iTunes expense for family of 5: $75 per mo
-cars are more expensive. Monthly cost around $1,500
-son is in college. Annual cost, after scholarships, is around $5k.
-I frequent SBUX more. Monthly expense is around $250.
-Utilities are more expensive.
-Primary place to buy gifts and random stuff is now Amazon.

Truth be told, my income is higher than it was 10 years ago and I definitely spend less at the mall. I wouldn’t consider myself a ‘dead consumer’, but one whose spending habits have migrated, evolved, and have changed to custom fit my decadent lifestyle.

The mall is dead. There’s even a website dedicated to it.

Comments »

Boeing, Lockheed Martin Attend Vietnamese Arms Symposium

Relax Vets, it’s just business.

Next week President Obama will visit Vietnam. Shortly thereafter, he will likely lift the arms embargo on Vietnam, because that’s what Barry does.

Then, Boeing, Lockheed and maybe Raytheon will ink arms contract with our former mortal enemy, amounting to billions of dollars.

This reminds me of Iron Man the movie, when Stark’s partner was inking fucked up arms deals in secrecy, only in real life.

Vietnam has been in talks with Western and U.S. arms manufacturers for several years now to boost its fleets of fighter jets, helicopters and maritime patrol aircraft, although Russia, its traditional supplier, maintains a dominant position.

Industry sources say Hanoi is keen on U.S. weapons yet wary of the threat of a future embargo even if the current one ends. The countries do have a common concern in China, however, whose assertiveness in the South China Sea has alarmed Washington.
Obama is due to start his Vietnam visit on May 22, the first by a U.S. president in a decade, underlining the rapidly warming relationship between the countries at a time of testy ties and growing mistrust between Hanoi and Beijing, which have competing claims to the Paracel and Spratly islands.

MODERNIZATION NEEDS

A spokesman for Lockheed Martin confirmed the company was attending the Hanoi event.

Boeing is also attending, although the firm made it clear it was not in contravention of the embargo.

“I would like to point out that any defense-related sales to Vietnam will follow development of U.S. government policy on Vietnam,” a spokesman said.

“We believe Boeing has capabilities in mobility and intelligence surveillance and reconnaissance platforms that may meet Vietnam’s modernization needs.”

They need modernization.

The fucked up communist nation of Vietnam, where untold human rights atrocities have taken place over the decades since the Vietnam War, has increased military spending to the tune of 700% in recent years, coinciding with their emergence onto the world stage as preferred slave factory locale for scores of western tech and textile corporations.

Comments »

Fed’s Fisher Offers Scathing Review of Fed’s Policies, Worries About Insurance Industry

In a scathing indictment of the Fed’s zero interest rate policy, Dallas Fed President, Richard Fisher said the Fed’s policies are hammering bank margins and pose a significant risk to the insurance industry, who rely upon treasuries to finance their chicanery.

Shockingly candid.

The companies Fisher said he’s most worried about are insurers.
“Insurance companies, particularly life companies, are like noble oxen. They pull the cart forward steadily forever and ever and ever. They’re living in a 1 percent world in this country, but they’re pulling a 3-to-6 percent liability cart. It doesn’t square,” he told CNBC’s “Squawk Box.”
Low interest rates are a major risk for insurers because the income they derive from investments — mostly in safe assets like Treasurys — may be insufficient to fund payouts to customers in low-rate environments.

Fisher said Fed policymakers did not anticipate the scope of easy money’s impact on the financial sector.

“Bank’s interest margins are being hammered. Money-market funds are trying to squeeze out a return. This is the kind of stuff, to be honest, sitting at the table, we did not foresee at the FOMC,” he said, referring to the Federal Open Market Committee.

Fisher is a hawk and wants the Fed to hike and then hike some more.

Comments »

KKR to Get Liquid On $HCA, Using Shareholder Money as a Means

KKR managed to convince management at HCA to buy back $800 million of stock from them, in one fell swoop, for the extreme discount of 1%.

08:35 | HCA | (80.93)
HCA to repurchase 9,360,958 shares of its common stock beneficially owned by affiliates of Kohlberg Kravis Roberts & Co. at $80.12/share

The Share Repurchase was made pursuant to the Company’s existing $3.0 billion repurchase program adopted by the Company’s board of directors in October 2015. After giving effect to the Share Repurchase, a total of $2.09 billion of share repurchases will have been effectuated under the program.

Michael Michelson, a general partner at KKR, in addition to being on the HCA board, without question, agrees with this move. Ever since Hercules was created, an entity that combined several PE firms, including KKR and Bain Capital, to acquire HCA and then bring them public again in 2011, they’ve been using shareholder money at HCA to liquidate their position.

Considering the fact that the stock has nearly tripled since then, thus far, the buybacks have been a great investment for the company. Then again, I’m not sure if share buybacks would’ve been the best use of capital over the given time frame, a period of great profit for hospital operators.

Nevertheless, the chrony capitalism continues at HCA, a denizen of Senator Bill Frist.

Comments »

Macy’s Warns, Cites ‘Continued Consumer Weakness’, Share Buybacks to Continue

The good news is that Macy’s is firing thousands of meaningless employees, fodder, which will save $400 million in the intermediate term. The bad news is the company has spent upwards of $7 billion on share buybacks since 2011, with another $2 billion remaining, and have lost money on almost every single transaction since.

Oh, and by the way, business sucks…because the mall is dead.

“We are seeing continued weakness in consumer spending levels for apparel and related categories. In particular, our sales trend relative to expectations meaningfully slowed beginning in mid-March, and first quarter results are below our original outlook,” Terry J. Lundgren, Macy’s chairman and chief executive officer, said in a statement. “Headwinds also are coming from a second consecutive year of double-digit spending reductions by international visitors in major tourist markets where Macy’s and Bloomingdale’s are key destinations, as well as a slowdown in some center core categories — further intensifying the challenges associated with growing topline sales revenue.”

08:01 | M
Macy’s sees 2016 EPS of $3.15-3.40 vs $3.80-3.90 prior guidance and $3.78 consensus and top-line sales expected to remain below initial expectations

image

Oh, don’t worry about the dividend. In spite of the fact that business is undeniably impaired, along with pursuing a share buyback frenzy, the company has once again hiked the dividend.

The business of Macy’s is not to sell goods to the consumer, after all. It is to sell their stock to the investor.

Comments »