iBankCoin
Home / 2016 (page 210)

Yearly Archives: 2016

New Home Sales Crush Estimates for April, Coming in at 619,000

These are fantastic new home sales numbers, at 619k for the month of April, compared to estimates of 520k.

This, coupled with the great earnings out of TOL this morning , is providing extreme buoyancy to the homebuilder sector.

The early leaders are TOL, KBH, TPH and HOV.

For the year, however, this has been a bedraggled sector, down more than 9%.

These were the best sales figures for a month since 2008.

Comments »

Market Soars, As Markets Decouple from Oil

Financials are up 1.2%. Oil stocks are down. Gold and silver are getting fucking hammered. Tech and healthcare are higher by 1%. Home builders are higher by 1.4%. And, lastly, semis are higher by 1.2%.

I hate to be that guy defecating on the parade, but breadth stands at an abysmal 45%.

Should I even talk about the greet number of awesome and amazing stocks that aren’t rallying with the broader markets, or should I just wait until the indices soften and then say “Ah-ha, I told you so?!”


Comments »

The Bank of Japan Has Created Spender Friendly ETFs for Their QE Program

The Bank of Japan is sick and tired of buying ETFs that have asshole companies, who don’t like to spendthrift their money on stuff, anymore. To remedy this problem, they’re created their own ETFs, weighted with good, wholesome, companies who spend lots of money on capex and wages.

The new custom-made ETFs track the following indexes: the MSCI Japan Human and Physical Investment Index, the JPX/S&P Capex & Human Capital Index, and the Nomura Enterprise Value Allocation Index.

This is truly unbelievable, a perversion of capitalism if I’ve ever seen it. The BOJ will never be able to exit their ETF investments. They already own titanic sized positions in their publicly traded stocks, via their ETF buying programs. In many cases, they own upwards of 60% of all shares in these baskets. It truly is an untenable situation being made progressively worse by the explicit and wanton manipulation of the Japanese stock market and economy.

Comments »

Snapchat Raises New Capital at 70x Sales

Snapchat is a cool app. All of the brainless kids love it. Therefore, venture capitalists are free to affix any valuation they feel is appropriate to it. After all, it’s the next big thing.

So, they raised new money at a $22 billion valuation. According to re/code, Snapshit will do $300-350 million in revenues for 2016, placing their price to sales ratio just about 70x. To put this into perspective, Facebook is trading about 20x and at the highest peak of the social media bubble, Twitter and others might’ve touched down at around 30x. But, for the most part, 20x sales is super bubble territory.

Because the first social media bubble worked out so well, investors figured Snapshit could be worth whatever they wanted it to be worth. For now, 70x sales will suffice.

This new financing, we understand, is a follow-on to the $175 million Series F round led by Fidelity. Snapchat was said to be valued at $16 billion in that round, flat on the year before. However, filings from earlier this month and embedded below, uncovered for us by market analysts VC Experts, show that the Series F was expanded.

Based on a share price of $30.72 per share — which VC Experts tells us was the value disclosed in an earlier Fidelity Fund filing related to its Snapchat investment — and assuming all of the authorized shares are issued, the more recent valuation could be as high as $22.7 billion. Authorized shares do not always all convert to issued shares, but this gives us a range that fits in with what we’ve heard about the $20 billion valuation.

Expanding the Series F with a Series FP, as it’s described in the document below, would also fit in with a description we’ve heard more than once about Snapchat’s fundraising: The startup is “always raising” on a “rolling” basis, partly because investors are so interested.

“They get offers all the time,” one investor close to the company said. “And once you start to grow on this path, many people come to give you money. You don’t know how to value the company, so the best way to do that is to do some kind of rolling funding. When you have a hot company and many people are approaching you, you do a market of discovery.”

Besides Fidelity, other existing investors in the company include Alibaba, which led its Series E; Benchmark (Series A lead); Coatue Management (Series C lead); General Catalyst; IVP (Series B lead); Saudi investment group Kingdom Holding Company; KPCB (Series B lead); Lightspeed (Snapchat’s earliest and most constant investor); SV Angel; WeChat owner Tencent and Yahoo. We hear that many existing investors are looking to participate in this new round, including Spark Capital

Ooh, the Saudi Prince from Kingdom Holdings is an investor, alongside a sundry of Chinese investors, such as Tencent and Alibaba. What can go wrong?

Comments »

Best Buy Beats Estimates, Warns on Bottom Line

Anyone need a good phonograph…from China. If so, BBY is your place. Ever notice how utterly lost this company is, especially when getting lost inside of their stores of antiquated electronics?

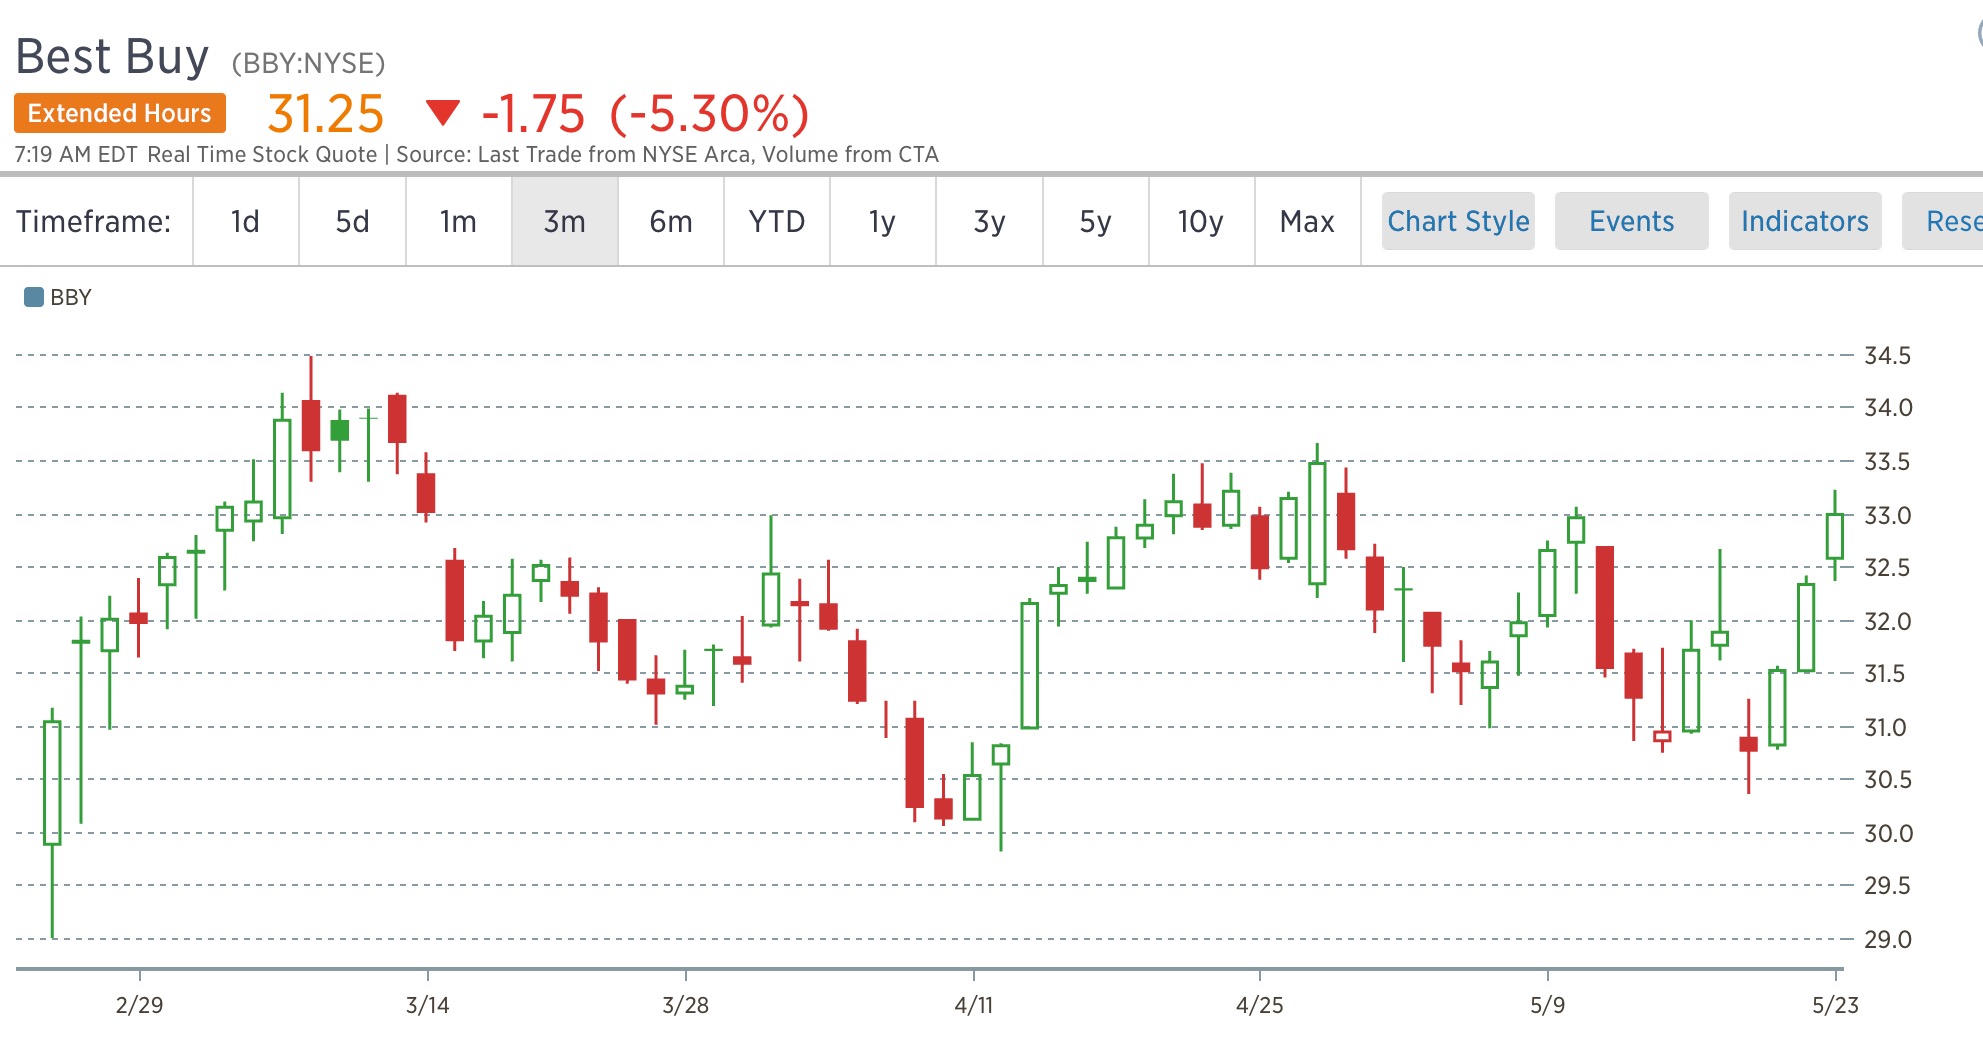
Best Buy just reported decent numbers, but warned for their bottom line going forward.

The company reported solid comps for appliances and a 23% spike in online sales. However, mobile phones, services and computers were abysmal. Most importantly, the companies main source of earnings improvement lies in their share repurchases. They’re blaming Japan’s earthquake for their earnings warning, but slightly offset by their absurd buybacks.
image

07:11 | BBY | (33.00)
Best Buy beats by $0.09, beats on revs; guides Q2 EPS below consensus, revs above consensus; reaffirms FY17 guidance; CFO Sharon McCollam to step down; Strategic Growth Officer Corie Barry named new CFO

Reports Q1 (Apr) earnings of $0.44 per share, excluding non-recurring items, $0.09 better than the Capital IQ Consensus of $0.35; revenues fell 1.3% year/year to $8.44 bln vs the $8.3 bln Capital IQ Consensus.

Comparable sales were essentially flat (-0.1%) vs. (2)-(1%) guidance against a backdrop where the NPD-reported categories were down 1.9%.

From a merchandising perspective, comparable sales growth in health & wearables, home theater, major appliances and computing was offset by declines in mobile phones, tablets and gaming. As expected, television sales related to the shift of the Super Bowl into Q1 FY17 positively impacted the Domestic segment by ~70 basis points. The company also saw continued revenue declines in services due to investments in services pricing and the reduction of frequency of claims on extended warranties which has reduced repair revenue.

Consumer electronics comps +5.6%; computing and phones -3.5%; entertainment -11.6%; appliances +14.3%; services -10.7%.
Domestic online revenue of $832 million increased 23.9% on a comparable basis primarily due to higher conversion rates and increased traffic. As a percentage of total Domestic revenue, online revenue increased 210 basis points to 10.6% versus 8.5% last year.

Co issues guidance for Q2, sees EPS of $0.38-0.42, excluding non-recurring items, vs. $0.50 Capital IQ Consensus Estimate; sees Q2 revs of $8.35-8.45 bln vs. $8.31 bln Capital IQ Consensus Estimate.

“In line with our original expectations, there are two factors impacting our year-over-year non-GAAP EPS guidance for the second quarter. First, we are expecting an approximate $0.03 net negative impact from the lapping of the periodic profit sharing benefit from our services plan portfolio that we received in the second quarter of last year. Second, we are expecting an approximate $0.06 negative impact from the carryover of last September’s services pricing investment. In addition, in digital imaging, we are now expecting an approximate $0.03 to $0.04 negative impact due to the April 2016 earthquake in Japan, which is impacting inventory availability in this high-margin category. Combined, these are putting $0.12 to $0.13 of pressure on Q2 FY17, which will be partially offset by an approximate $0.04 benefit from share repurchases.”

“We are reaffirming our previously provided full year financial outlook which includes ~flat revenue and non-GAAP operating income, with non-GAAP EPS growth [consensus +3.2%] driven by share repurchases. Although we are reporting better-than-expected results today, we are not raising our full year outlook as the first quarter represents less than 15% of full year earnings and at this stage we have no new material information as it relates to product launches throughout the year.”

Sharon McCollam, the company’s chief administrative and chief financial officer, will be stepping down on June 14, 2016. McCollam will remain with the company in an advisory capacity until the end of the fiscal year, January 28, 2017, to ensure a seamless transition. Corie Barry, a 16-year veteran of Best Buy and its current chief strategic growth officer, will become the company’s chief financial officer at the conclusion of Best Buy’s annual shareholder meeting, being held on June 14.

In lieu of these numbers, Citi downgraded BBY to neutral.

Comments »

Iron Ore Falls to March Lows

It truly is collapsing, but I didn’t want to give any of you heart attacks before tomorrow’s trade. It might prevent some of you from liquidating your portfolios and causing an even greater decline.

Iron ore represents China in all of its grave depravity. Now we have the price dropping to the lowest point since March the 3rd, at the same time copper keeps dropping too. There is a discernible cause for panic amongst China bulls. By extension, all of you should panic too.

“There’s little doubt that the iron ore price will sink below $50 a ton as seaborne supply is rising while the Chinese steel mills will reduce purchases,” Ren Jiaojiao, an analyst at Maike Futures Co., said by phone from Xi’an on Tuesday. Inventories at China’s ports — which topped 100 million tons last week — may increase further, according to Ren.

“The run-up in April was fueled partly by purchases from steel mills ramping up production to capture the exceptionally-high profit margin,” said Ren. But that margin is now “quickly contracting, so mills are adjusting to the new situation by depleting their raw material inventories first. They will also adopt a hand-to-mouth strategy in purchases later because of anticipation of higher supply at the ports.”

Ore with 62 percent content sank 6.7 percent to $51.22 a dry metric ton on Monday, the lowest since March 3, according to Metal Bulletin Ltd. After surging 23 percent last month as China’s ill-fated frenzy gathered pace, the price has tumbled by the same amount so far in May. Futures in Dalian fell as much as 2.6 percent on Tuesday, while the SGX AsiaClear contract was little changed.

Citigroup Inc. said in a report on Tuesday it remained bearish on iron ore, forecasting persistent oversupply on rising output from the top miners as well as Gina Rinehart’s Roy Hill project. At the same time, weaker steel prices will encourage mills to restrain output and keep ore holdings low, it said.

“Oversupply should extend into the rest of 2016,” Citigroup said, predicting that prices will average $47 a ton this year. “Weaker steel prices should incentivize mills to decrease utilization rates and maintain low iron ore inventories, putting pressures on Chinese iron ore imports.

Talking about iron ore and how doom is beckoning gets boring sfter a while. Not before long, the cat calls shrieking from this bloggery must be backed up with actual calamity. Don’t worry lads, recession is an assured outcome. Give it a chance. You might like it.

Comments »

Danger: The Yield Curve is Flattening

When I took my 25% position in TLT, back in late December, I said I’d hold it until the yield curve inverted. The last time the yield curve inverted was back in 2007, right before the world almost ended. For those young to the world of investing, the yield curve is the spread between the 2 and 10 year duration treasuries. When the yields of the 2s surpass the 10s, doom is right around the bend.

The inversion of the yield curve has accurately predicted every recession over the past 50 years. Therefore, and it goes without saying, it’s notable when the curve begins to flatten.

As of now, the spread is at its narrowest since 2007, just 93bps.

When the Fed hikes rates, I predict the long duration yields will fall, and the shorter term will rise. This trend will continue until people finally figure out the Fed has purposely wrecked the economy, at which point we will already be in a recession. The yield curve will be inverted and “The Fly” will win again, via his large TLT position.

This is prophecy at its highest and finest form. Failure to acknowledge future facts is no different from being in possession of a time machine and not winning the lottery at some point in your travels.

Comments »

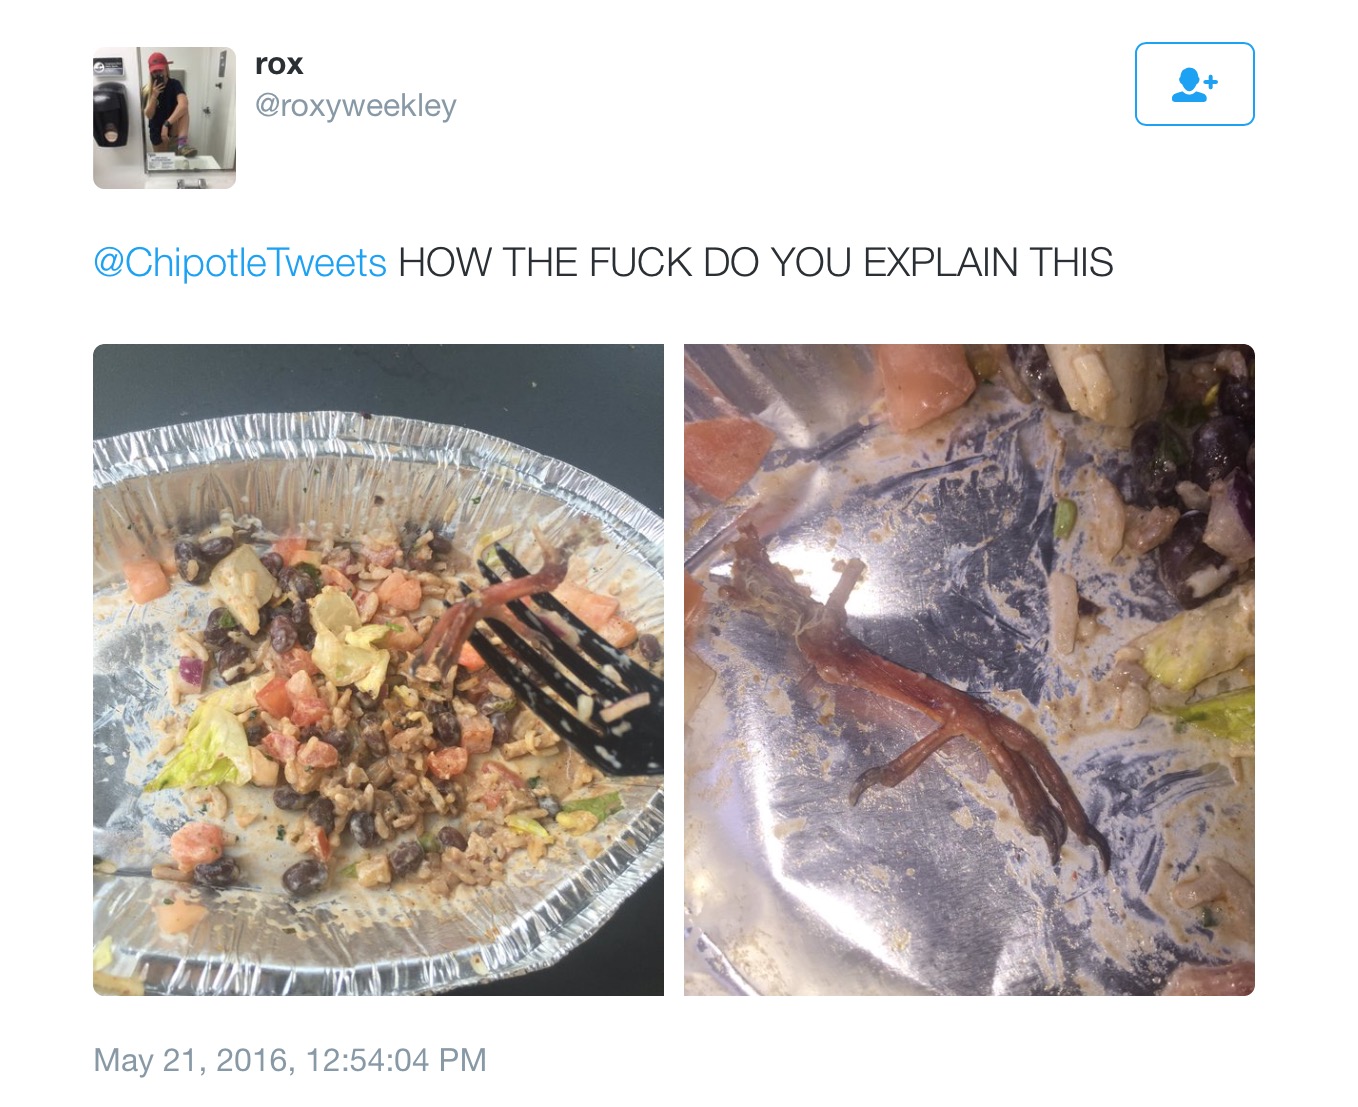
Woman Goes Ape on Twitter After Finding Chicken Foot in Chipotle Burrito Bowl

This is the sort of press Chipotle could’ve swept under the rug, pre ecoli era. And this is exactly why CMG is uninvestable, since every food quality story has the potential to cause a 30% drawdown in sales.

People are truly delusional for owning CMG, thinking the worst is behind the company.

Earlier today some random woman with a few followers posted a picture on Twitter of her all but devoured chicken burrito bowl. At the bottom of her bowl was a treat of sorts. If you look at the picture you can see a nice chicken foot, which could be used in a sundry of devil worshipping, occult, black magic spells.

image

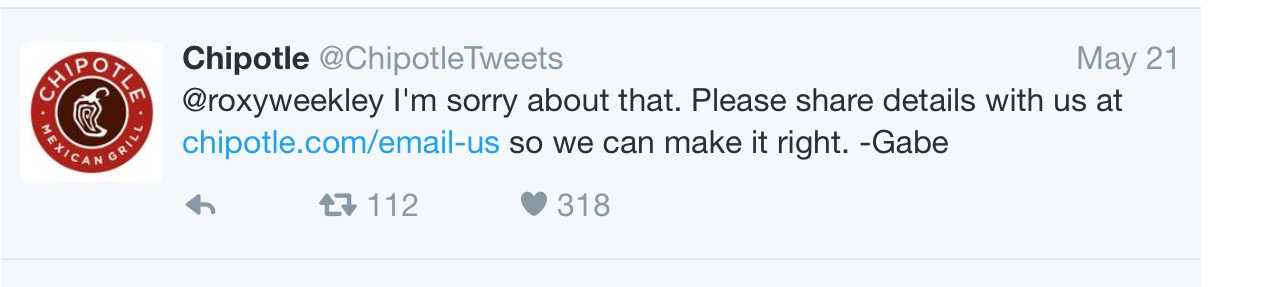
“Gabe” from the CMG Twitter customer service department is on the case.


image

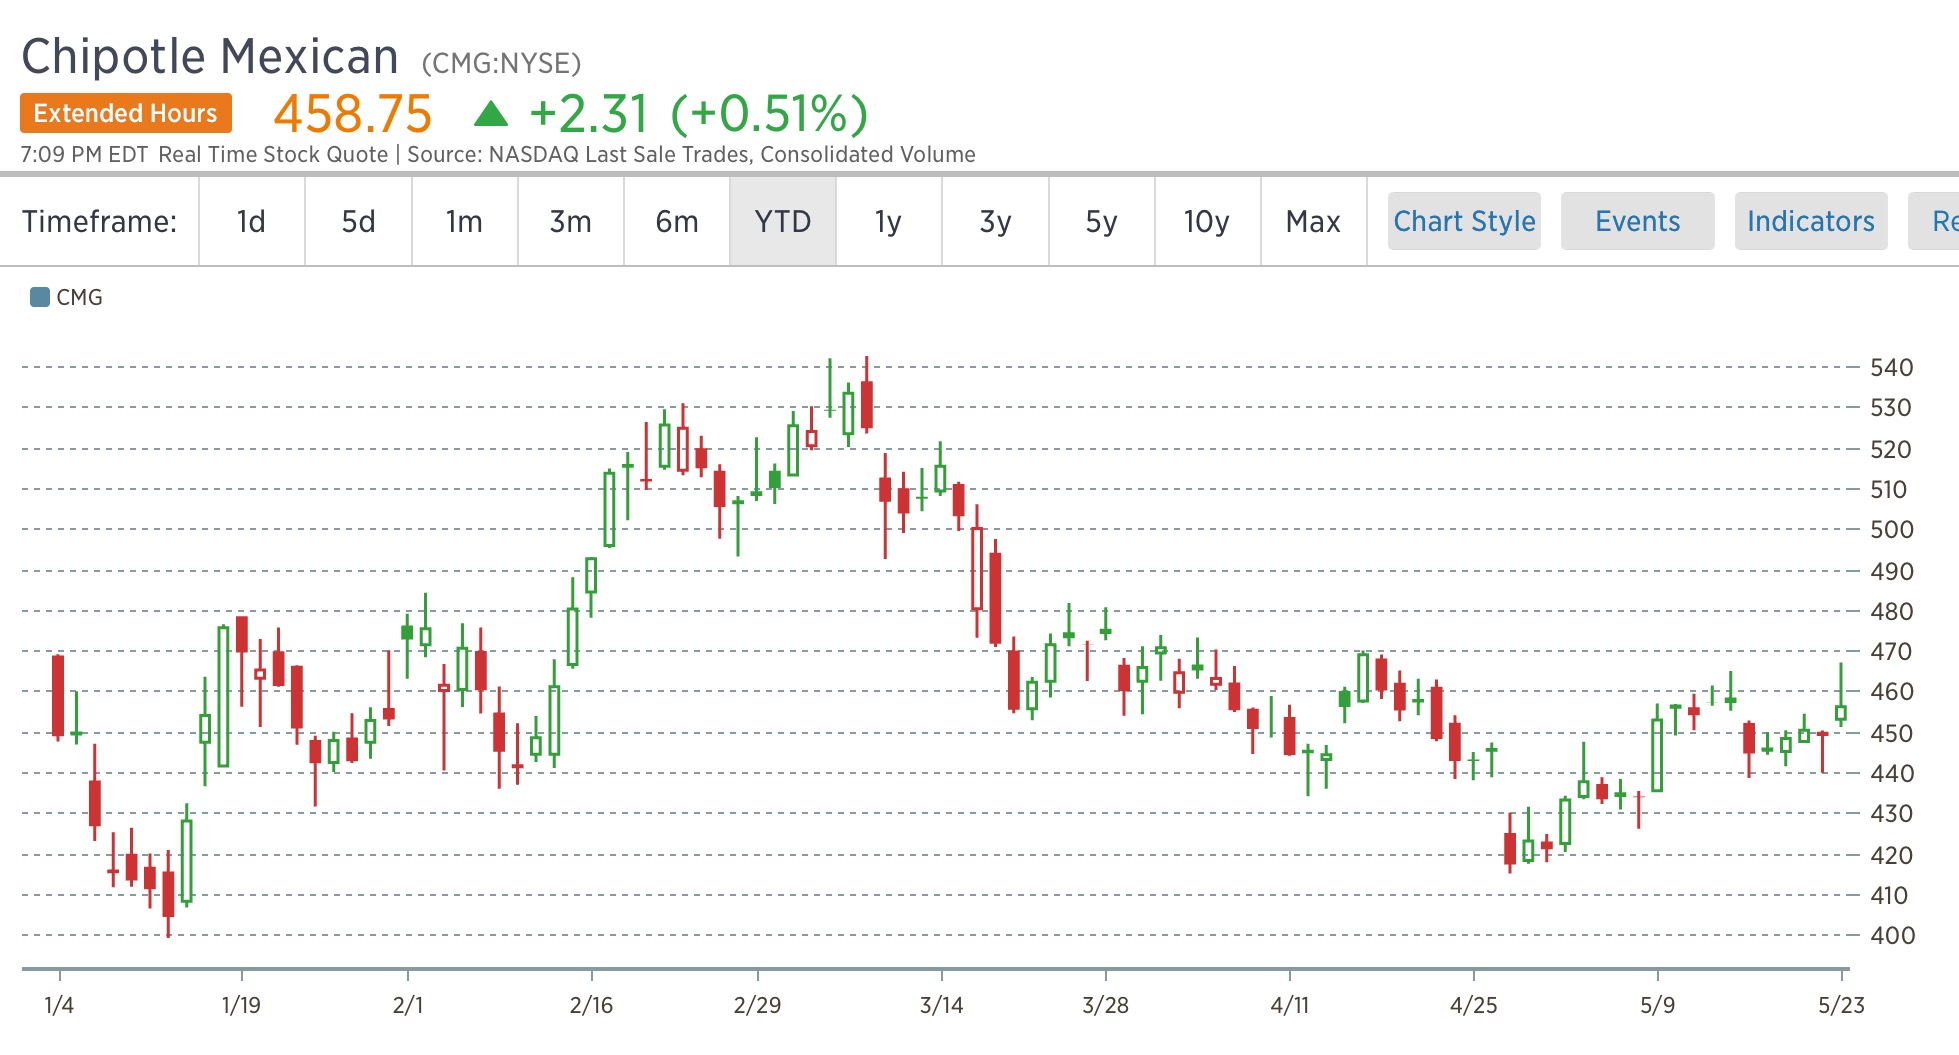
Shares have rebounded lately, on the belief that the company doesn’t serve poison, or chicken feet at the bottom of their burrito bowls.

image

Comments »

Chesapeake Screws Shareholders Again, Swaps More Debt for Equity

In yet another dilutive debt/equity swap, the beleaguered oil and gas giant is running out of creative ways to service its debt. They’ve issued 10% of its equity over the past month, in an effort to get a better handle on their 9 billion debt hold.

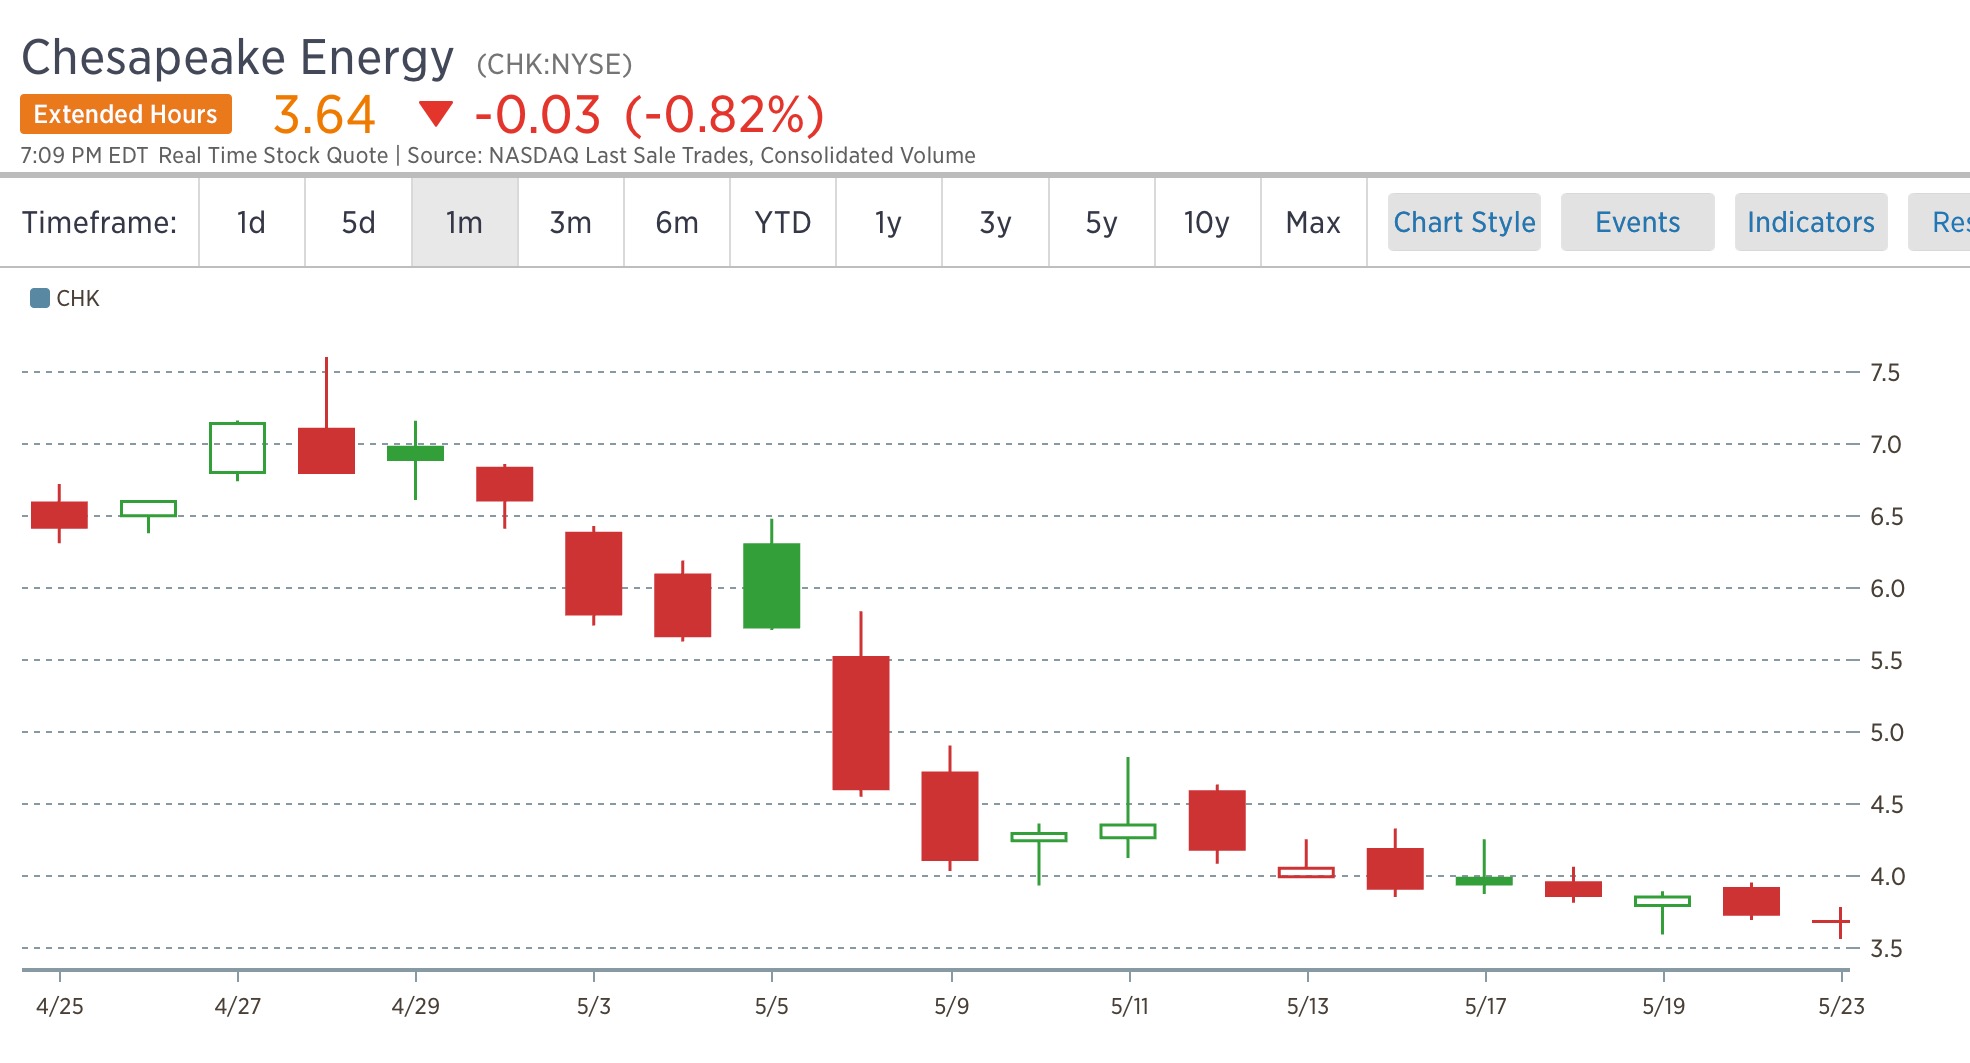
This, of course, comes at a great cost. Shares of CHK are down 44% over the past month.

image

The company, which has more than $9 billion in debt, said on Monday it issued or agreed to issue about 37.1 million shares between May 16 and May 23 in exchange for senior notes worth about $166 million. The notes are due in 2017, 2019, 2037 and 2038.

Chesapeake swapped $153 million of debt for about 4 percent of its equity earlier this month.

This is the main reason why I’d avoid playing the sector on the long side. Desperate people do desperate things.

Comments »

Fed’s Harker Foresees Two to Three Rate Hikes in 2016, Cites Inflation Risk as Main Concern

Fed’s Harker is out talking greasy tonight, talking up rate hikes and inflation, pointing to a robust American economy, in spite of the inconvenient facts on the ground that suggests otherwise. Moreover, he believes the Fed will hike 2 to 3 more times in 2016 (that’s in the next 6 month’s for you 2nd grade math gurus out there).

The craziness of Harker’s comments is that he said the Fed might have to use ‘aggressive policy actions’ to fend off runaway inflation, which has consistently remained under 2%, for years.

He said once crude stabilized and ‘reversed’, inflation would surely hit 2% and more, further validating his stance that the Fed should hike rates now, in order to get ahead of the curve. This, of course, countermands reality, in that crude has ‘stabilized’ and is higher by more than 50% from the February lows–yet inflation is non-existent.

I suppose Harker believes crude will trade to $100 again? Speculating on the price of crude has always been something the Fed eschewed, due to the gambling nature of it all.

Federal Reserve Bank of Philadelphia President Patrick Harker said that he could see two to three rate hikes in 2016 and that prices will return towards the central bank’s inflation target over the medium term.

“Although I cannot give you a definitive path for how policy will evolve, I can easily see the possibility of two or three rate hikes over the remainder of the year,” Harker said, according to remarks prepared for delivery in Philadelphia on Monday.

Harker emphasized that the U.S. has continued to grow in spite of global headwinds and he called the labor market “extraordinarily dynamic.” His remarks follow several other speeches by Fed official emphasizing the possibility of an interest rate increase at their June 14-15 policy meeting in Washington.

“If the economy follows the path I expect it to follow, monetary policy will be overly accommodative by historical standards,” Harker said. “That will set in motion the possibility of another risk, which is accelerating inflation and the need for aggressive policy actions.”

On inflation, which has consistently undershot the Fed’s 2 percent goal, Harker argued that the “math is in our favor” as energy prices rebound and dollar strength abates.

“I believe that, once energy prices stabilize and start reversing, inflation will return to our 2 percent target by sometime next year,” he said.

All of what he said was complete and utter nonsense. I truly doubt he believed any of it. Moreover, the market doesn’t believe it, as the market is only forecasting a 30% chance the Fed will move in June and a 46% chance in July. Clearly, three rate hikes over the next 6 months isn’t priced in.

Comments »