Let’s see if this blog and my Twitter following has any correlation with the real world or not. My suspicion is that finance, naturally, attracts a more conservative brand of person. Most capitalists that I know aren’t too political. But they tend to lean towards whoever they believe will provide the best environment for sustained economic growth.
I am running a poll on Twitter, which will last a day, to see who people will vote for this Presidential election.
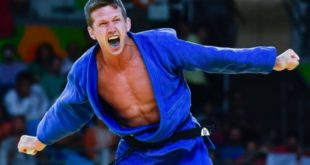
I feel like I’m living in the bizarro world. How the fuck does an Olympic judo medalist get robbed and beaten up by some random asshole on a beach in Brazil?
He’s a fucking blackbelt in judo, at he highest levels. He could’ve taken this guy and twisted him up in a pretzel and then snapped his neck like a dry twig.
Dirk van Tichelt won his first Olympic judo medal Monday.
Dirk Van Tichelt probably didn’t envision one of the greatest days of his life ending in the hospital. But that’s exactly where the Belgian judoka found himself Monday night hours after winning his first-ever Olympic medal.
Van Tichelt won bronze in the 73-kg judo competition on Monday. Naturally, he went off to Copacabana Beach that night to celebrate the achievement. And that’s where things went awry.
Van Tichelt was reportedly assaulted by a thief on the famous beach, and was struck in the face. He was taken to the hospital after the incident.
The thief, who was reportedly Brazilian, came away with a cellphone, but, crucially, not with a bronze medal.
These fucking people are so delusional, in their monarchy of terror, corruption and mental illness. Now all asset managers in America who manage just $1b can invest in their fucking asshole stocks, which is completely based on crude oil.
Or, maybe you can just buy USO and avoid having to support a regime that is the single biggest supporter of terrorism, which has infected the world with their brand of Islam that threatens the very fabric of the western world.
The regulations — which will cut the amount of assets foreigners must have under management to invest directly in the nation’s stocks to 3.75 billion riyals ($1 billion) from 18.75 billion riyals — will be enacted on Sept. 4, according to a statement from the Capital Market Authority on Wednesday. They will also allow individual foreign investors to own not more than 10 percent of shares outstanding in a single company, up from 5 percent.
The Riyadh-based regulator said in May the changes would take effect before the end of the first half of 2017.
Over the past year, the Saudi Tadawul is down 25.4%.
Yes, the headline was designed to be tongue in cheek and sarcastic. Last week, crude oil spiked on a bigger than expected draw in distillates. Today, for some odd reason, the same news is causing a sell off.
Crude oil inventories had a build of +1.06 mln (consensus called for a draw between -800K & -1.75 mln barrels)
Gasoline inventories had a draw of -2.81 mln (consensus called for a draw between -1.0 & -1.2 mln barrels)
Distillate inventories had a draw of -1.96 mln
Please don’t pay attention to the fact crude inventories are rising. We don’t want to recognize that news. As bull market circle jerkers, the narrative that we will spread amongst friends and enemies alike is one that speaks to a dwindling supply of crude oil at a time when demand is robust. We will ignore all of the earnings reports that announce record oil production and we will never discuss the levels of production emanating out of the Middle East.
WTI is down. Without question, it is a buying opportunity!
Okay, for some reason people don’t believe the Fed will hike rates any time soon today. Thanks to this belief, which is entirely logic based, commodities are getting a new bid, led by gold and silver–up 0.8% and 2.2% respectively.
The dollar is down 0.55% v the euro and bonds are trading higher.
Notice how whether the market is trying to price in a Fed hike or not stocks rally? That’s called a bull market. Good news is great and bad news is good. Nothing can go wrong. As such, we all dive into the markets, headlong, and prepare ourselves for fantastically gay gains. The only problem with a pornographic tape, such as this, is the presence of the canaille. You know, the asshole who doesn’t deserve to bank coin in the market–due to lack of talent and genetic ties to very old and prestigious American families? Yeah, those guys will soon get flushed out, like city trash down a storm drain after a healthy downpour.
Sure, at the moment, it’s very sunny and wonderful. The birds are chirping and the people are singing, whilst playing the harpsichord. But very soon the mood will turn to be dour and grim and all of the birds will be dead and the people will be maimed and carelessly tossed aside whilst wild gorillas stomp out the fucking harpsichords.
While the lot of you no comments having bloggers were asleep like babies counting sheep, Le Fly was out in the night, armed with a crowbar, busting into your blogs to rewrite your fucking titles. I’m sure you all went to great lengths to create those idiotic titles, lamenting over the SEO and Twitter appeal that they’d have on the masses. I’m straight up Jiggly-puffing your web blogs, while you snore.
This is a very awkward tight rope for Assange to cross. If indeed Seth Rich was the source of the DNC leaks, then we all know why he was murdered. On the otherhand, if Assange were to blow the whistle on this important fact, it might serve as a deterrent against future leakers to come public with information. Remember, Assange isn’t trying to get Trump elected. Bringing down Hillary, by pursuing the “Seth Rich was killed because of DNC leaks,” might prove to be extremely detrimental to Assange’s organization.
In this interview, he didn’t flat out say it. But any person with an IQ north of 85 can sure as hell figure out what he’s suggesting.
Julian Assange: Whistleblowers go to significant efforts to get us material and often very significant risks. As a 27 year-old, works for the DNC, was shot in the back, murdered just a few weeks ago for unknown reasons as he was walking down the street in Washington.
Reporter: That was just a robbery, I believe. Wasn’t it?
Julian Assange: No. There’s no finding. So… I’m suggesting that our sources take risks.
Shares of YELP are screaming higher in the after-hours and for good reason. The company was scheduled to finish last in the race and instead BROKE THE FUCKING LEGS AND ARMS OF THEIR COMPETITORS and finished first.
I am quite biased when it comes to YELP, being an avid user of the service and believer in the long term prospects for this magnificent company. Bearshitters like to deride the company as some piece of shit, Google waste product. In fact, Google tried to buy them years ago and Steve Jobs begged Jeremy Stoppleman to not sell out to them. Correctly, Jobs cited the Google people to be evil dick sucking bastards, who wanted to rule the world with iron, gay, fists.
Stoppleman will be having none of that for the eloquent and Liberace styled world of fine dining.
For now, the company is free and independent from the social media oligarchy of Facebook-Google.
Reports Q2 (Jun) earnings of $0.16 per share, $0.01 better than the Capital IQ Consensus of $0.15; revenues rose 29.5% year/year to $173.4 mln vs the $169.8 mln Capital IQ Consensus.
Co issues upside guidance for Q3, sees Q3 revs of $180-184 mln vs. $179.59 mln Capital IQ Consensus Estimate. Adjusted EBITDA is expected to be in the range of $24 million to $28 million. Stock-based compensation is expected to be in the range of $21 million to $23 million, and depreciation and amortization is expected to be approximately 5% of revenue.
Co issues upside guidance for FY16, sees FY16 revs of $700-708 mln vs. $698.94 mln Capital IQ Consensus Estimate. Adjusted EBITDA is expected to be in the range of $100 million to $108 million. Stock-based compensation is expected to be in the range of $85 million to $87 million, and depreciation and amortization is expected to be approximately 5% of revenue.
Valuation wise, the stock is inexpensive, trading just 4x sales. Bear in mind, this is the single best social media invention of all time. To be selling under TWTR’s 5.5 p/s valuation is an utter and complete joke.
The shares are up 10% in the after hours and how a clean run path towards $75, based upon price to sales compares to GRUB and LNKD.
In this video, Cramer sucks the knee caps of TWLO, calling the modern day Vonage ‘the future of cloud computing.’ He was fantastically impressed by the conference call, saying it was ‘one of the great calls.’
They fucking text message alerts. Okay? Not exactly revolutionary stuff.
Canaccord likes the story, but keeps the stock at a hold–due to a thing called ‘valuation.’
“For investors who care about long-term prospects, we came away incrementally more positive following this call. The punch line here is that Twilio has a very attractive business model in which it gets paid on a consumption or transactional basis. The firm is at the center of a big trend toward mobile apps and, based on our conversations, has best-in-class developer tools, the combination of which bodes well for its long-term prospects.”
Elon Musk is, without question, one of the premier innovators in our time. Maybe he sees something the rest of us don’t But, even Steve Jobs was fallible. His first stint at Apple is a perfect example of it. This merger of car company and money losing solar panel maker is ridiculous on almost every level.
After the bell, SCTY warned and cited difficulties in securing financing to fudge their numbers, in lieu of the proposed merger. Hardly anyone buys those stupid panels. The company survives only be securing financing to lease out the panels and they lose money doing it to boot.
Reports Q2 (Jun) loss of $2.32 per share, excluding non-recurring items, $0.19 better than the Capital IQ Consensus of ($2.51); revenues rose 80.7% year/year to $185.8 mln vs the $147.31 mln Capital IQ Consensus.
Preannounced 201 MW installed vs. 185 MW guidance.
Co issues downside guidance for Q3, sees EPS of ($2.55-2.65), excluding non-recurring items, vs. ($2.34) Capital IQ Consensus Estimate; sees Q3 revs of $155-168 mln vs. $173.77 mln Capital IQ Consensus Estimate. For Q3 2016 we expect to install 170 MW, as the softer Q1 2016 bookings feed their way into installation throughput. Driven by the pick-up in bookings we have seen in Q2 and July as well as C&I’s seasonally strongest period, we expect to install between 315 and 415 MW in Q4 2016 (C&I experiencing a significant uptick in MW Deployed including some projects already under construction C&I).
Expect total 2016 MW Installed of 900—1,000 MW (down from 1.0-1.1 GW), with the mid-to-high end of the range assuming an improvement in residential sales productivity. As our infrastructure had been built to handle ~1.25 GW of annual capacity, we will be reducing our cost structure to accommodate our current forecasted volume run rate and positioning ourselves to report one of the lowest Cost per Watt in our history in the fourth quarter of 2016.
Cash balance expected to increase by the end of Q3 2016 (as compared to the end of Q2 2016) and to further increase by the end of Q4 2016 (as compared to the projected closing balance as of the end of Q3 2016)
Being acquired by TSLA for 0.11 TSLA shares per SCTY share.