iBankCoin
Home / 2016 / August (page 20)

Monthly Archives: August 2016

The Market is Pricing in Zero Rate Hikes for the Next Year

Everything makes sense, with exception to the fact that the market doesn’t give a shit about the economy. It refuses to cede any real gains, as it pertains to chances of a Fed rare hike.

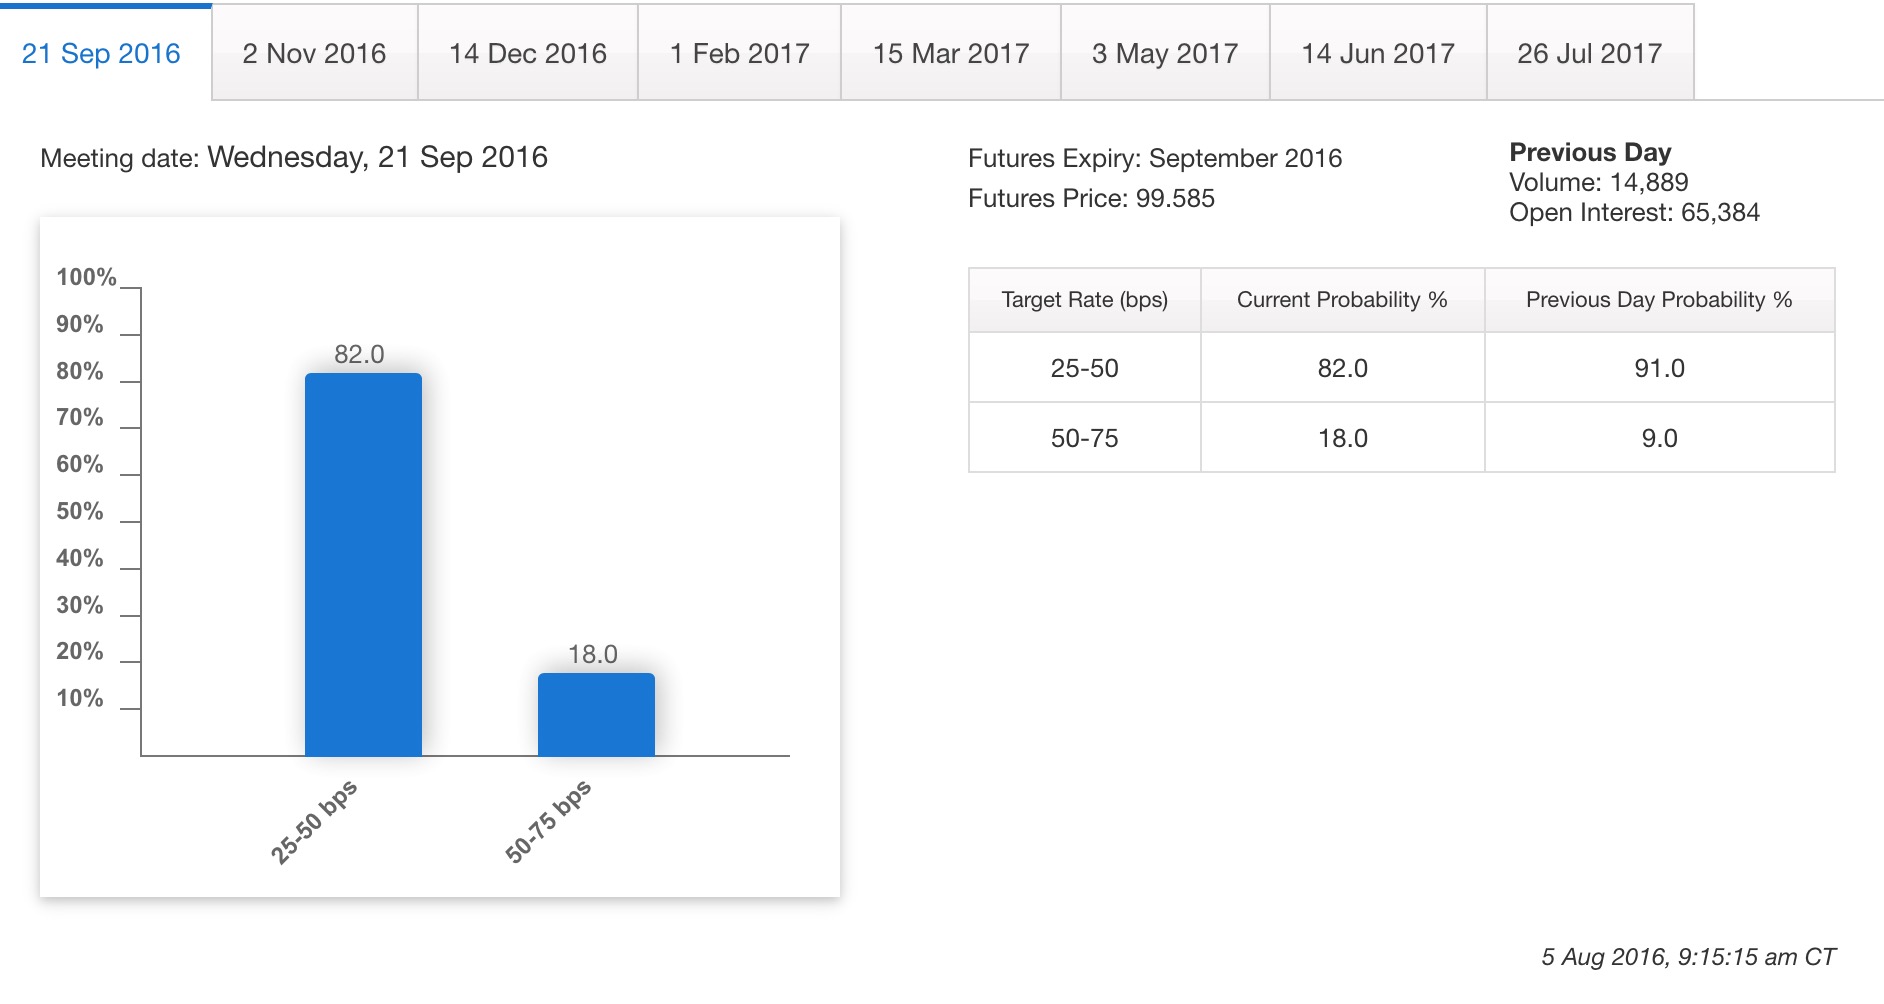
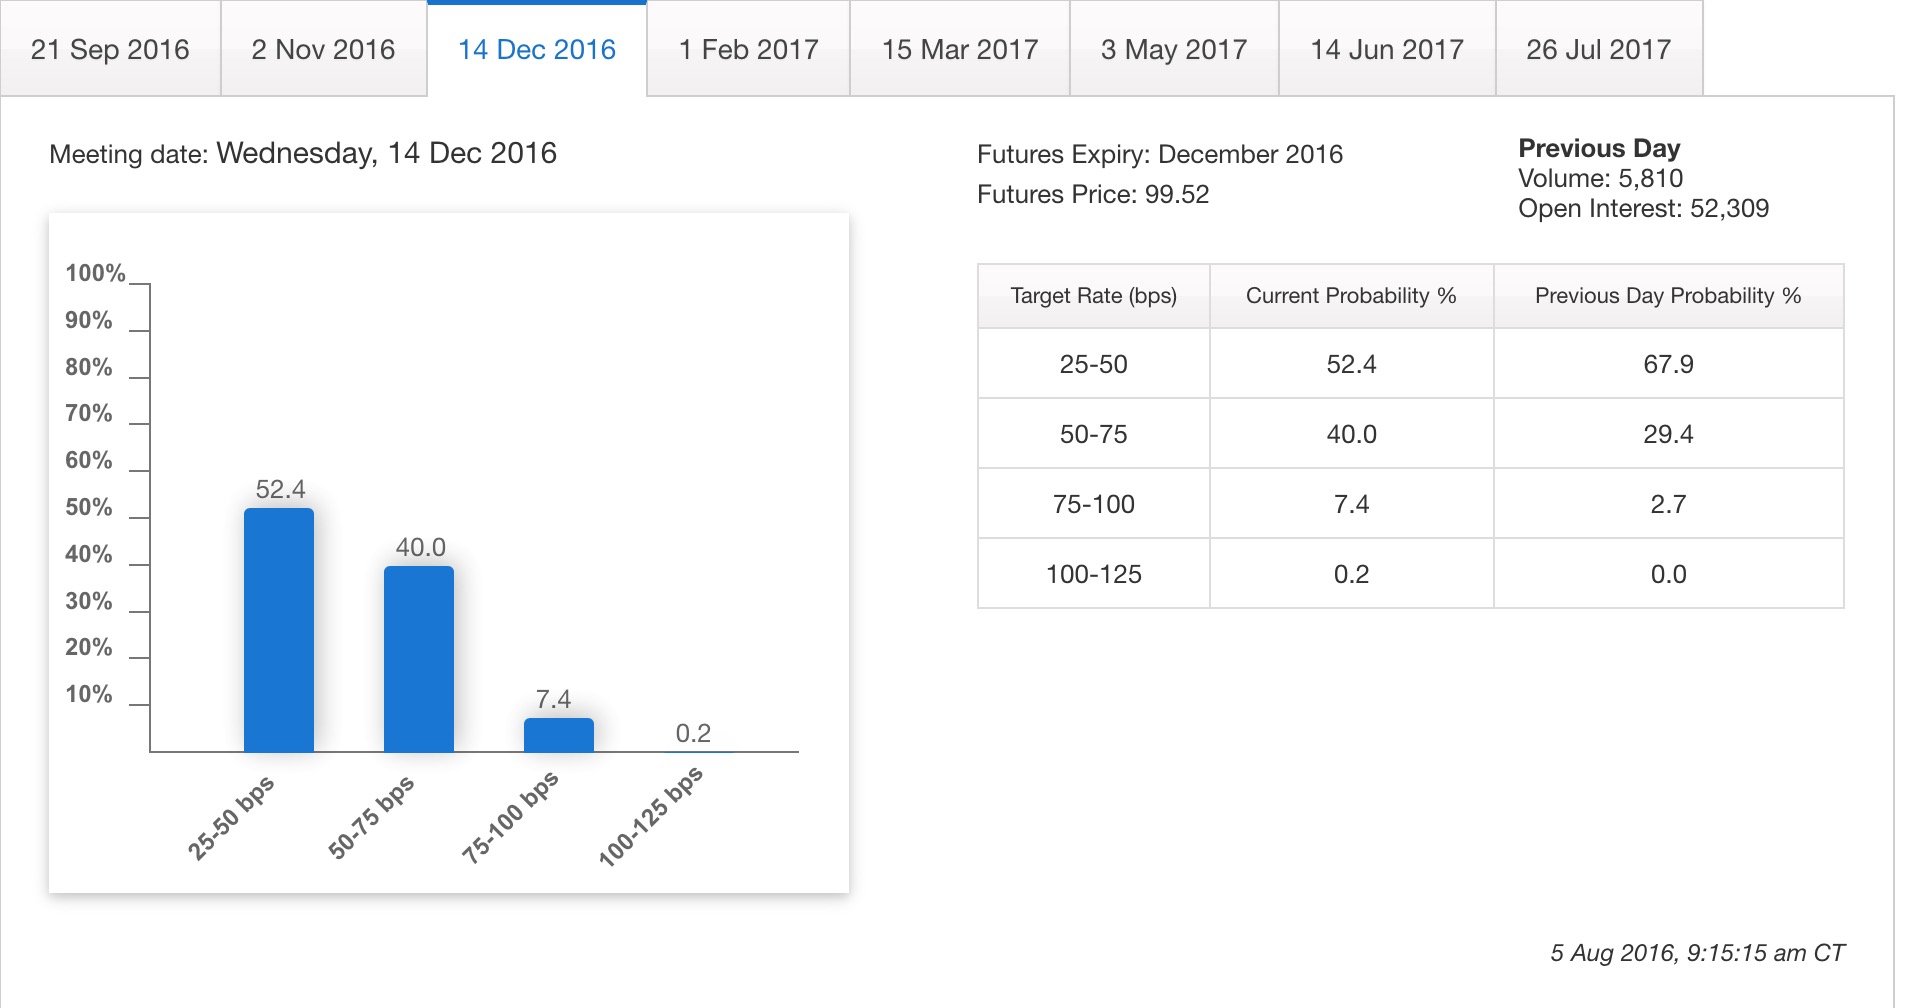
Yesterday, the chances of a September hike was 9%. Today it doubled, but only 18%. The chances for a December hike are just 40%. As a matter of fact, the market is pricing in zero rate hikes for the next year.

image

image

Whatever.

The dollar is still up big, commodities down, stocks up.

Comments »

Commodities Harangued by Losses, as King Dollar Reigns Glorious

The market doesn’t always make sense, but today it does.

Let’s review.

Stocks are higher because the economy is doing well, as indicated by the July jobs report.

Yeah I know, 94m people aren’t in the jobs market. Fuck those people.

The dollar is surging v the euro because people believe the Fed will hike rates. Frankly, if the economy is strong, they should. Moreover, people should get over it already.

As a result of the perceived tightness in US monetary policy, the dollar gains are pushing down commodities.

image

If we’re being true and honest here, gold, silver, oil and the rest of them should trade down on the perception that the Fed will hike. This was the primary reason why I sold out of my gold positions. Moreover, this is one of the reasons why I am short FCX and oil drillers.

As far as bonds are concerned, the short duration yields will be affected most. As a matter of fact, US 30 yr should do okay, since we didn’t have QE in the first place. Plus, the market is always skittish about the global economy and will continue to buy our bonds in favor of Japan and Europe’s. Providing negative yields persist overseas, a floor is in place for TLT.

Comments »

$BMY SHAREHOLDERS SMASHED WITH HARROWING LOSSES FOLLOWING FAILED CLINICAL DRUG RESULTS

How can BMY lose $25b in market cap because of a failed clinical trial of a drug that does only $550 million by its chief competitor Merck?

I can’t even begin to rationalize this drop in a mega cap super star company, the crown jewel of Princeton, NJ.

Opdivo has become a foundational treatment that is transforming cancer care across multiple tumor types. While we are disappointed CheckMate -026 did not meet its primary endpoint in this broad patient population, we remain committed to improving patient outcomes through our comprehensive development program, including the ongoing Phase 3 CheckMate -227 study exploring the potential of the combination of Opdivo plus Yervoy for PD-L1 positive patients, and Opdivo plus Yervoy, or Opdivo plus chemotherapy in PD-L1 negative patients.”

I hear they’re working on chimeras in that sprawling prime real estate in Princeton. Seriously, this 18% drop seems a bit excessive. Then again, we’re an excessive people.

image

MRK is benefitting from BMY’s demise, which is doubly absurd.

image

Comments »

AMERICA: 255,000 JOBS ADDED IN JULY

Fuck yeah.

Last month we added 292k new jobs. Granted, many of those jobs are burger flippers at Wendy’s; but who’s looking at the details aside from me and a few others?

Unemployment rate stands at 4.9%, a little higher than what Trump is polling at in a Reuters poll.

“Solid labor markets mean households will be in good shape, incomes will be OK,” Michael Gapen, chief U.S. economist at Barclays Plc in New York, said before the report. Gapen also said the Fed probably will raise rates in September if hiring remains strong.

Labor participation rate, which is a stat that has been maligned as horseshit, came in at 62.8%, up 0.1%.

‘Merica.
Wage growth rose ahead of forecast, up 0.3% to $25.69.

The net result is a run up in futures. Markets should climb by triple digits at the open. Short dated yields are spiking, indicative of a possible Fed rate hike. That has to be on the table once again. If so, the markets have to be okay with it, being that the economy is adding 250k jobs per month and Q3 GDP is trackI got +3.7%.

If the Fed can’t hike under these conditions, they’ll never hike.

On paper, this is bearish for gold, short dated bonds, and bullish for stocks.

Comments »

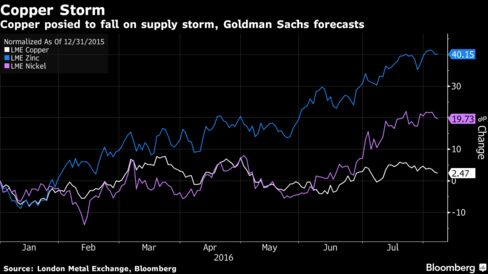
Goldman: ‘Copper is Entering the Eye of the Supply Storm’, Predicts Prices Will Plunge Soon

Goldman is out with a report predicting catastrophe is about to strike down the price of copper, by 17% in fairly short order. They’ve come to this conclusion, as a matter of fact, tracking 20 companies which represent more than 60% of worldwide supply. Like oil, supply is rising across the board in the debt laden copper space. The notion that any of the major commodities are enduring supply constraints is a bald faced lie.

Goldman said these 20 companies are set to increase supply by 15% in the coming quarters, which should put additional pressure to an already oversupplied copper market.

“Company guidance and our estimates suggest that copper is entering the eye of the supply storm,” analysts including Max Layton and Yubin Fu wrote in an e-mailed report received on Friday. A drop to $4,000 would be a 17 percent slump from Thursday’s close on the London Metal Exchange.

“This ‘wall of supply’ is expected to translate into higher copper smelter and refinery charges and ultimately, higher refined-copper production, set against softening demand growth,” Layton and Fu wrote. The metal is seen at $4,500 a ton in three months and $4,200 in six, they said, reiterating targets.

In July, Barclays Plc said supply may exceed demand every year through to 2020. The month before, Stephen Higgins, who heads Freeport-McMoRan Sales Company Inc., a division of the largest publicly traded copper miner, said more production has come on stream at a time demand growth in China has slowed.


At the time of this post, I am short FCX.

Comments »

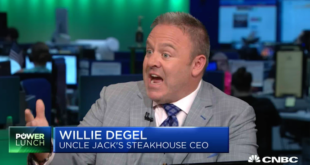
Willie Degel on the Restaurant Business: ‘If You’re Not Making Money, You’re Making Believe’

Badda bing.

This is an interesting interview about the restaurant industry with the CEO of Jack’s Steakhouse, Willie Degel. Having grown up in NY, I am accustomed to these sort of Brooklyn accents. Those of you in the midwest must cringe upon hearing it. In my experience, however, you have more to worry about with the Upper East Side Mid-Atlantic accent guy than someone like this.

Comments »

Hortonworks Has Been Destroyed

I once met a programmer who worked here. His stock options are, without question, deeply underwater.

The problem with these fast growing tech companies is they’re unable to make money. If you gave me $1billion, I guarantee you I could generate $2 billion in revenues, while burning through the cash in a glorious ball of Silicon Valley fuckery.

The CEO is departing as well. Go team!

  • Reports Q2 (Jun) loss of $0.72 per share, $0.04 worse than the Capital IQ Consensus of ($0.68); revenues rose 45.7% year/year to $43.64 mln vs the $45.24 mln Capital IQ Consensus.
  • Operating billings, the aggregate value of all invoices sent to our customers in a given period, were $62.2 million for the second quarter of 2016, an increase of 49 percent compared to the second quarter of 2015.
  • Deferred revenue was $131.8 million for the second quarter of 2016, a 23 percent increase over the $106.8 million reported as of December 31, 2015 and a 64 percent increase over the $80.6 millionreported as of June 30, 2015.
  • Co issues guidance for Q3, sees Q3 GAAP revs of ~$45 mln, may not be comparable to $49.30 mln Capital IQ Consensus Estimate, expects operating billings, the aggregate value of all invoices sent to our customers in a given period, to be $68.0 million.
  • Co issues guidance for FY16, sees FY16 GAAP revs of $177 mln, may not be comparable to $191.41 mln Capital IQ Consensus Estimate, expects operating billings, the aggregate value of all invoices sent to our customers in a given period, of $265.0 million in 2016 (Unch from prior).

Shares are being treated punitively in the after-hours, collapsing by 25%.

Comments »

OIL PARTY: $EOG RAISES PRODUCTION GUIDANCE AND DRILLING LOCATIONS, ASSUMES OIL TO JUMP 50% FROM CURRENT LEVELS

In spite of EOG’s 28% drop in revenues over last year and a persistent bleeding out of cash, due to deleterious losses, shares are rising in the after hours on news that the company lost less than had previously been expected. Moreover, and indelibly so, the company is INCREASING the number of ‘premium drilling locations’ by around 30%–because things are so peachy green now.

Reports Q2 (Jun) adj net loss of $0.38 per share, $0.10 better than the Capital IQ Consensus of ($0.48); revenues fell 28.1% year/year to $1.78 bln vs the $1.52 bln Capital IQ Consensus.

In the second quarter 2016, EOG increased its inventory of net premium drilling locations from 3,200 to 4,300.
Total premium net resource potential increased from 2.0 billion barrels of oil equivalent to 3.5 BnBoe.

U.S. crude oil volumes of 265,400 barrels of oil per day in the second quarter 2016 exceeded the midpoint of the company’s guidance by 2 percent.
Total natural gas production for the second quarter 2016 decreased 5 percent versus the same prior year period.

The company has offered some super bullish guidance, going forward. They’re upping the numbers of wells to be drilled, as well as production levels, assuming WTI prices of $60, or just 50% higher from current prices.

3Q & FY16 Production guidance

Q3: Total crude oil/condensate volumes between 268.4-280.8 MBbld; NGL volumes between 75-79 MBbld; Natural gas volumes between 1085-1139 MMcfd
FY16 Total crude oil/condensate volumes between 269.6-275.8 MBbld; NGL volumes between 76-80 MBbld; Natural gas volumes between 1,127-1174 MMcfd

2016 Capital Plan Update and 2020 Crude Oil Production Outlook:
As a result of cost reductions and efficiency improvements, EOG has increased its targeted number of well completions for 2016 from 270 to 350 net wells. Many of the additional well completions are scheduled for late 2016.

In addition, due to increased drilling productivity, the company expects to drill 250 net wells, 50 more than in its original 2016 plans. This increase in activity will be accomplished while maintaining 2016 capital expenditure guidance of $2.4 to $2.6 billion, excluding acquisitions. EOG can achieve significant production growth with balanced cash flow from 2017 through 2020, even in a moderate commodity price environment.

Based on EOG’s long-term plan and assuming a flat $50 West Texas Intermediate crude oil price (WTI), EOG would expect 10 percent compound annual crude oil production growth through 2020.

Assuming flat $60 WTI, EOG would expect 20 percent compound annual crude oil production growth through 2020.

Party like it’s 2007. EOG is rising in the after hours.

Comments »

FIReEYE LOSES AGAIN; SHARES SHIT THE BED FOLLOWING HEINOUS EARNINGS REPORT

Shares of FireEye are plunging in the after-hours, by 14%, in what can only be described as ‘business as usual’ for this shit filled company of perfidious swindlers.

Reports Q2 (Jun) loss of $0.33 per share, excluding non-recurring items, $0.06 better than the Capital IQ Consensus of ($0.39); revenues rose 18.9% year/year to $175 mln vs the $181.57 mln Capital IQ Consensus.

Co issues guidance for Q3, sees EPS of ($0.32)-($0.30), excluding non-recurring items, vs. ($0.24) Capital IQ Consensus Estimate; sees Q3 revs of $180-186 mln vs. $208.09 mln Capital IQ Consensus Estimate.

Total Billings in the range of $200-215 mln.

Operating margin in the negative 25-27% range
Co issues guidance for FY16, sees EPS of ($1.32)-($1.24), excluding non-recurring items, vs. ($1.24) Capital IQ Consensus Estimate; sees FY16 revs of $716-728 mln vs. $793.45 mln Capital IQ Consensus Estimate.

Non-GAAP Billings in the range of $835-855 mln (Prior $975-1055 mln)
Non-GAAP Operating Margin in the range of negative 26-28%

The more hackers hack, the less business FireEye get–because they’re a company of submental morons.

Comments »

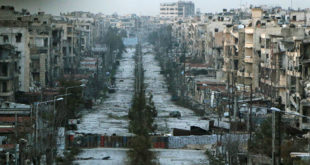
Russia Accuses the U.S. of Backing ‘Animals’ Using Chemical Weapons in Syria

It’s s slow news day, so I figured a little world war 3 saber rattling might be of interest to you.

As the war in Syria wades on and the ‘rebels’ we back cut off the head of 10 year olds and then post it on social media sites, Russia is trying to support the secular Assad, who is also an animal in his own right, in an effort to restore balance and remove the fucking caliphate from Syrian soil.

In the meantime, the ‘rebels’ are using chemical weapons against civilians without warning and Russia is making it known.

Zakharova criticized the United States over an incident the Russian military said occurred on Aug. 2 in eastern Aleppo when rebels used poison gas, killing at least seven people.

She blamed the Free Syrian Army’s Nour al Din al-Zinki group for what she said was a crime. The same group, which has received U.S. military backing, said last month it was investigating the beheading of a young child in Aleppo after video footage circulated showing the boy being killed by a man whom activists identified as a member of the group.

“The United States is supporting these animals who used poison gas against the civilian population,” Zakharova wrote.

“Unfortunately it’s not the only tragedy which the ‘moderates’ backed by Washington stand behind.”

“The United States and the SDF are not taking any steps to warn people to avoid deaths,” she said, saying that U.S and coalition aircraft had killed hundreds and wounded thousands of civilians according to “conservative estimates.”

“If our Western colleagues and above all Washington do everything again not to notice these facts then any of their talk about an end to bloodshed in Syria will simply become preposterous,” wrote Zakharova

Upwards of 200,000 people have been killed in Syria since the beginning of their war, leading to a flood of migrants, estimated between 1-3 million, into Europe.

Comments »