iBankCoin
Home / 2016 (page 283)

Yearly Archives: 2016

Cramer & Faber’s Take on Valeant Pharmaceuticals Plunge: ‘They’re Being Eviscerated’

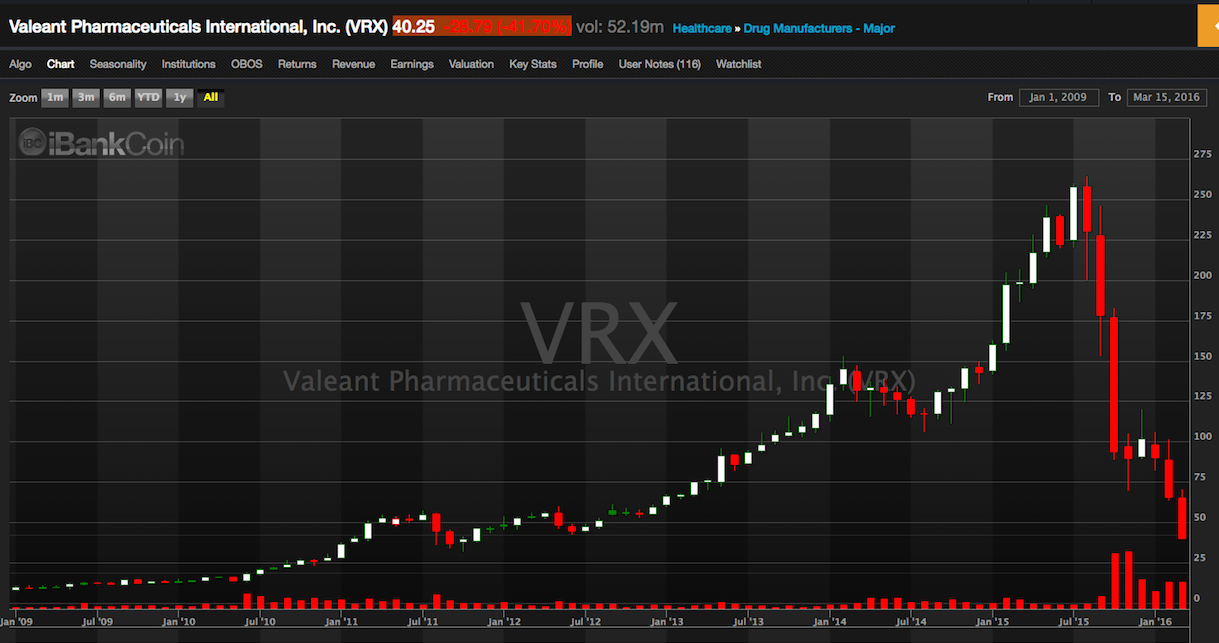
This is easily the biggest story of 2016. The once mighty VRX, with its hefty market cap and pernicious business model, has fallen. The men who supported its heft and insidious schemes have been given a Viking Funeral. Their ashes have been strewn across Wall Street for others to take notice and to fear the deleterious effects of unbridled hubris.

Faber sums up the quarterly disaster and Cramer offers his insight into this unbelievable story.

Shares of Valeant are down $29, or 41% for the day–down from an all-time high of $259.
VRX3

It’s worth mentioning, Andrew Left from Citron Research warned everyone of this eventuality many month’s before everyone else. Major props goes out to him and his staff.

This was forwarded to me from @Lance0333 on Twitter.

Allergan’s case against accepting Valeant’s takeover bid.

agn

Comments »

In Light of Today’s $500 Mill Loss in $VRX…

I almost feel bad doing this. After all, billionaires (extra Bernie Sanders) have feelings too. But the peril Bill Ackman and his cohorts face now were brought on by their own hubris. These brush fires were lit a few years ago, when they used VRX to make a bid for AGN, clearly an insider trading scheme that was permitted to go unchecked. The net result was Pershing Square concentrating 40% of their fund in AGN, into a self-directed, Valeant led, buyout offer–which resulted in a 40% return for the Man from Montauk.

Ironically, he is now being hung by his own petard in the burning house of cards, which is VRX–currently off by a staggering  40%.

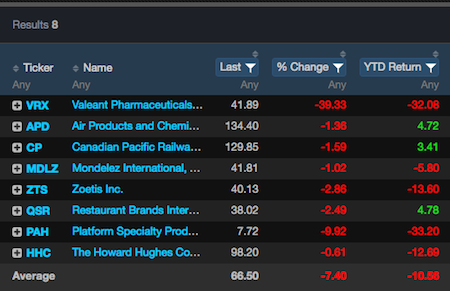
Here are Pershing Square’s positions. Should this decline in VRX force redemptions, which is bound to happen en masse, the following stocks might come under pressure–as he liquidates the fund.

VRX2

And let’s not forget this.

HLF

Ackman is short 20 million shares and is exposed to a short squeeze, now that his fund is being shredded.

Comments »

Obama Flip Flops on Atlantic Drilling Decision, Caves to Environmentalists

I love how these psychopaths are so anti-fossil fuel, yet use said fossils when flying in airplanes, cars, heating of homes etc. I’d love to be able to forgo my addiction to dirty fossil fuels. But the windmill and hideously ugly solar panels just aren’t doing it for me.

Obama, in an effort to secure his super liberal bonafides, reversed an earlier decision which gave the states of Georgia, Virginia, S. Carolina and N. Carolina permission to tar their beaches with light sweet crude. They are no longer permitted to do suchness.

“Any new offshore drilling will be a stain on President Obama’s climate legacy,” May Boeve, executive director of the group 350.org, said in a statement Monday. “If the president is going to meet the targets he agreed to at the climate talks in Paris, he needs to keep fossil fuels in the ground or in this case, under the sea. We can’t afford any more oil spilling into the oceans and carbon pouring into the atmosphere.”

Comments »

Pershing Square is Being Skinned Alive In Valeant Today, Losses Top $400 Million

Shares of VRX are plunging, in earnest, right now–off by almost $20 or 30%. The company missed expectations by a football field. But I suspect the verbiage in their conference call, regarding covenants that might be breached, which can cause a default, is what’s spooking investors.

  • Net leverage to pro forma adjusted EBITDA per credit agreement expected to be ~5x by year end 2016
  • Credit agreement — March 30th: 10-K due; default if not delivered — 30 days to cure default by delivering 10-K (if not filed by March 30th) — April 29th: event of default if 10-K is not delivered
  • Bond indentures — March 16th: If 10-K not filed, breach of the reporting covenant in the indentures; trustee or holders of at least 25% of any series of notes may deliver a notice of default — 60 days from the date of receipt of a notice of default to file the 10-K and thereby cure the default
  • Launching process with bank lenders next week to seek to extend deadline for filing our 10-K and Q1 10-Q, and waive cross-default arising from breach of reporting covenant in the indentures
  • Plans to pay down $1.7 bln debt this year

VRX

According to recent filings, Pershing Square owns about 20 million shares of VRX. Valueact, Sequoia and Paulson are also major shareholders. The hedge fund industry are racked with immeasurable losses today, long this bullshit stock from absurdly high levels.

VRX has more than $30 billion in debt. With today’s drop in share price, their debt/eq level is approaching 2x.

Comments »

Nucor Warns, But Offers Promising Outlook

Never trust the positive comments out of a CEOs mouth right after he warns. Nevertheless, that’s exactly what NUE did this morning. Maybe they will do better than 2015. Given that 2015 was nothing short of disaster for the industry, I’d say the bar is quite low.


Co issues downside guidance for Q1 (Mar), sees EPS (excluding $0.03 LIFO charge) of $0.23-0.28, excluding non-recurring items, vs. $0.32 Capital IQ Consensus Estimate.
Nucor expects first quarter results to be in the range of $0.20 to $0.25 per diluted share. Projected first quarter of 2016 results include an estimated LIFO expense of $15.0 million ($0.03 per diluted share), compared to a credit of $217.8 million ($0.41 per diluted share) in the fourth quarter of 2015 and a credit of $16.5 million ($0.03 per diluted share) in the first quarter of 2015.
“Although conditions in world markets remain uncertain, we now believe that full year 2016 profitability will be slightly improved compared to full year 2015 results, excluding the impairment charges taken in the prior year. This improved performance is driven by expected increases in the performance of the steel mills and steel products segments.”

Nucor’s stock has been on a tear throughout 2016.


image

Comments »

Cramer Much Less Sanguine About the Economy, Ahead of the Fed

Apparently, he’s disappointed by retail sales.

I get the sense that Cramer, and many others of his ilk, put on elaborate acting demonstrations in order to try to sway public opinion, and ultimately Fed policy, towards a path of accommodation. He’s doing them a favor, quite frankly. But you know, deep down, Cramer is effervescently bullish.

Comments »

Banks Are at the Vanguard of Losses in Europe

European indices are lower from 0.7-1.5%, continent-wide.  The largest losses are overly abundant in the banks, even more so than their energy companies.

Banks

Here in the states, Dow futures are off by 91.

Comments »

Losses Await Investors in the Early Going

Crude oil is lower by 2.2%. Gold is down by another 1% and is acting strangely horrible.

The yen is getting hammered by 1%.

S&P futures are off by 13.

The ark floats, unharassed by the negative feedback loop, higher by 0.8%.

Bill Ackman is undergoing a measureless disaster with VRX trading down more than 17%.

The energy is inexorably absent from the market ahead of empirically important Federal Reserve meetings.

Comments »

Pershing Square Broken to Pieces on the Valeant Catherine Wheel

This stock is like a torture device. I’m assuming most of you are familiar with the Catherine Wheel, yes? It was a device that was used to exact extreme punishment unto those who deserved it, vagabonds, petty thieves, rapists and the like. The way it worked was pretty straight forward. The criminal was tied to a large wooden wheel, spread eagle, with arms and legs fully extended. The executioner would club the prisoner about his bones, go back to the pub for a few pints, then revisit the doomed to club some more. This process would carry about for hours, until the prisoner expired.

image

VRX is Bill Ackman’s Catherine Wheel. His losses in the pre-market are upwards of $200 million. The news is grim.

Reports Q4 (Dec) earnings of $2.50 per share, $0.12 worse than the Capital IQ Consensus of $2.62; revenues rose 22.3% year/year to $2.79 bln vs the $2.76 bln Capital IQ Consensus.

  • Co lowers guidance for Q1, sees EPS of $1.30-1.55 (Prior $2.35-2.55) vs. $2.66 Capital IQ Consensus Estimate; sees Q1 revs of $2.3-2.4 bln ($2.8-3.1 bln) vs. $2.85 bln Capital IQ Consensus Estimate.
  • Co lowers guidance for FY16, sees EPS of $9.50-10.50 (Prior $13.25-13.75) vs. $13.48 Capital IQ Consensus Estimate; sees FY16 revs of $11.0-11.2 bln (Prior $12.5-12.7 bln) vs. $12.54 bln Capital IQ Consensus Estimate.
  • The co also offered guidance for the next four quarters (2Q16 – 1Q17), saying it expects revs to be $11.6-11.8bln,

    and EPS of $10.75-11.25

  • “The challenges of the past few months are not yet behind us and our goal for 2016 is to better balance our priorities across all of our constituencies – physicians, patients, employees, payors, debt holders and shareholders…In discussion with the Board, we have assumed lower growth in our U.S. dermatology, gastrointestinal, and woman’s health portfolios, as well as certain geographies like Western Europe, while keeping our expenses largely unchanged. We plan to work hard to improve these metrics by delivering higher revenues and reducing our costs and, if successful, we hope to beat this guidance in the quarters to come. In the meantime, we are comfortable with our current liquidity position and cash flow generation for the rest of the year, and remain well positioned to meet our obligations.”
    • Due to the ongoing review of company financials, we cannot provide certain comparative metrics that we have historically provided;
      • Metrics we cannot provide: Organic Growth; Business Unit Growth; Price/Volume
    • Under new tax reporting:
      • Q1 EPS guidance is $1.18-1.43 ($1.30-1.55 under old method) vs. $2.66 consensus.
      • FY16 EPS $8.50-9.50 ($9.50-10.50 under old method)  vs. $13.48 consensus
    • Lower revenue trajectory on key businesses
      • More conservative forecasting on Dermatology and Gastrointestinal growth
      • GI: timing and impact of additional sales team and coverage
      • Dermatology: timing and uptake of patient access program
    • Continued growth in Contact Lens, Dentistry, Oncology, Generics, and Eastern Europe, Asia (Emerging Markets)
    • Several businesses off to slow starts: Western Europe, Ophthalmology Rx, Solta, and Obagi
    • Walgreens off to a good start: Walgreens ~30% of total dermatology volume • Brand for generics program on track to launch this summer
    • Given significant reduction in revenues, work needed to align cost base
    • Continued focus and improvement on patient access
    • Co is restructuring smller business and exploring target divestitures of non core assets

Comments »

The Bank of Japan Holds; China’s Yuan Folds

The lunatics in the orient are at it again. Instead of menacing us with capital ships, they distort their economies and twist themselves into knots, leaving all sorts of room for superfluous drama.

The Bank of Japan did nothing tonight, leaving their negative rates idle, opting to take a wait and see approach to fleecing their population any further.

“The BOJ will keep a wait-and-see stance for a while,” Yasuhide Yajima, the chief economist at NLI Research Institute, said before the decision. “I expect further easing in July, when prices data will clearly show they’re off target.”

On the other hand, the PBOC fixed the Chinese yuan lower by 0.26%, the largest single day drop since the glum days of January.

As such, the tone is decidedly negative.
image

image

image

image

Comments »