iBankCoin
Home / 2016 (page 30)

Yearly Archives: 2016

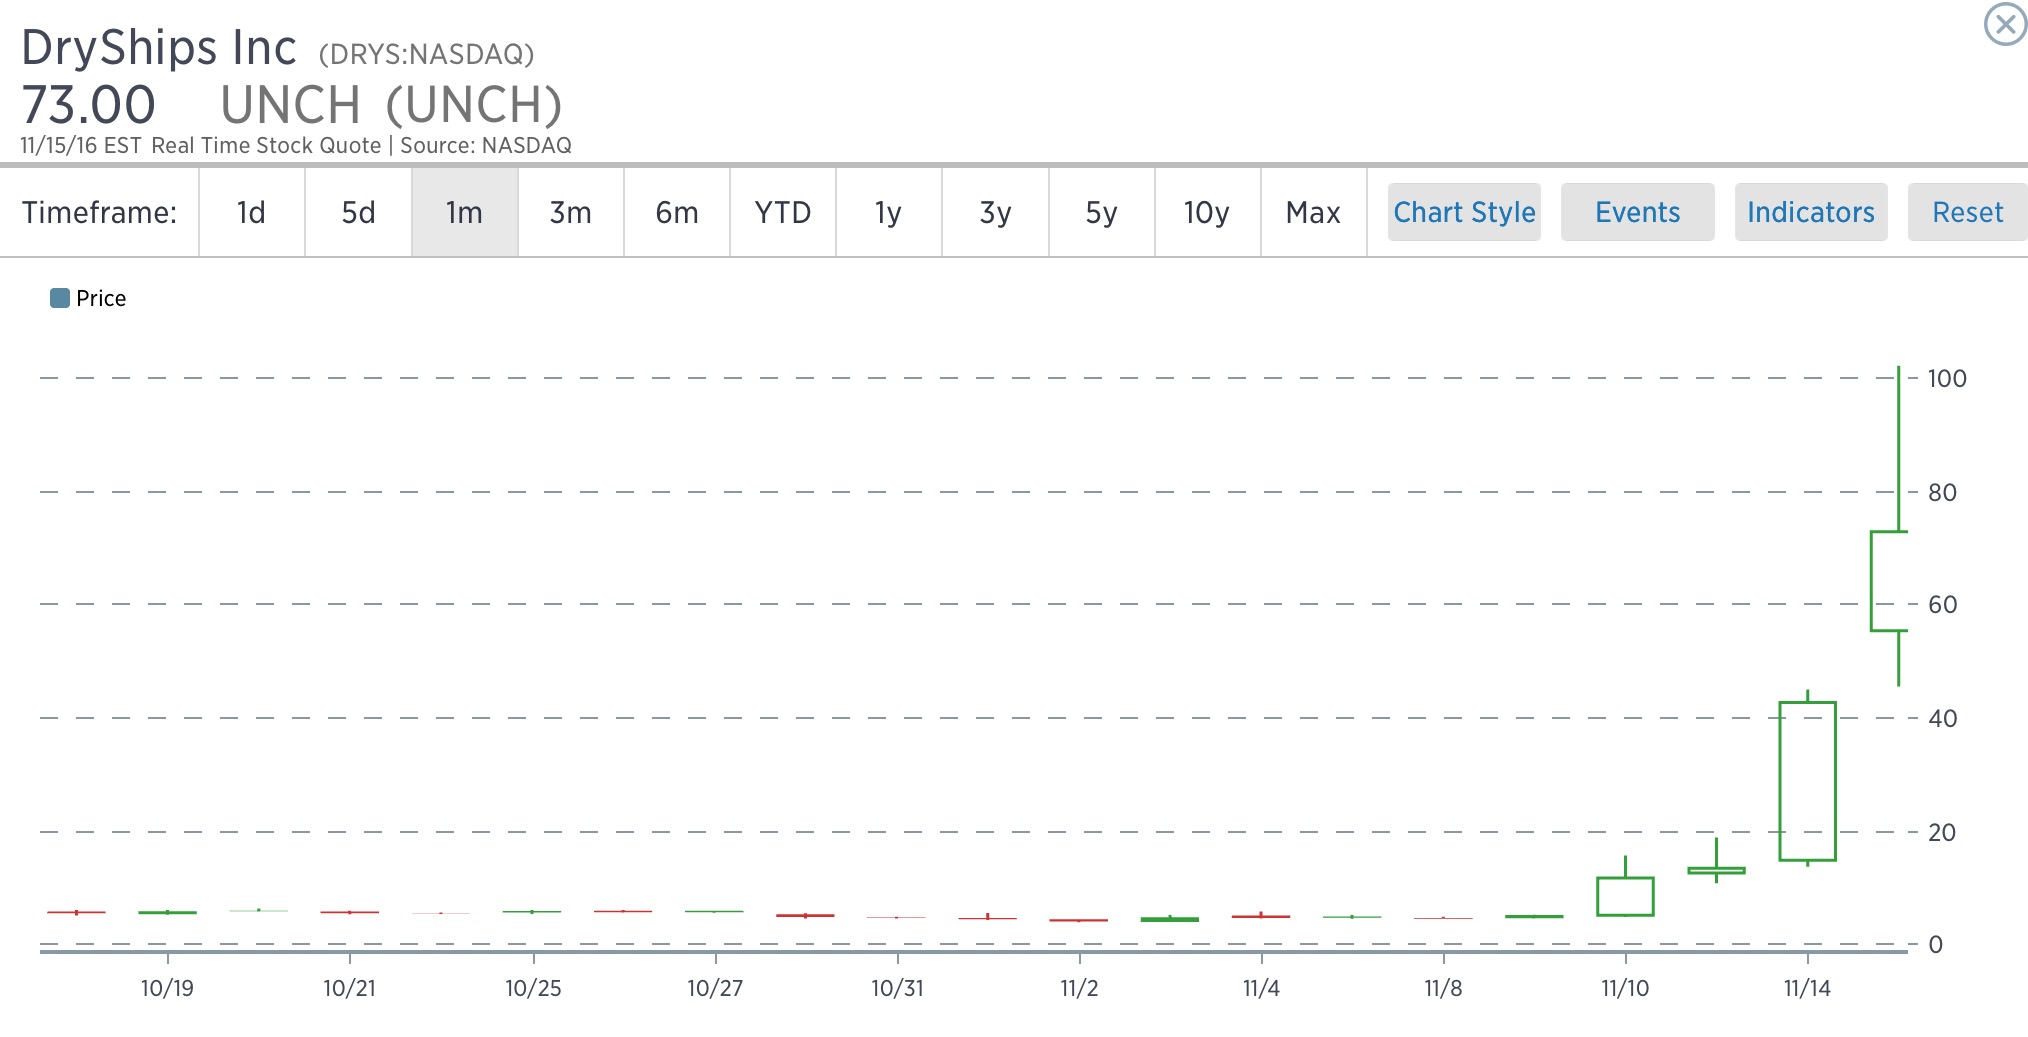
GRAVITY: Dry Bulk Shippers Endure Monumental Single Day Decline

What goes up, eventually comes down and gets ravaged. These fuckers got shot out of the sky and eaten down to the skeleton once marooned on the ground. I’ve been my share of fuckery in the market, but rarely have I seen a sell off in a sector quite as brutal as this one.

$DRYS fell 85%? What in the actual fuck?

Go grab a bag of popped corn and BEHOLD these losses — laugh and chuckle, snort even, at both the misfortune and carelessness of others.
drys

I think we can call this speculative run finished. Fair to say?

Comments »

Apple Asked its Contract Manufacturer in June to Sketch Out Plans to Move iPhone Production to the U.S.

This is what you call hedging your bets. Like any smart business person, Tim Cook asked its slave factory operators at FOXCONN to sketch out plans to move production to the US back in June — in light of Donald Trump promising to ameliorate Apple if they didn’t. Such a plan, however, would be expensive. Estimates from a ‘source’ say it’d cost twice as much to make an iPhone here than in the slave campus in China.

“Apple asked both Foxconn and Pegatron, the two iPhone assemblers, in June to look into making iPhones in the U.S.,” a source said. “Foxconn complied, while Pegatron declined to formulate such a plan due to cost concerns.”

Another source said that while Foxconn had been working on the request from Apple Inc., its biggest customer that accounts for more than 50% of its sales, Chairman Terry Gou had been less enthusiastic due to an inevitable rise in production costs.

“Making iPhones in the U.S. means the cost will more than double,” the source said.

The person added that one view among the Apple supply chain in Taiwan is that U.S. President-elect Donald Trump may push the Cupertino, California-based tech titan to make a certain number of iPhone components at home.

LOL at this stupid as shit article saying the Chairman of FOXCONN was ‘less than enthusiastic’ about moving its largest customer out of China and back into the US, without bothering to mention he’s a government agent and FOXCONN is communist Chinese run. You stupid shits.

America is on its way to becoming great again. Bigly.

Comments »

CATASTROPHE STRIKES THE BULKERS; CIRCUIT BREAKERS TRIGGER TRADING HALTS AFTER CALAMITOUS DROPS

Well, you all knew it was bound to happen at some point. Stocks don’t go from $3-$115 in a week without enduring a crash shortly thereafter.

The rout started after DCIX reversed 40% gains and started to trade lower — after people realized the earnings they reported this morning were abysmal. Then DRYS reopened for trade, after a trading halt that lasted a day, to broken cable elevator trading action — the sort of harrowing decline specifically tailored to bankrupt fools about the rocks — off by 40%. Shares immediately halted, the sector plunged in tumult, multiple stocks are now to and fro trading halts — trying to sort out the end of days scenario now playing out in the sector.

img_5666

img_5661

img_5662

img_5663

img_5664

The game has ended. Thanks for playing.

Comments »

HAPPENING NOW: Former Valeant Exec Arrested; $VRX Plunges Again

What do the former execs of Valeant and Hillary Clinton have in common?

They’re both going to jail.

At least in the case of the former CEO of Philidor, Andrew Davenport, and a one Gary Tanner from Valeant, the DOJ have found sufficient evidence (perhaps an email or two) to arrest them and formally charge them. God willing, this is the first step towards lethal injection and zeroing out of $VRX.

img_5654

img_5655

No word on whether or not Bill Ackman is sad after these turn of events. The delicious irony in all this is Ackman wanted the DOJ to arrest the execs at his biggest short, $HLF, but instead ended up arresting the one’s from his biggest long.

Talk about being galactically fucked.

This is all due to an elaborate kickback scheme, one that is graciously outlined for us by the clerks at the DOJ this morning.

img_5656

img_5657

img_5658

img_5659

Comments »

Day Rates for Capes Surge Overnight Equals Unencumbered Gains for Dry Bulkers Again

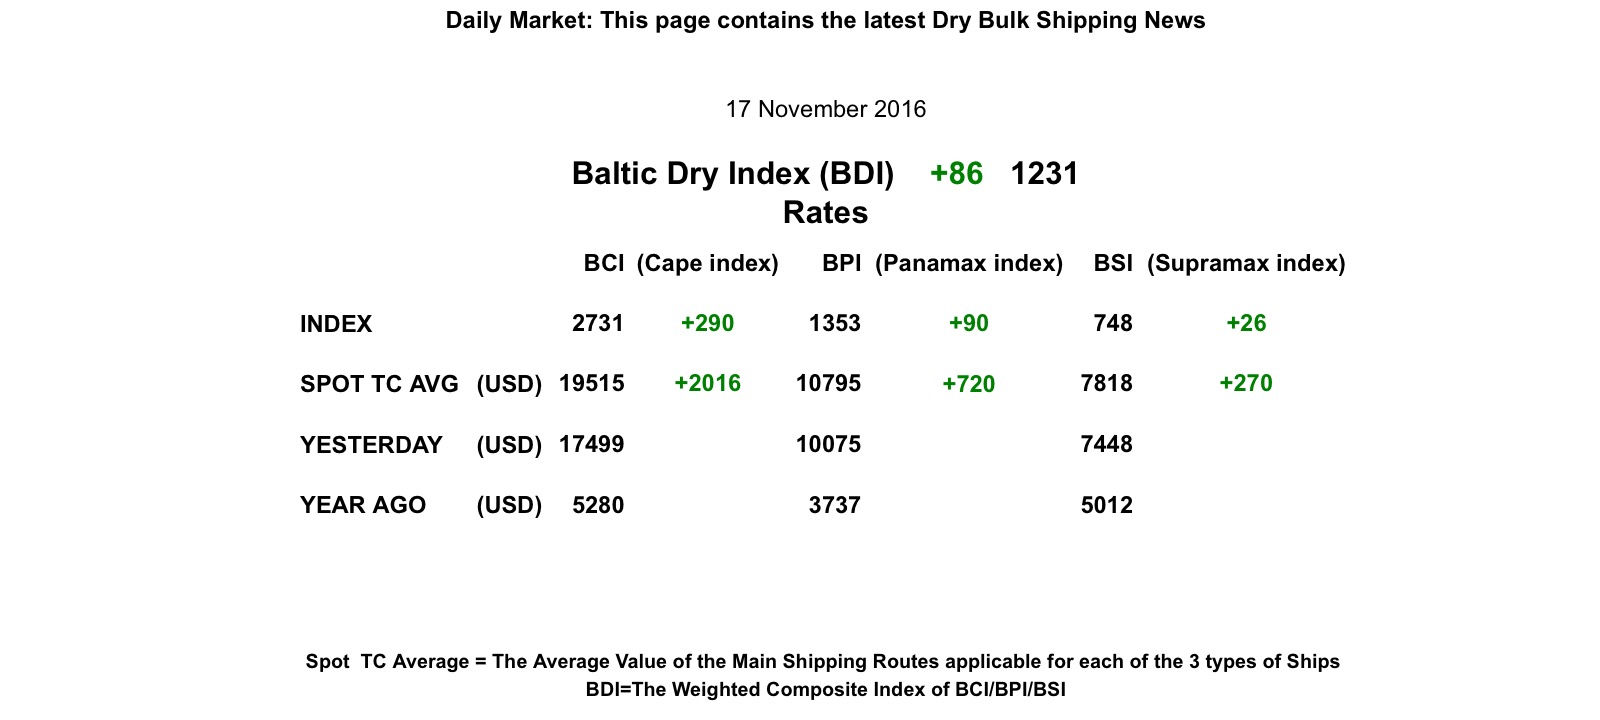
The day rates for the most popular large dry bulk vessels, capesizes, soared by more than 10% overnight — which is now fueling the speculative fires in the bulkers this morning.

img_5648

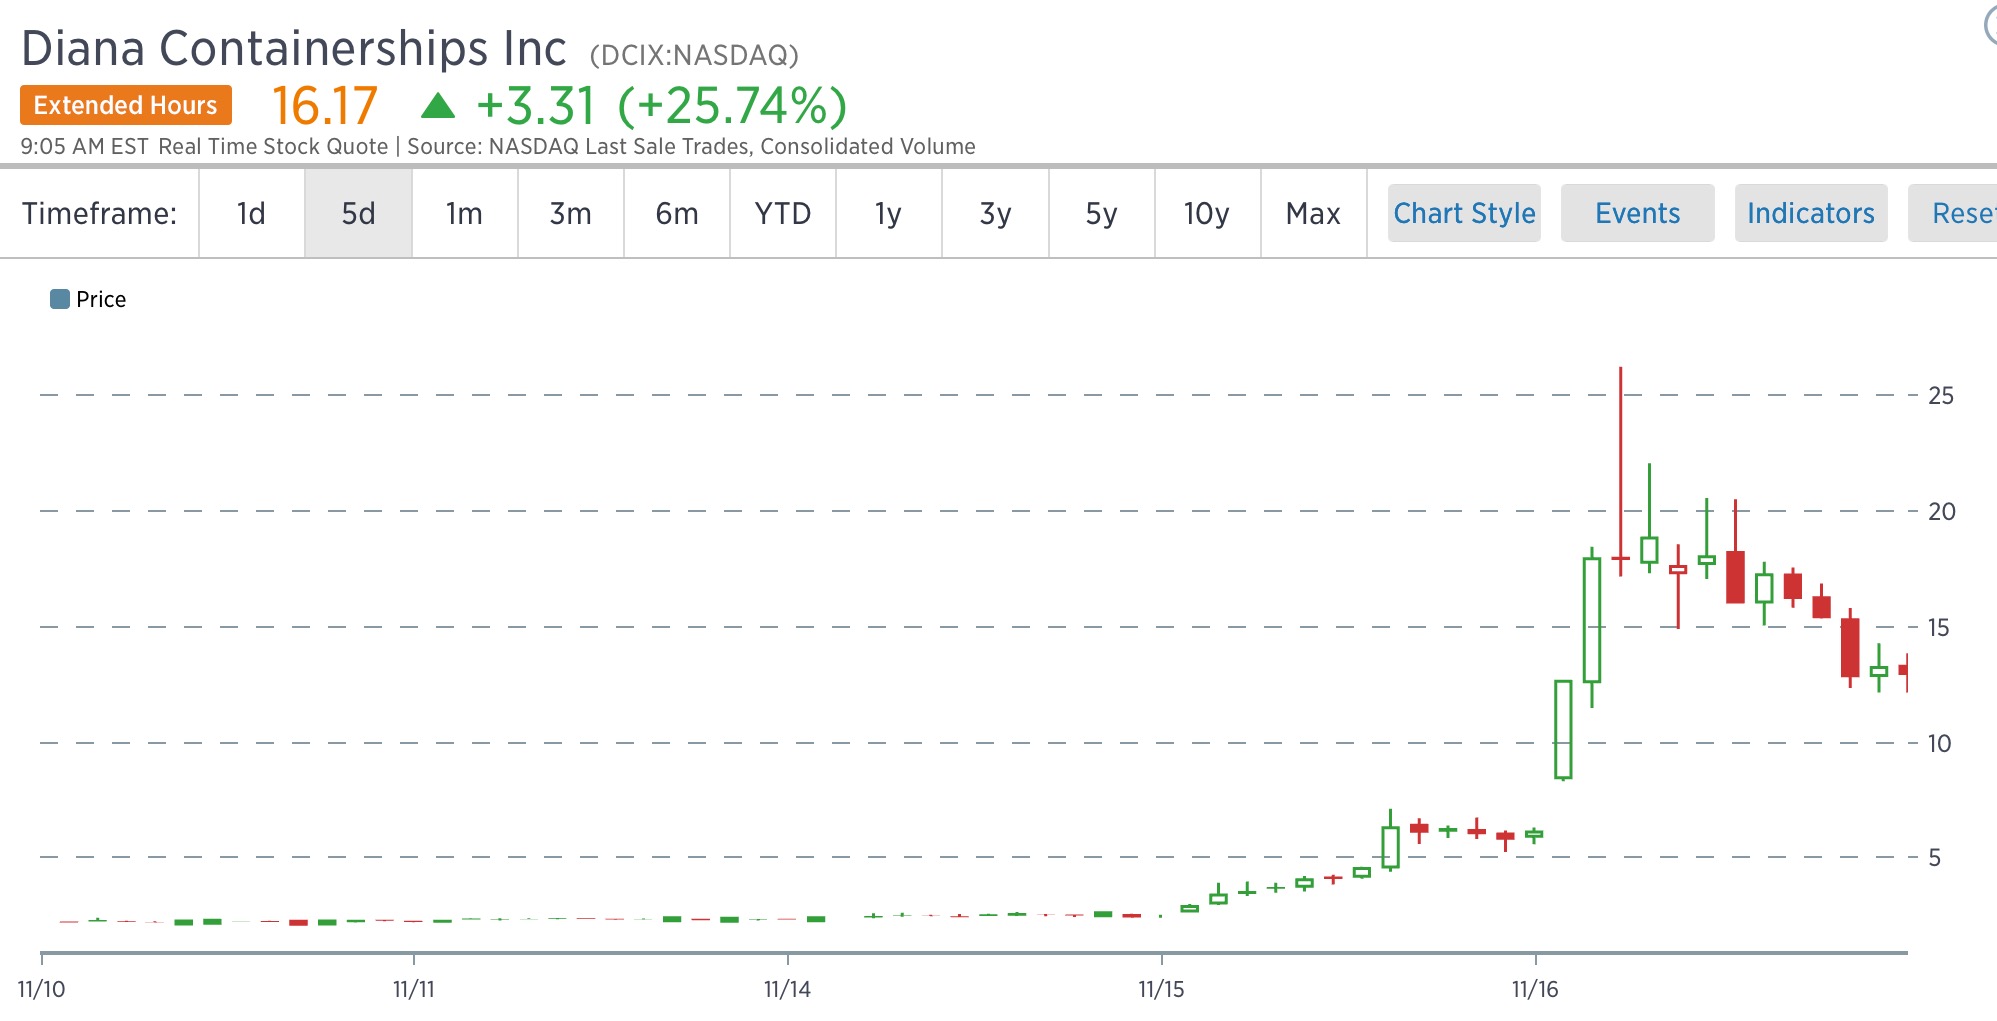
One of particular interest is DCIX. They just reported abysmal earnings and the stock is ripping higher because of it. The stock has lifted from $2 to $16 over the past five days.

img_5647

Reports Q3 (Sep) loss of $13.84 per share, includes charges, may not be comparable to the single analyst estimate of ($0.78); revenues fell 50.3% year/year to $8 mln vs the $8.1 mln single analyst estimate

The loss for the third quarter of 2016 was mainly the result of $118.9 million of impairment charges for seven of the co’s vessels, without which the result for the quarter would have been a net loss of $7.9 million

Time charter revenues, net of prepaid charter revenue amortization, were $8.0 million for the third quarter of 2016, compared to $16.1 million for the same period of 2015, mainly due to reduced employment opportunities and time charter rates
Time charter equivalent (TCE) rate was $5,977/day in the quarter, well below last year’s quarter of $12,654/day
Meanwhile, daily vessel operating expenses for the quarter were $6,620/day vs. last year’s quarter of $7,314/day

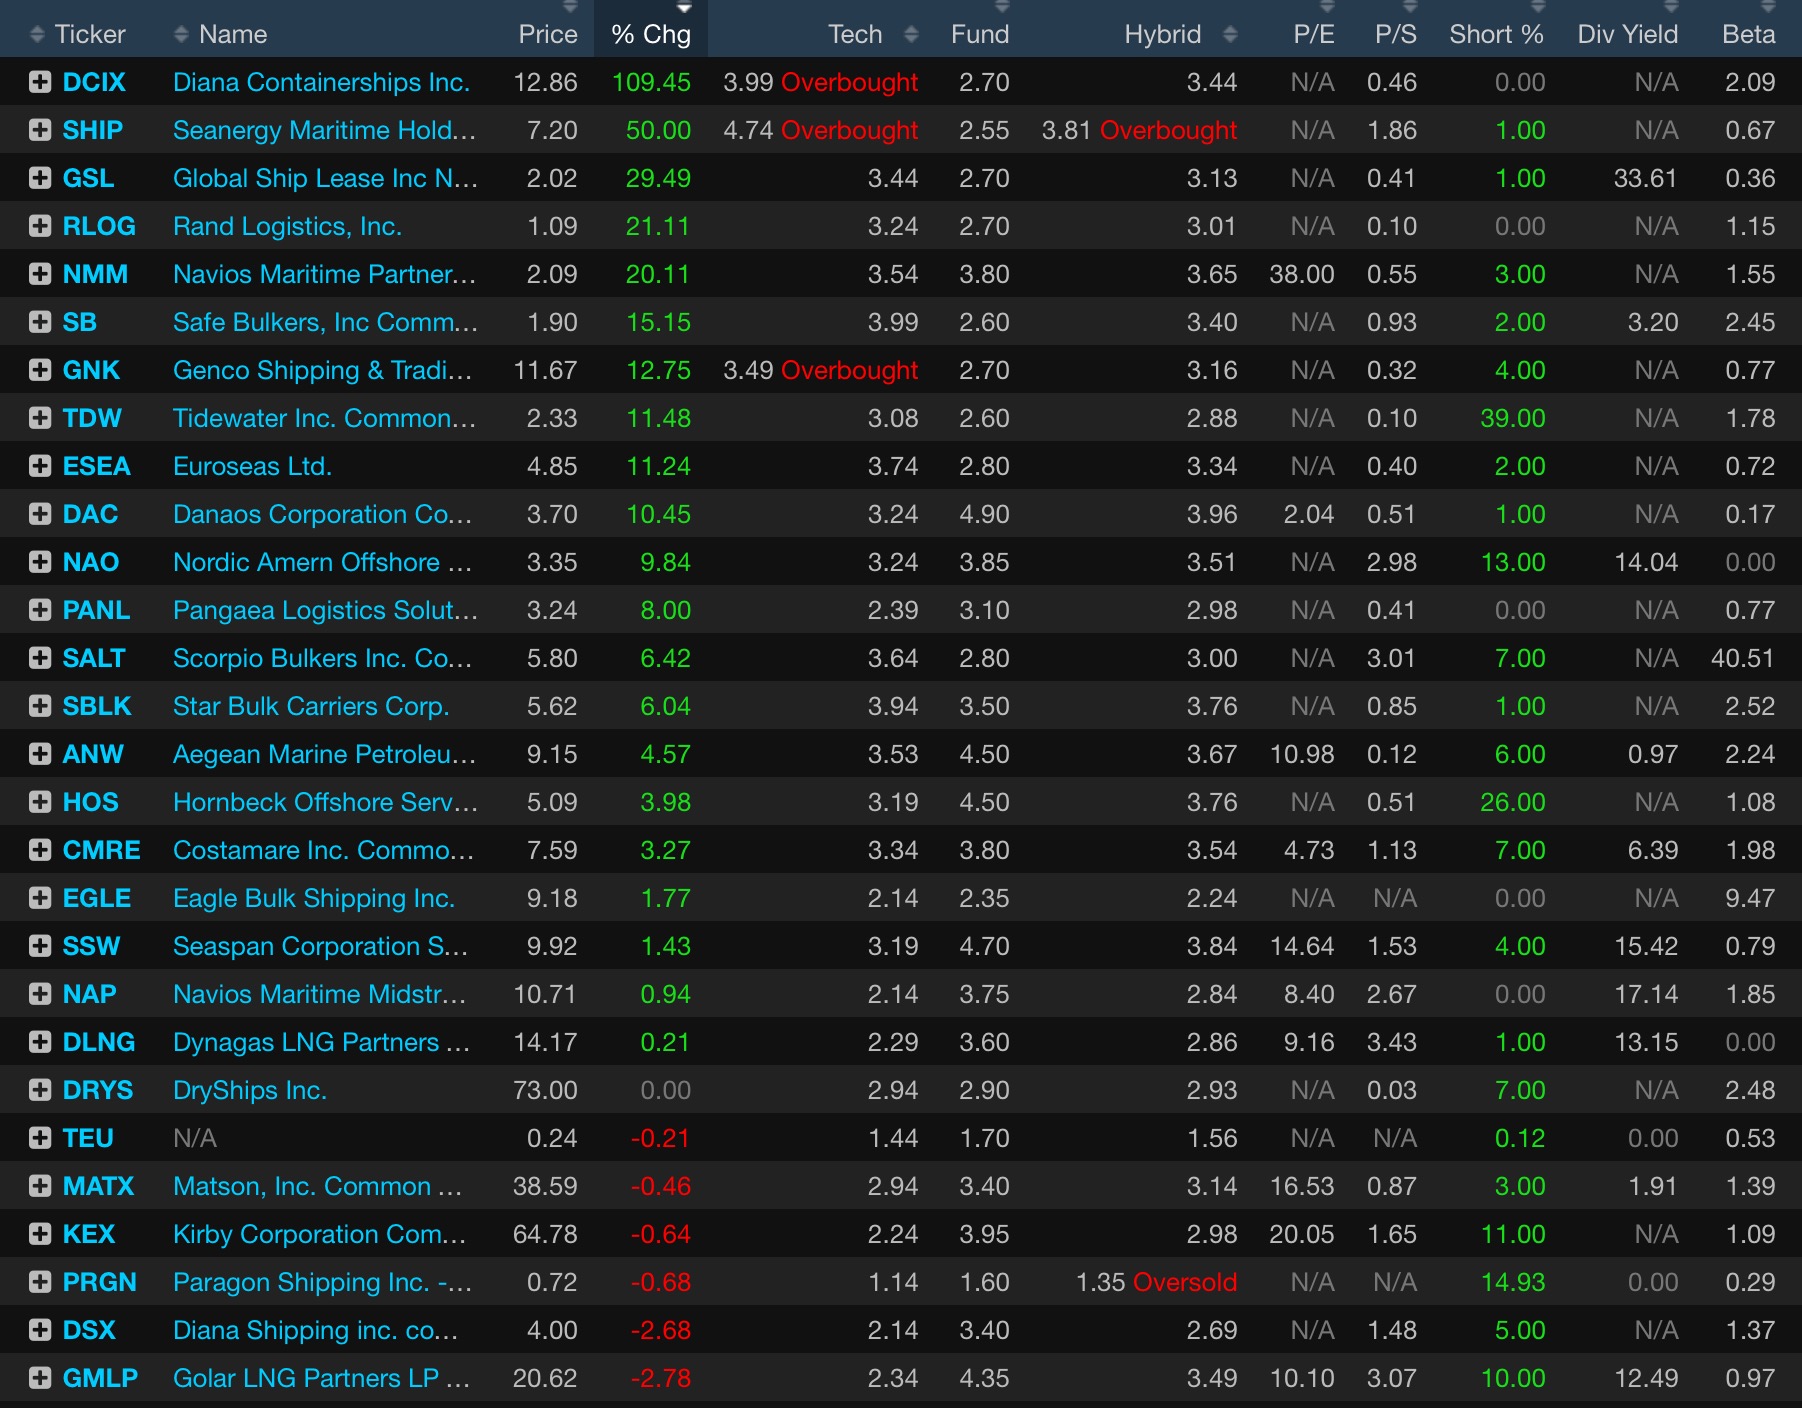
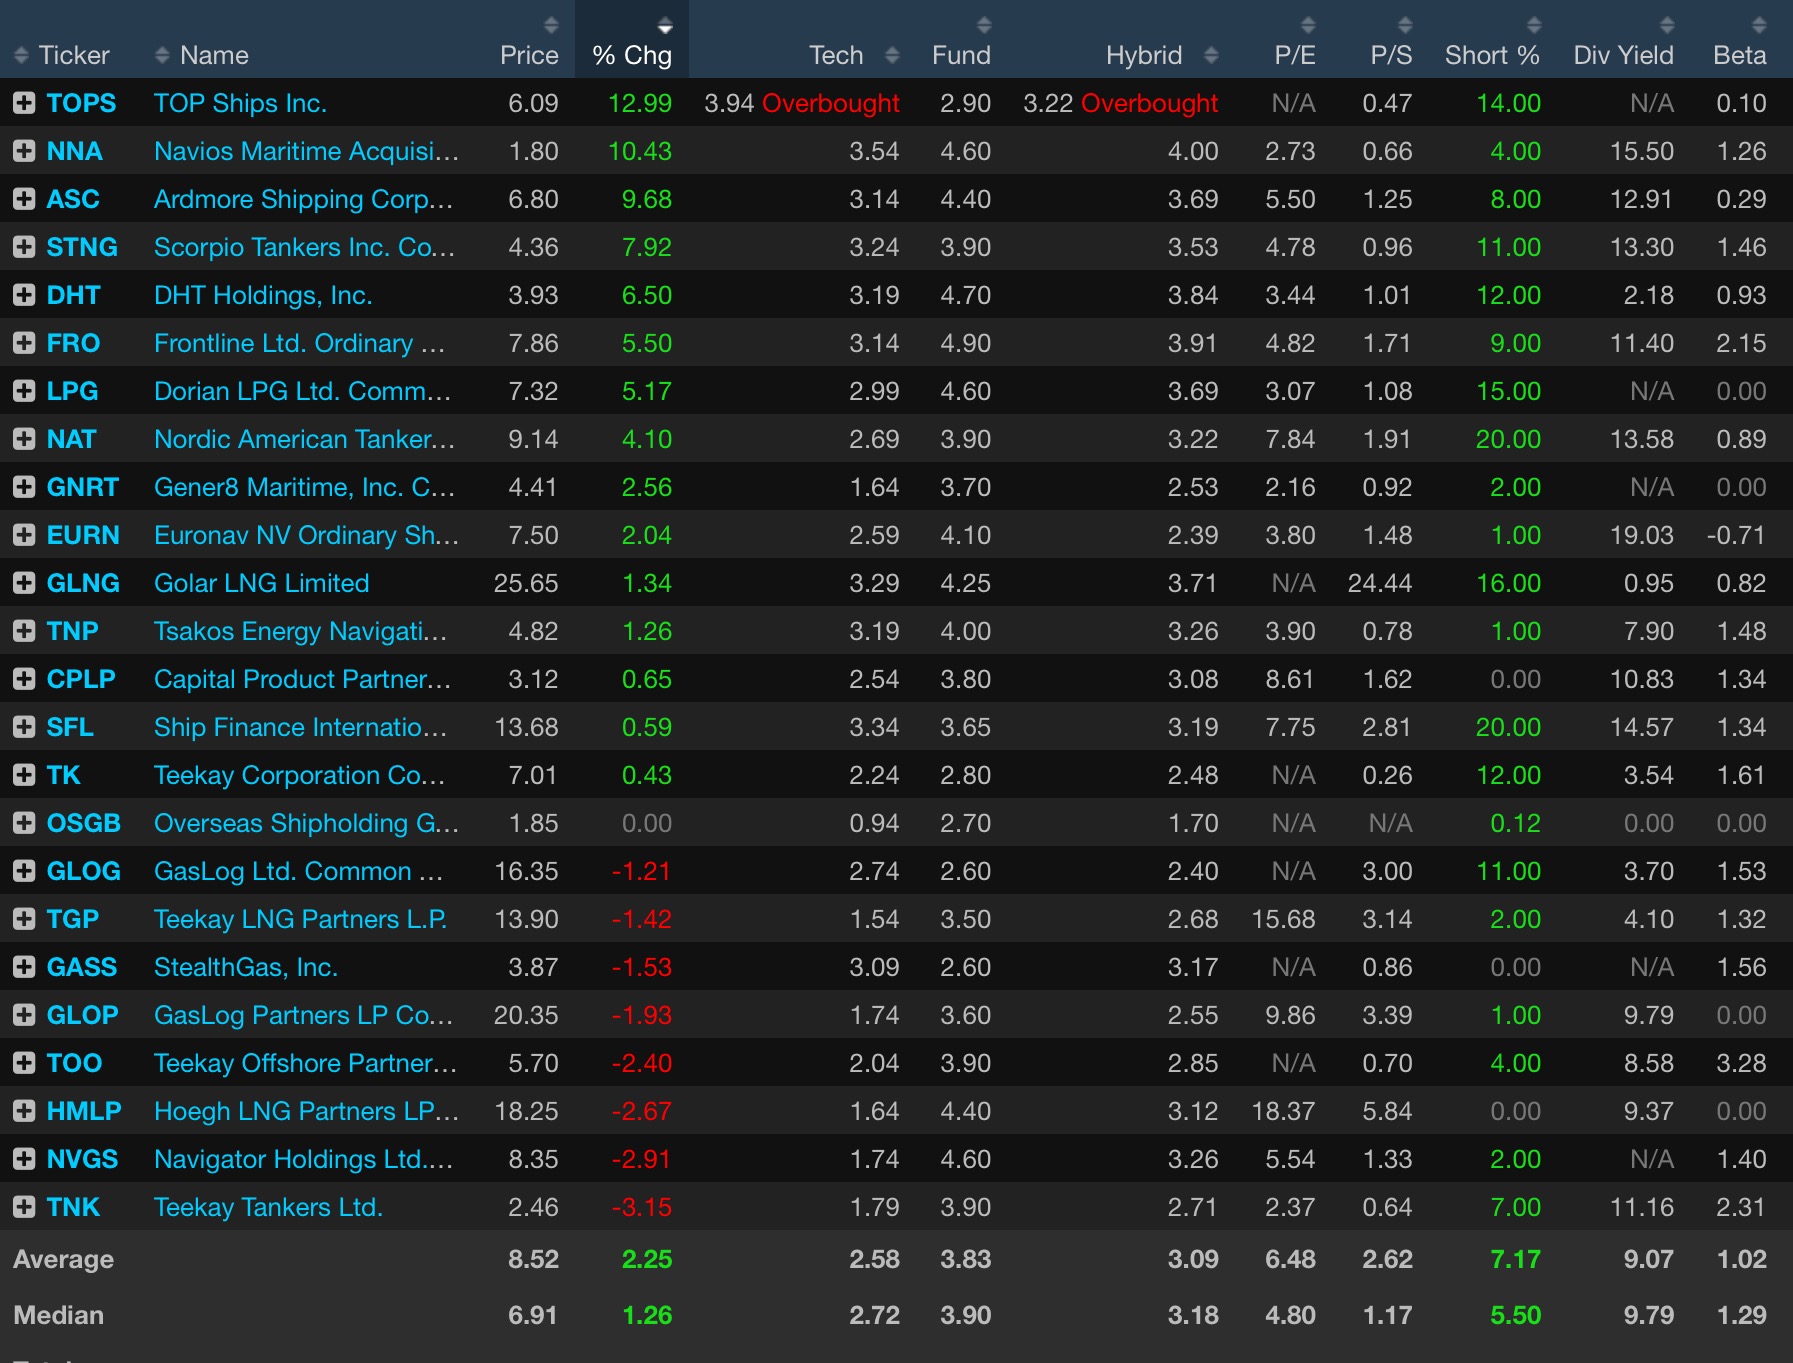
Via Exodus, here’s the full list of shippers. Below them are the tankers, in the event this idiocy spreads to that disheveled sector too.

img_5649

img_5650

Comments »

REJOICE and BEHOLD: A Deluge of Better Than Expected Data Just Hit the Tape

Wall Street is yawning off a slew of better than expected rigged data out this morning, painting an effervescent economy that is fair and equitable to all and booming like a motherfucker.

CPI is running hot, to the point of  needing immediate Fed hikes. Also, housing starts have, all of a sudden, skyrocketed. Be sure to log into Zillow today: I’m quite sure the value of your home is flat to down in spite of these marvelous numbers.

Lastly, the Philly Fed came in better than expected as well — which is actual evidence that the renaissance is upon you. Do not listen to fake news sites that tell you otherwise.

Thank you.

October Headline CPI +0.4% vs +0.4% Briefing.com consensus, Core CPI M/M +0.1% vs +0.2% Briefing.com consensus

October Building Permits 1229K vs 1200K Briefing.com consensus; Prior 1225K

October Housing Starts 1323K vs 1178K Briefing.com consensus; prior revised to 1054K from 1047K

Initial Jobless Claims 235K vs 257K Briefing.com consensus; Prior 254K

November Philadelphia Fed 7.6 vs 7.0 Briefing.com consensus

Comments »

YELLEN: RATES ARE GOING UP RIGHT AWAY, SAYS DELAY COULD CAUSE ‘EXCESSIVE RISK TAKING’

Good God, what in the world is she talking about now? Yellen is saying rates must be hiked now, in order to stave off excessive risk taking and financial instability? Where has she been for the past 4 years of QE fueled idiocy in the markets — starring one blown up VC funded IPO after the next?

But now that Trump is about to take over, she’s gonna get very serious about rigged markets and will make sure the Fed cools things down. After all, inflation is such a concern for the every day working blue collar’d American steel factory fuckhead of a worker. Right? Yes?

“Were the FOMC to delay increases in the federal funds rate for too long, it could end up having to tighten policy relatively abruptly to keep the economy from significantly overshooting both of the Committee’s longer-run policy goals,” Yellen said. “Moreover, holding the federal funds rate at its current level for too long could also encourage excessive risk-taking and ultimately undermine financial stability.”

img_5646

While stating the case for an imminent hike, Yellen also repeated her pledge that subsequent hikes will come at a gradual pace. Critics have worried that the Fed has missed opportunities to normalize policy, but Yellen said “the risk of falling behind the curve in the near future appears limited, and gradual increases in the federal funds rate will likely be sufficient to get to a neutral policy stance over the next few years.”

Yellen said the economy is making progress toward the Fed’s goals of maximum employment and price stability but still “has a bit more room to run.” Inflation is running faster and GDP growth has picked up as well, though business investment remains soft and consumer spending is posting moderate gains.

Comments »

Shares of $BBY Soar to Fresh 52 Week Highs on Earnings Beat and Raise

This bodes well for the retail landscape this holiday season. And, in spite of Samsung, Best Buy is guiding higher. The stock hasn’t been this awesome since 2007, when Tom Tom GPS devices were all the rage.

img_5645

Reports Q3 (Oct) earnings of $0.62 per share, excluding non-recurring items, $0.15 better than the Capital IQ Consensus of $0.47; revenues rose 1.4% year/year to $8.95 bln vs the $8.85 bln Capital IQ Consensus.

Comps +1.8% vs. +1% guidance.

Domestic revenue of $8.2 billion increased 1.3% versus last year driven by comparable sales growth of 1.8%, partially offset by the loss of revenue from 14 large format and 23 Best Buy Mobile store closures. Industry revenue in the NPD-tracked categories declined 3.1%.4

From a merchandising perspective, comparable sales growth in home theater, mobile phones, wearables and connected home was partially offset by declines in gaming.

Domestic online revenue of $881 million increased 24.1% on a comparable basis primarily due to increased traffic, higher average order values and higher conversion rates. As a percentage of total Domestic revenue, online revenue increased 200 basis points to 10.8% versus 8.8% last year.

Domestic GAAP and non-GAAP gross profit rate was 24.7% versus 24.1% last year. The 60-basis point increase was primarily due to improved margin rates in the computing and home theater categories, which were partially offset by the mobile category.
Co issues mixed guidance for Q4, sees EPS of $1.62-1.67, excluding non-recurring items, vs. $1.58 Capital IQ Consensus Estimate; sees Q4 revs of $13.4-13.6 bln vs. $13.7 bln Capital IQ Consensus; comparable sales change in the range of (1.0%) to 1.0% vs. ests near +1.2%; domestic comparable sales change in the range of (1.0%) to 1.0%; International comparable sales change in the range of (2.0%) to 2.0%

“From a revenue standpoint, we are excited by the rate of technology innovation, the quality of our assortment and our ability to execute. That being said, we have updated our original expectations to incorporate the impact of recent product recalls and the fact that certain products will simply not be available for sale during our fourth quarter. The expected impact of these recalls on our fourth quarter Domestic revenue is ~$200 million.”

UPDATE via Briefing.com, notes from call

In store traffic unchanged while ticket and online traffic is up.

Excited about product innovation.

Vendor partnerships continue to benefit the company.

Gross margin strength computing and home theater categories, which were partially offset by the mobile category.

Best Buy is doing well at the high end of the TV/home entertainment space as co offers the best customer experience in terms of offerings and service.

Lower ASP with great products/innovations: 4K, OELD — driving consumer interest.

Streaming devices also doing well.

Computing industry not necessarily doing great but co’s assortment and exclusive offerings/partnerships are a very important strength; MSFT/AAPL

Strength in mobile (iPhone) offset by Samsung recall; AT&T/VZW store within stores growing

iPhone in-line with expectations, not as strong as 6 but better than 6S last year; ability to buy from multiple carries helps supply.

Appliances +3% vs. +16% last year, slowed late in quarter due to Samsung recall and inventory constraints; continuing to gain material market share.

Home automation, drones and VR doing well but still early.
Continues to experimenting with new features to enhance customer service — e.g. in home advisory pilot.

Promotional activity will not be subdued for the holiday this year. Sees Q4 gross margin flattish to slightly higher Y/Y; slightly positive service comps.

Comments »

End of an Era: $TSO Swallows $WNR Whole for $37

In a perfect world, this deal should be permitted to occur. But now that the EPA is literally a holding pen for future unemployed cucks, TSO thinks they have a license to steal from the American people. As such, they’re acquiring one of their few competitors, WNR, for $37.30 per share.

In my opinion, this borders on monopoly and the government should tell them to eat a bag of dicks, instead of swallowing WNR. But the Trump administration isn’t likely to be monopoly unfriendly and will let this deal get down. Bear in mind, Trump is all about getting deals done. The more deals the better.

I could really veer off the reservation very easily now, going heavy into this bitch of a deal; but that’d be selfish of me. Trump is a true American and anything I assume about his administration now is pure conjecture, making me no worse than all of you fruit basketed retards.

Many of you know my fondness to WNR, with it being my largest holding several times during my wasteful career as a manager of money. An end of an era is upon you; the WNR has been acquired.

Tesoro Corporation (TSO) and Western Refining jointly announced a definitive agreement under which Tesoro will acquire Western at an implied current price of $37.30 per Western share in a stock transaction, representing an equity value of $4.1 billion based on Tesoro’s closing stock price of $85.74 on November 16, 2016. This represents an enterprise value of $6.4 billion, including the assumption of approximately $1.7 billion of Western’s net debt and the $605 million market value of non-controlling interest in Western Refining Logistics, LP (WNRL).

The acquisition is expected to create a premier, highly integrated and geographically diversified refining, marketing and logistics company and provides a strong platform for earnings growth and cash flow generation.

Under the terms of the agreement, Western shareholders can elect to receive 0.4350 shares of Tesoro for each share of Western stock they own, or $37.30 in cash per share of Western stock. Elections to receive cash will be subject to proration to the extent they exceed approximately 10.8 million shares (or approximately $404 million in the aggregate). Stock elections will not be subject to proration. The purchase price represents a premium of 22.3% to the closing price of Western’s stock on the day prior to announcement, and a 31.6% premium to the volume weighted average price over the last 30 trading days. The transaction is expected to be tax-free to Western’s shareholders who elect stock.

Expected benefits of the transaction:
Shareholders of both companies will benefit from $350 to $425 million in operational, commercial and corporate synergies.
Expects to achieve 10% to 13% EPS accretion in 2018, the first full year of combined operations

Upon closing, Tesoro will continue to have a strong balance sheet and credit metrics, and will remain on track for achieving an investment grade credit rating. The Company has increased its share repurchase authorization by $1.0 billion to over $2.0 billion in total. Tesoro expects to maintain its current quarterly dividend of $0.55 per share (or $2.20 per share annualized) after closing and is focused on growing dividends commensurate with the growth of the Company.

Comments »