iBankCoin
Home / 2016 (page 138)

Yearly Archives: 2016

Art Cashin: You Should Worry About Oil

In spite of what the Commodity King said earlier today, the iced cube marinator in Chief, Art Cashin, believes you should be exceedingly wary about the prospects for crude oil, as it delves lower on a daily basis.

The truth is, as you can see by the market rallying, NO ONE GIVES A SHIT, ARTHUR.

Back to your regularly scheduled cocaine rally, ya’ll.

Comments »

Greenspan Warns Policy Makers of Economic Dangers, But No One is Listening

Alan Greenspan is a very old and a very smart man. Perhaps he’s had some time to reflect upon the grave dangers that his Federal Reserve policies placed upon the American economy. He’s been warning about entitlements and lack of investment for years now, but no one is listening.

Isn’t it amazing that we have people running this country who believe it’s okay to run up deficits year in and out, without ever thinking about the future? The hand outs are endless. The more people get, the more they want. Higher taxes for lower productivity. It’s a recipe for madness and failure.

Aside from that, Greenspan is concerned that stagnation might morph into stagflation. Should that occur, we’d be truly fucked.

Old man Greenspan is whistling in the wilderness.

Comments »

Dennis Gartman: There Is No Correlation Between the Price of Oil and Stocks

D. Gart is out talking greasy this morning, suggesting that the great oil boom of the past decade, when investors financed and helped leverage up nefarious wildcatters in the hope of cashing in on expensive $100+ crude prices, due to war and fuckery, is meaningless drivel now that oil has collapsed. In other words, D. Gart doesn’t believe there is a debt storm around the bend, in spite of the balance sheet numbers that suggest a solid $600 billion is teetering on distressed levels.

Because there isn’t a debt bubble in crude, Gartman thinks you should all shut the fuck up about a nonsensical correlation between crude and stocks–because he has charts from the 1980’s and 90’s (pre-bubble era) suggesting otherwise. When asked about whether the price of crude going lower might scare people into believing global growth was at risk, D. Gart quickly reversed his opinion and acquiesced to that logic.

Comments »

Wall Street Isn’t Buying What $WFM is Selling

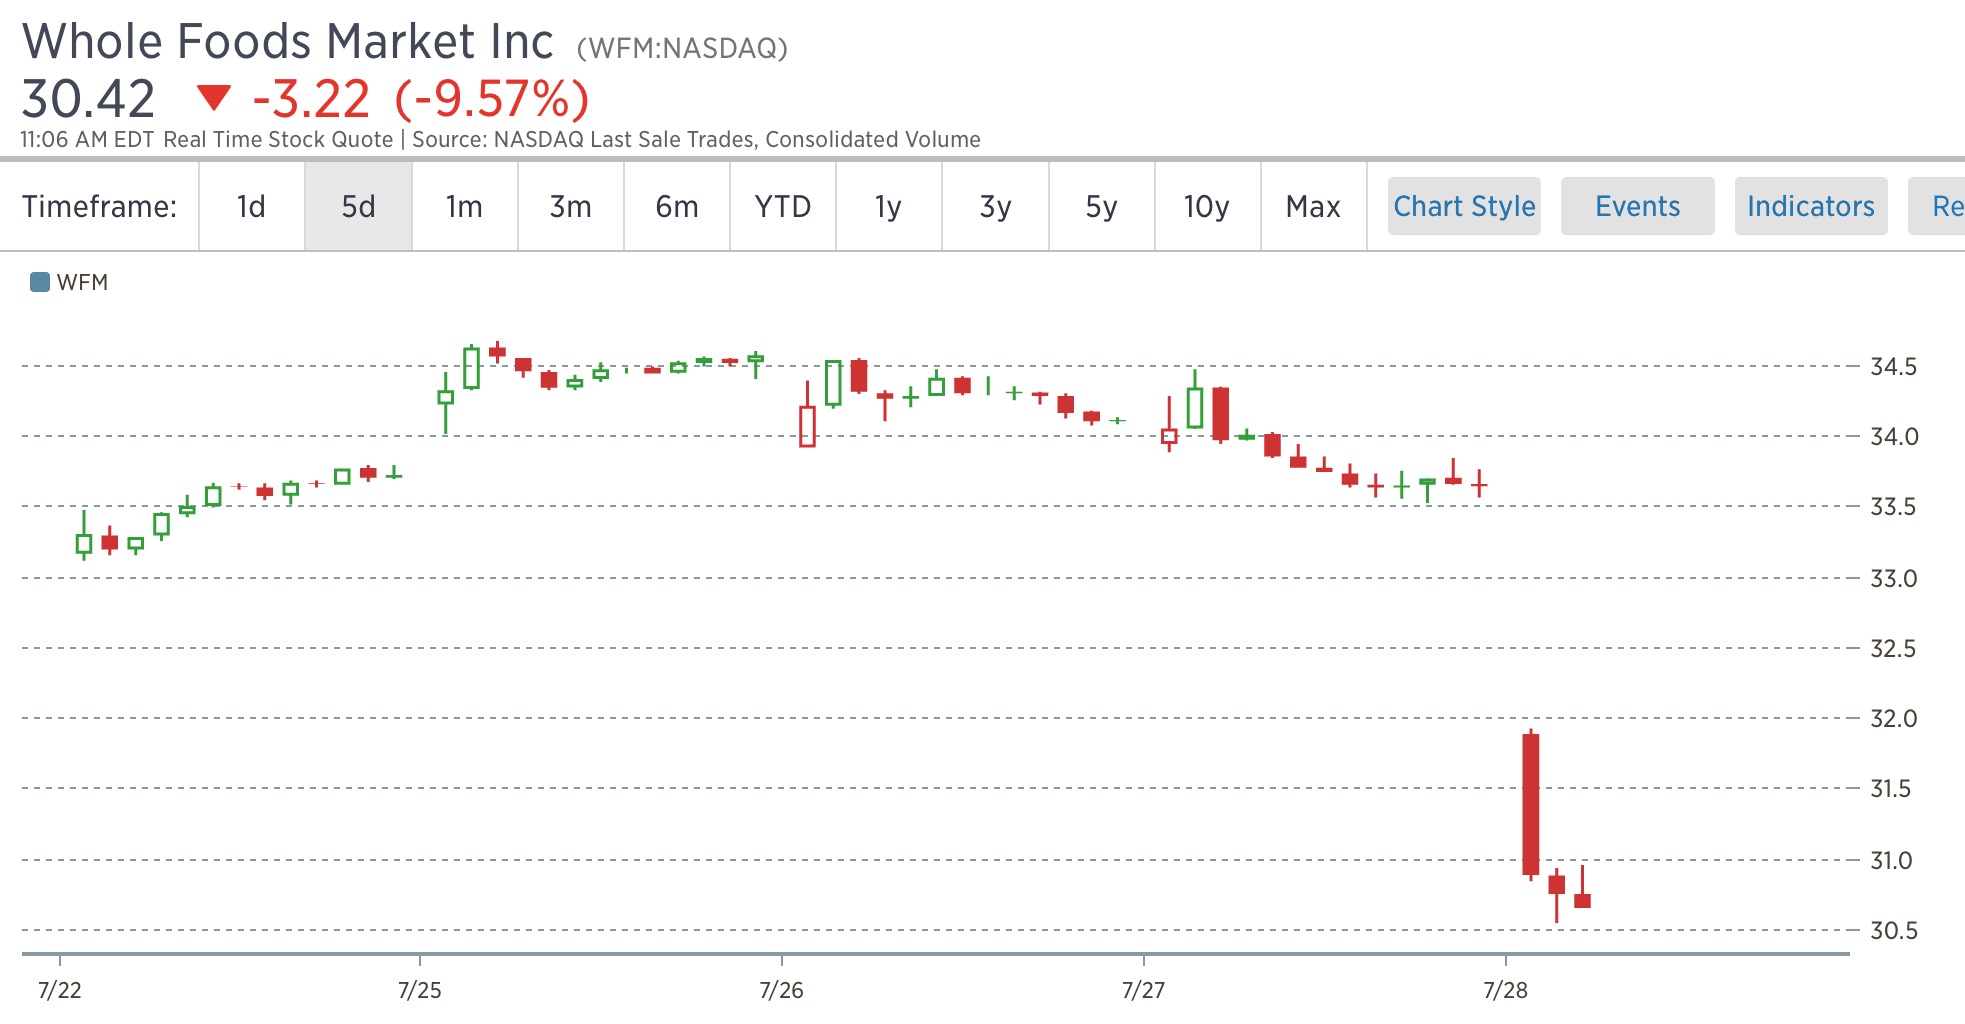
Remember when Whole Foods was a special place? It was a respite from the God foresaken Foodtowns and Pathmarks of the world. But the world caught up to Whole Foods and now the innovator is becoming the imitator of lesser brands. In this case, I am speaking of Whole Foods’ 365 niche store concept, an obvious rip off from Trader Joe’s.

I like TJ; but everyone knows it’s s poor man’s WFM. The company is lost without a paddle. Wall Street isn’t buying what they’re selling and neither am I.

image

Analysts take.

TAG understands the co is actively attempting to reduce costs and restructure the business, but there has not been much improvement in sales despite a multi-year investment in price and traffic driving initiatives. The competitive environment remains intense, and Whole Foods is still searching for a solution. Traditional and other specialty grocers continue to encroach on Whole Foods’ niche, forcing the co to increase its investment in pricing and marketing, and seek growth beyond the core concept via its new “365” by Whole Foods banner. In addition, the shift toward online grocery and the need to invest to be relevant and differentiated in that space may weigh on earnings. Although Whole Foods seems to be doing the right thing by focusing on traffic-driving initiatives and reducing its cost structure, they need to see stabilization in same-store sales to believe that the co’s efforts are generating results.

Pivotal Research notes the most worrisome development about Whole Foods’ latest results is the continued sales deceleration heading into FY17. Two-year stacked comp trends declined from +0.6% in 2Q16 to -1.3% in 3Q16. They expect two-year stacked comps to take a further step back by 130 bps to -2.6% in 4Q. Against this backdrop of heavy gross margin investment and continued descent of Whole Foods’ sales trajectory, the potential for comps to remain negative in FY17 is now a real possibility. Currently, the consensus expectation is +1.5% for FY17 comps. By the time mgt. communicates its preliminary FY17 guidance in early November, they think there will be several more shoes to drop that could weigh on the earnings outlook for next year; Sell.

RBC notes that while QTD commentary fell below expectations, they believe Whole Foods relieved fears over the need to rebase earnings. With better earnings surety and unchanged (albeit weak) comp profile, near-term downside is limited. Their thesis is predicated on 365’s ability to tap into a previously unavailable growth engine. Legacy quarterly results, absent a sequential deceleration, do not shake that view.

Wedbush notes WFM’s 3Q16 performance was effectively in-line on impressive cost control and included encouraging commentary surrounding various initiatives including recent produce investments (beginning to improve basket sizes, traffic), but the company’s QTD comp trend decelerated again on a 2-year stack basis. While they see opportunities for WFM in FY17 as intriguing (new store concept, procurement, affinity program, POS initiatives), these factors may do little to offset near-term competitive concerns for investors and therefore still believe WFM shares will remain range bound.

Comments »

The Crude Story is Being Tarred and Blackened

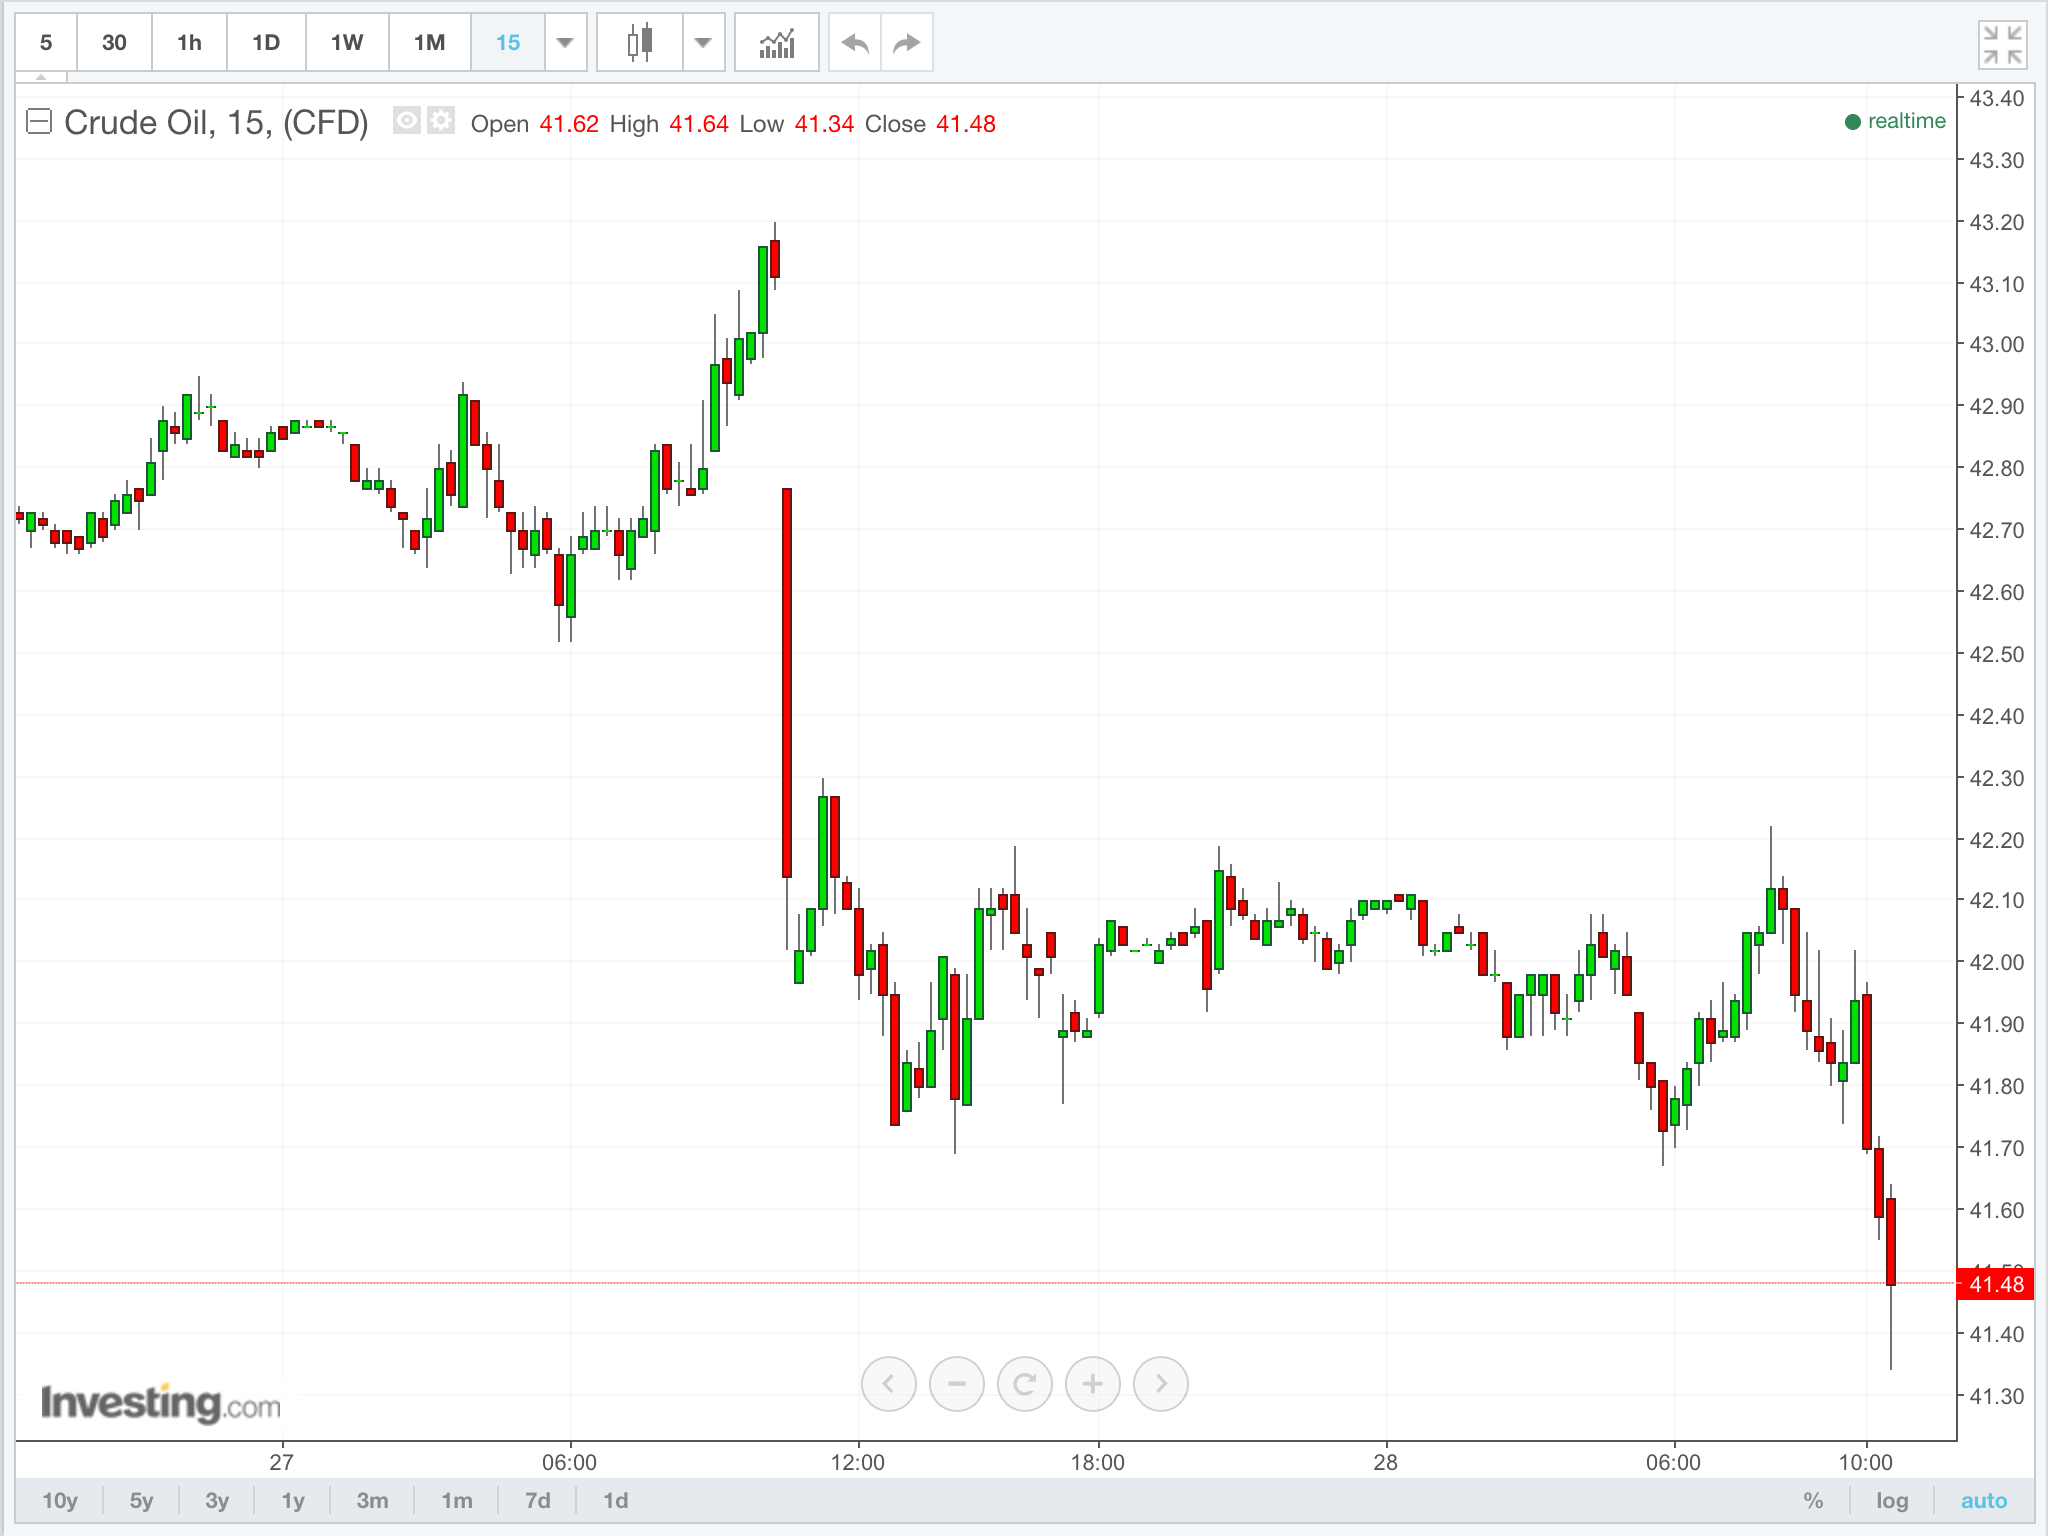
WTI is down another percent today, widening its losses to 14% over the past month. For the most part, oil stocks have stupidly ignored this horrendous price action and have traded like grocery store stocks.

The fuck out of here.

image

Down, down, down.

WLL and CLR are your coal mine canaries. The blood will flow, heavy and with ceaseless consistency. You’d be wise to liquidate your entire portfolio and go swimming in St. Bart’s, should crude break $40 to the downside.

Comments »

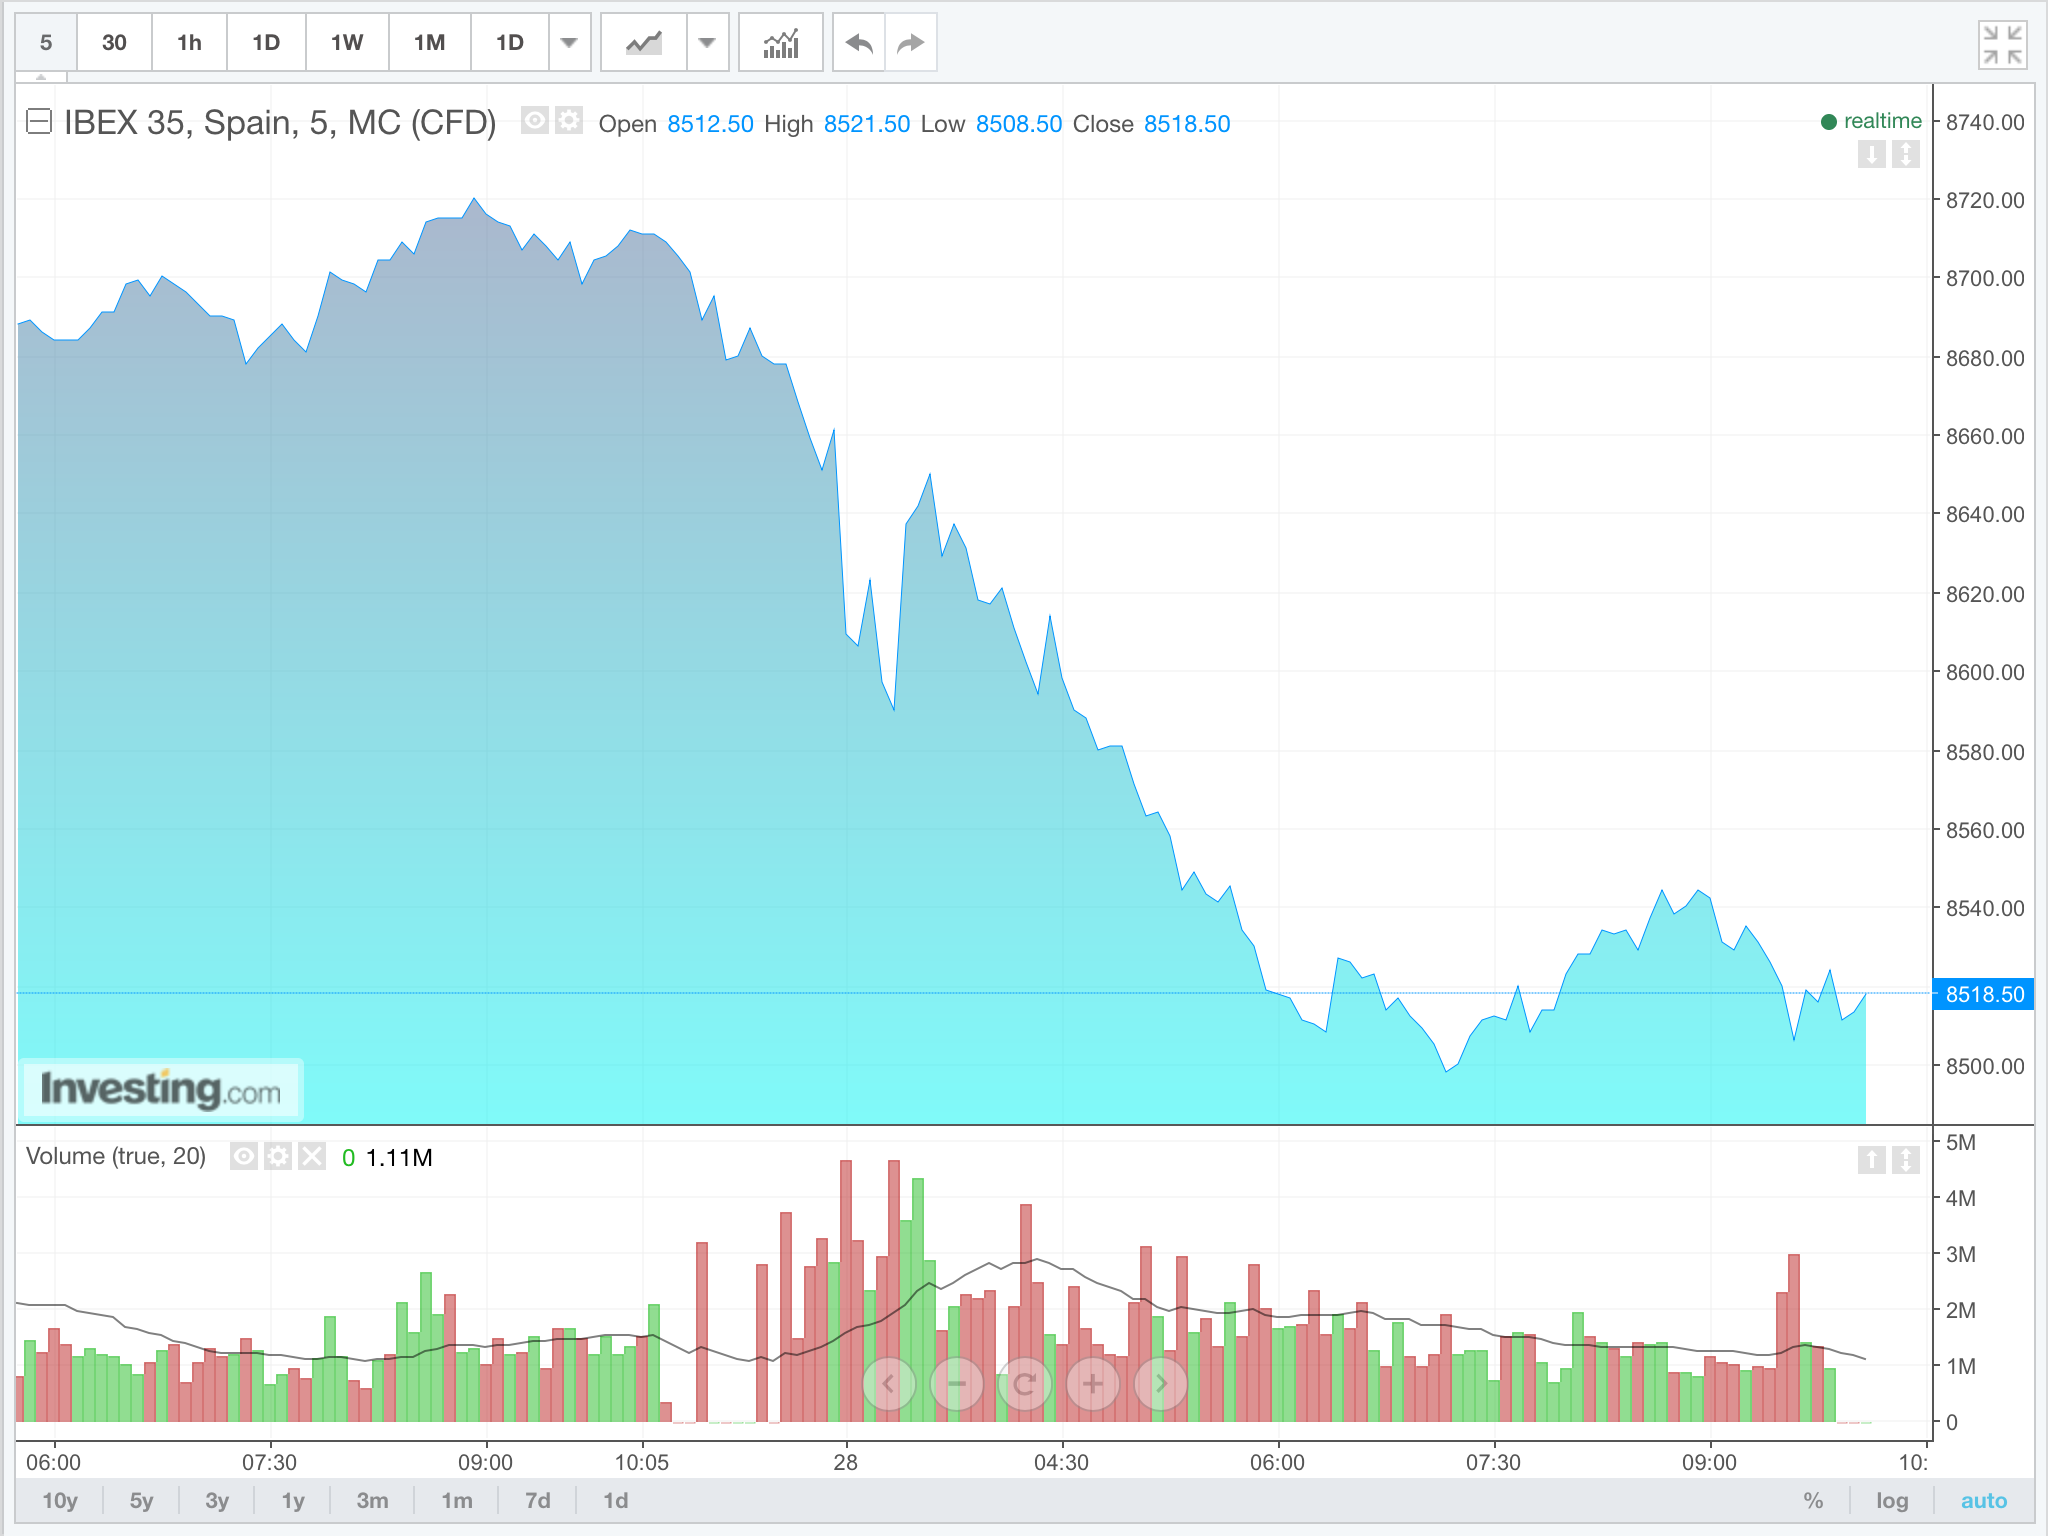
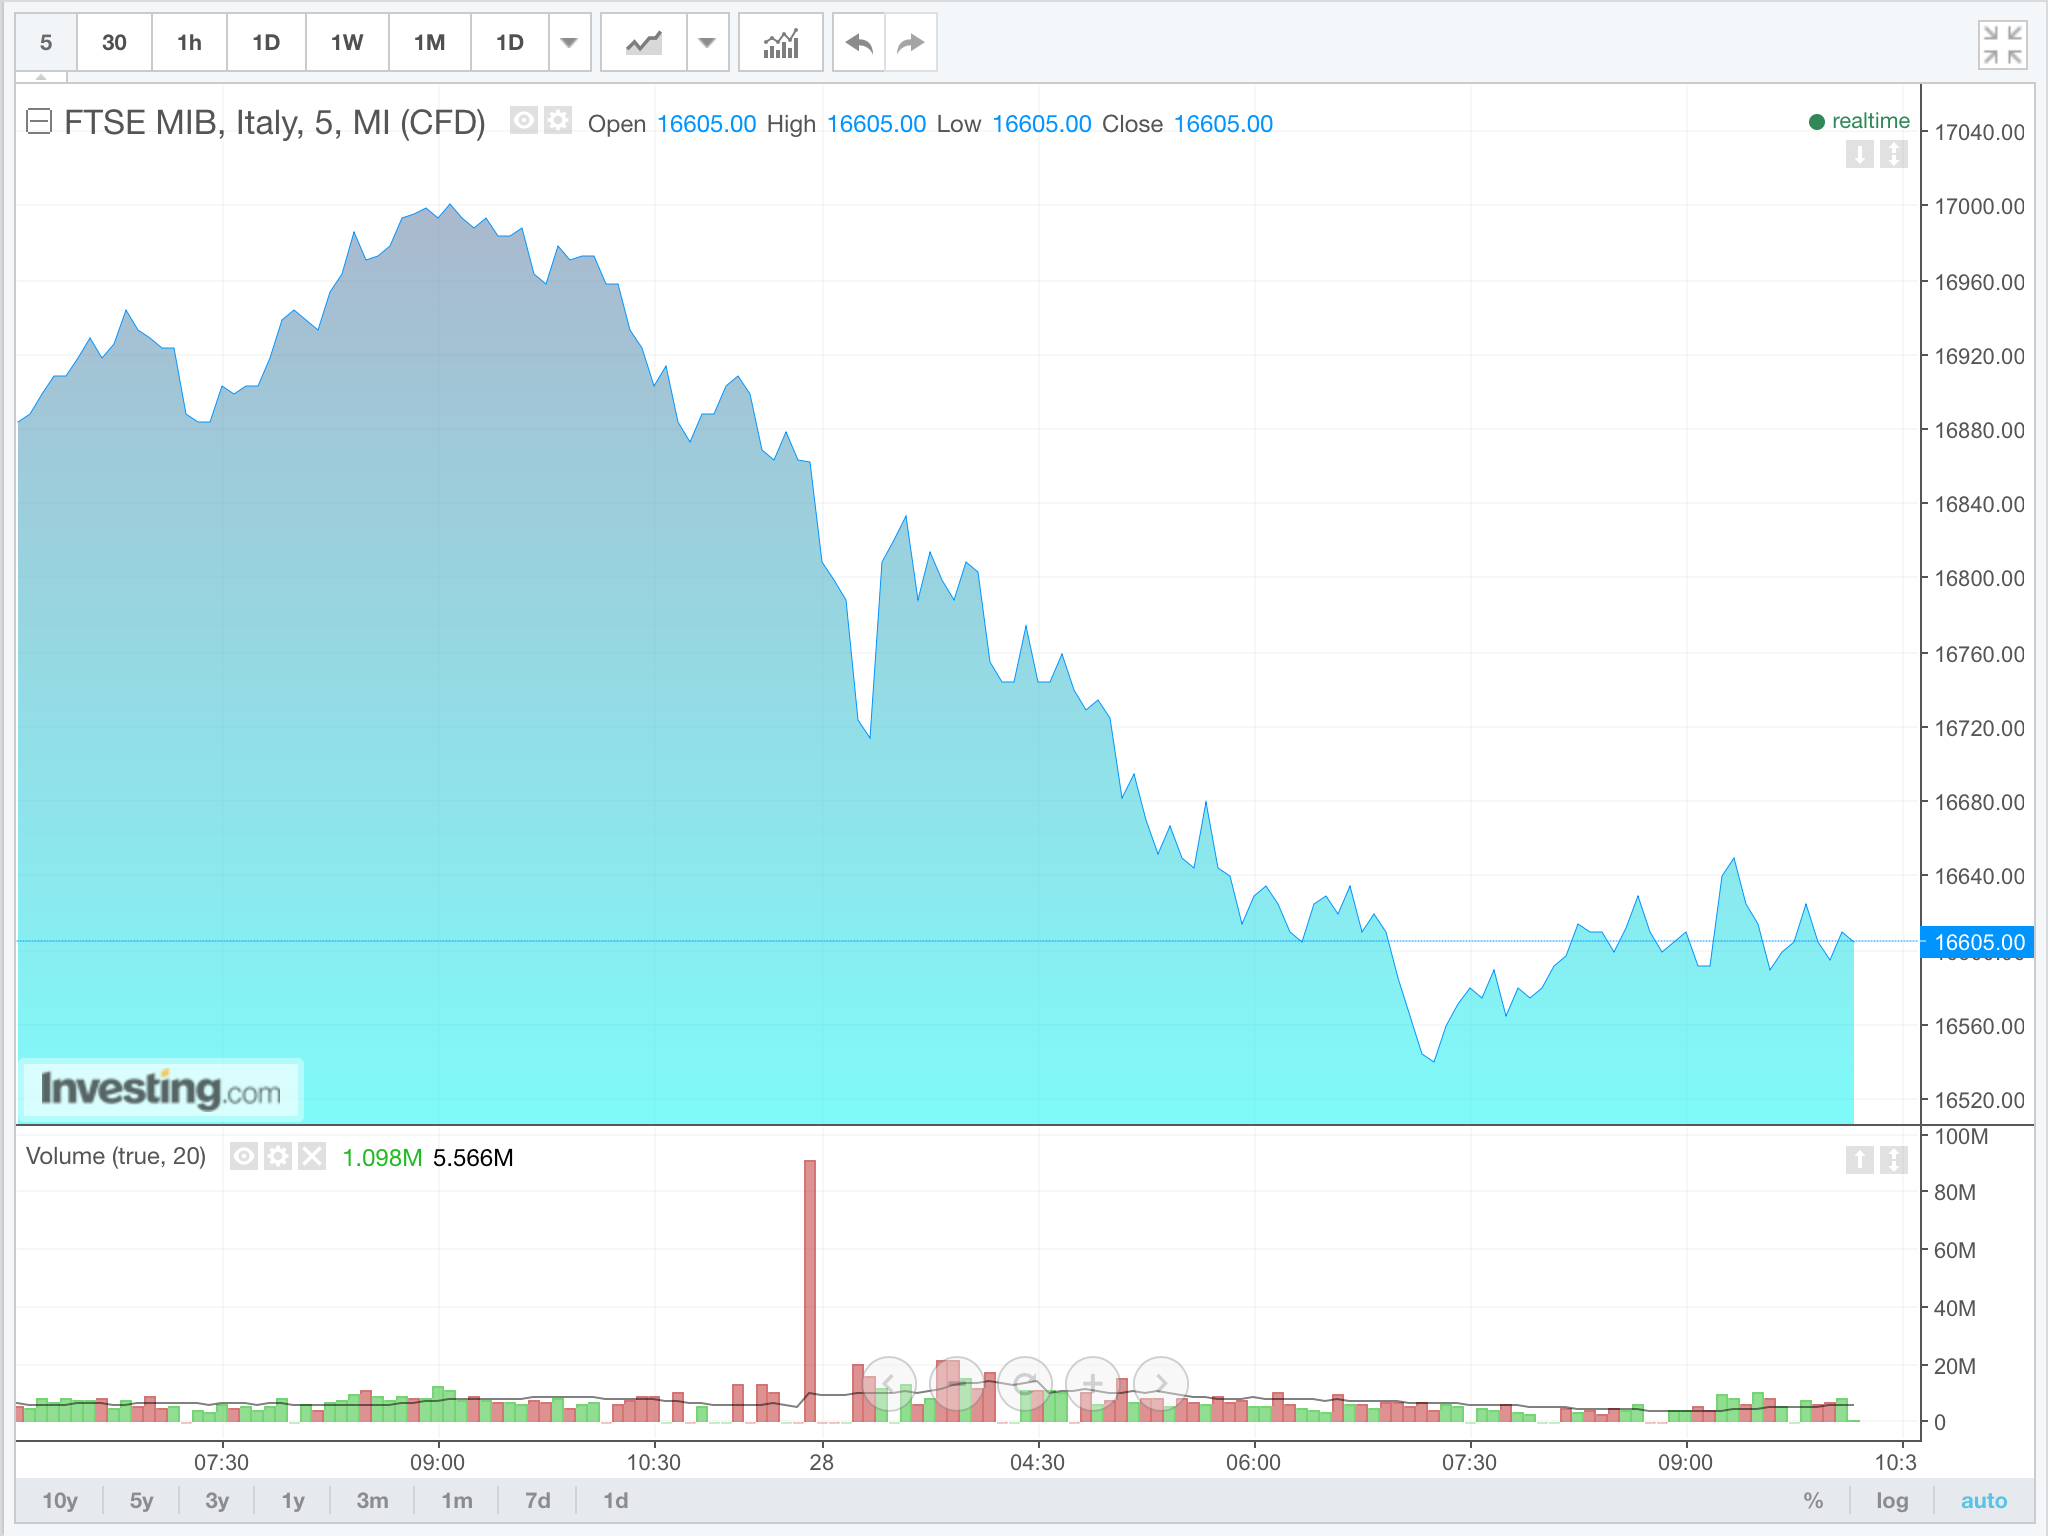
Italian and Spanish Markets Are Getting Rocked

I know, who cares about those latins? Truth is, the jingoistic mentality of this country could see our stocks rise amidst nuclear detonations in Europe. We’re at a point in this cycle that the gains are excessive to the point of madness.

It’s the sort of tape you chase. You get lured into the fray by a sundry of tantalizing moves, like FB, AAPL or even N and GRUB. We’re in the midst of a truly special time for stocks and I am going to make sure that I miss out on every single second of it.

Both Italy and Spain are down in excess of 1.5%, led lower by banks.

image

image

Unicredit is down 4% and about a dozen other banks are lower by 3%.

Comments »

Two Stocks to Own for Those Scared to Get Shot

Afraid to go outside of your housing tenements? That Taco John’s or Kansas Fried Turkey is looking real good, from your window view. If only you could get the food without having to risk going outside and possibly get robbed or shot.

Hey, we live in a very high tech world these days. It’s not like how we grew up in the 90s, playing games with numbers on our beepers. I read a report last week that stated restaurant stocks are weak (Extra Hillary) because people are afraid of the anarchy. The analyst said to buy PZZA. I like that play, and also DPZ. But it’s not the reason why I wrote this damned article.

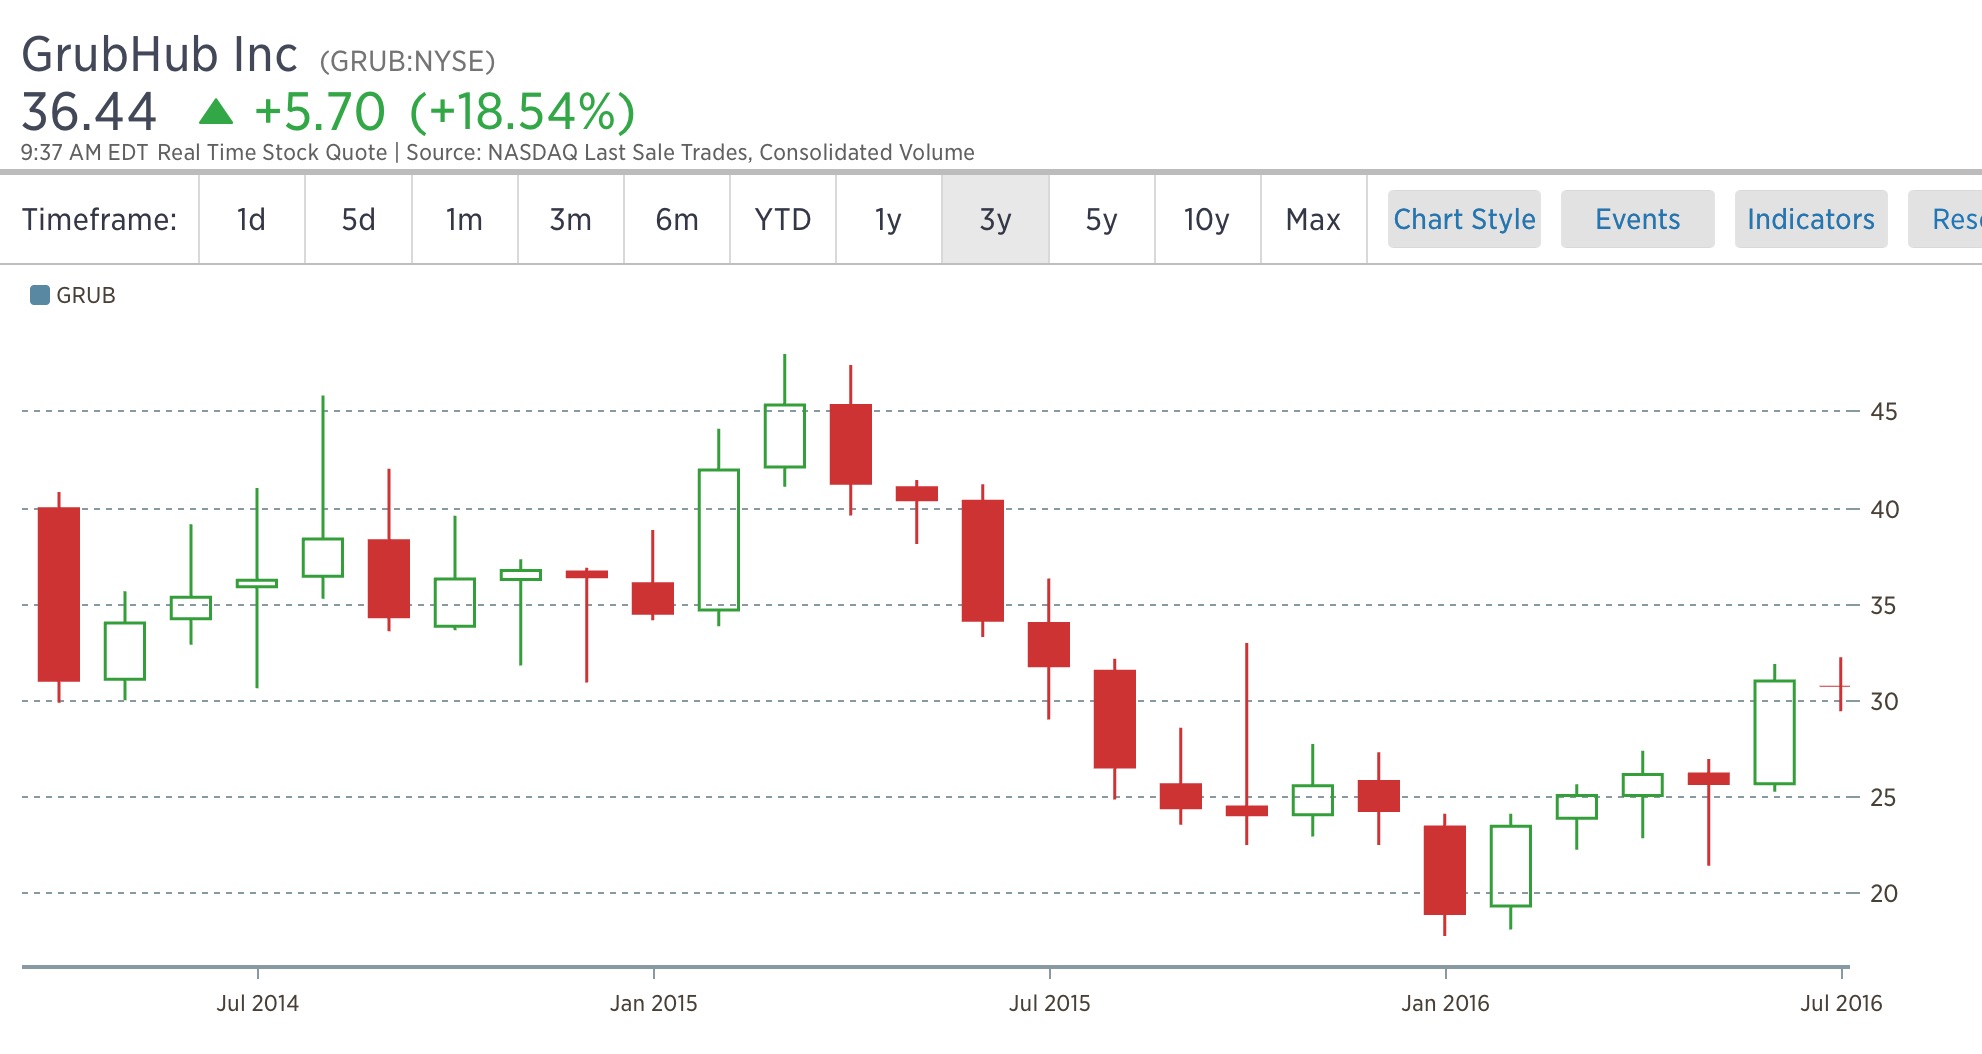
Order via your phones, jackasses. GRUB specializes in placating the coward and the sloth. They just crushed the quarter.

image

Reports Q2 (Jun) earnings of $0.23 per share, $0.04 better than the Capital IQ Consensus of $0.19; revenues rose 36.6% year/year to $120.2 mln vs the $114.25 mln Capital IQ Consensus. EBITDA $37.6 mln vs. $30-32 mln guidance.

Active Diners were 7.35 million, a 24% year-over-year increase from 5.93 million Active Diners in the second quarter of 2015. Daily Average Grubs were 271,100, a 23% year-over-year increase from 220,100 Daily Average Grubs in the second quarter of 2015.

Gross Food Sales were $733 million, a 29% year-over-year increase from $568 million in the second quarter of 2015.

Co issues upside guidance for Q3, sees Q3 revs of $116-119 mln vs. $113.82 mln Capital IQ Consensus; EBITDA $30-32 mln.
Co issues upside guidance for FY16, raises FY16 revs to $480-488 mln from $465-480 mln vs. $473.30 mln Capital IQ Consensus; raises EBITDA to $136-142 mln from $125-133 mln.

The other obvious play is YELP. It’s one of my go to apps. As a food and a very brave man, I enjoy the many luxuries that YELP affords me. They also have an order in feature, which of course caters to the dystopian world we’re delving into.


Comments »

Ellison Finally Acquires $N for $109, All Cash Offer

This has been to most widely talked deal in the history of deals. I recall reading about a possible deal a decade ago. I used to own a large amount of N and always liked the company. As a matter of fact, I believe software stocks are the best speculative investments out there.

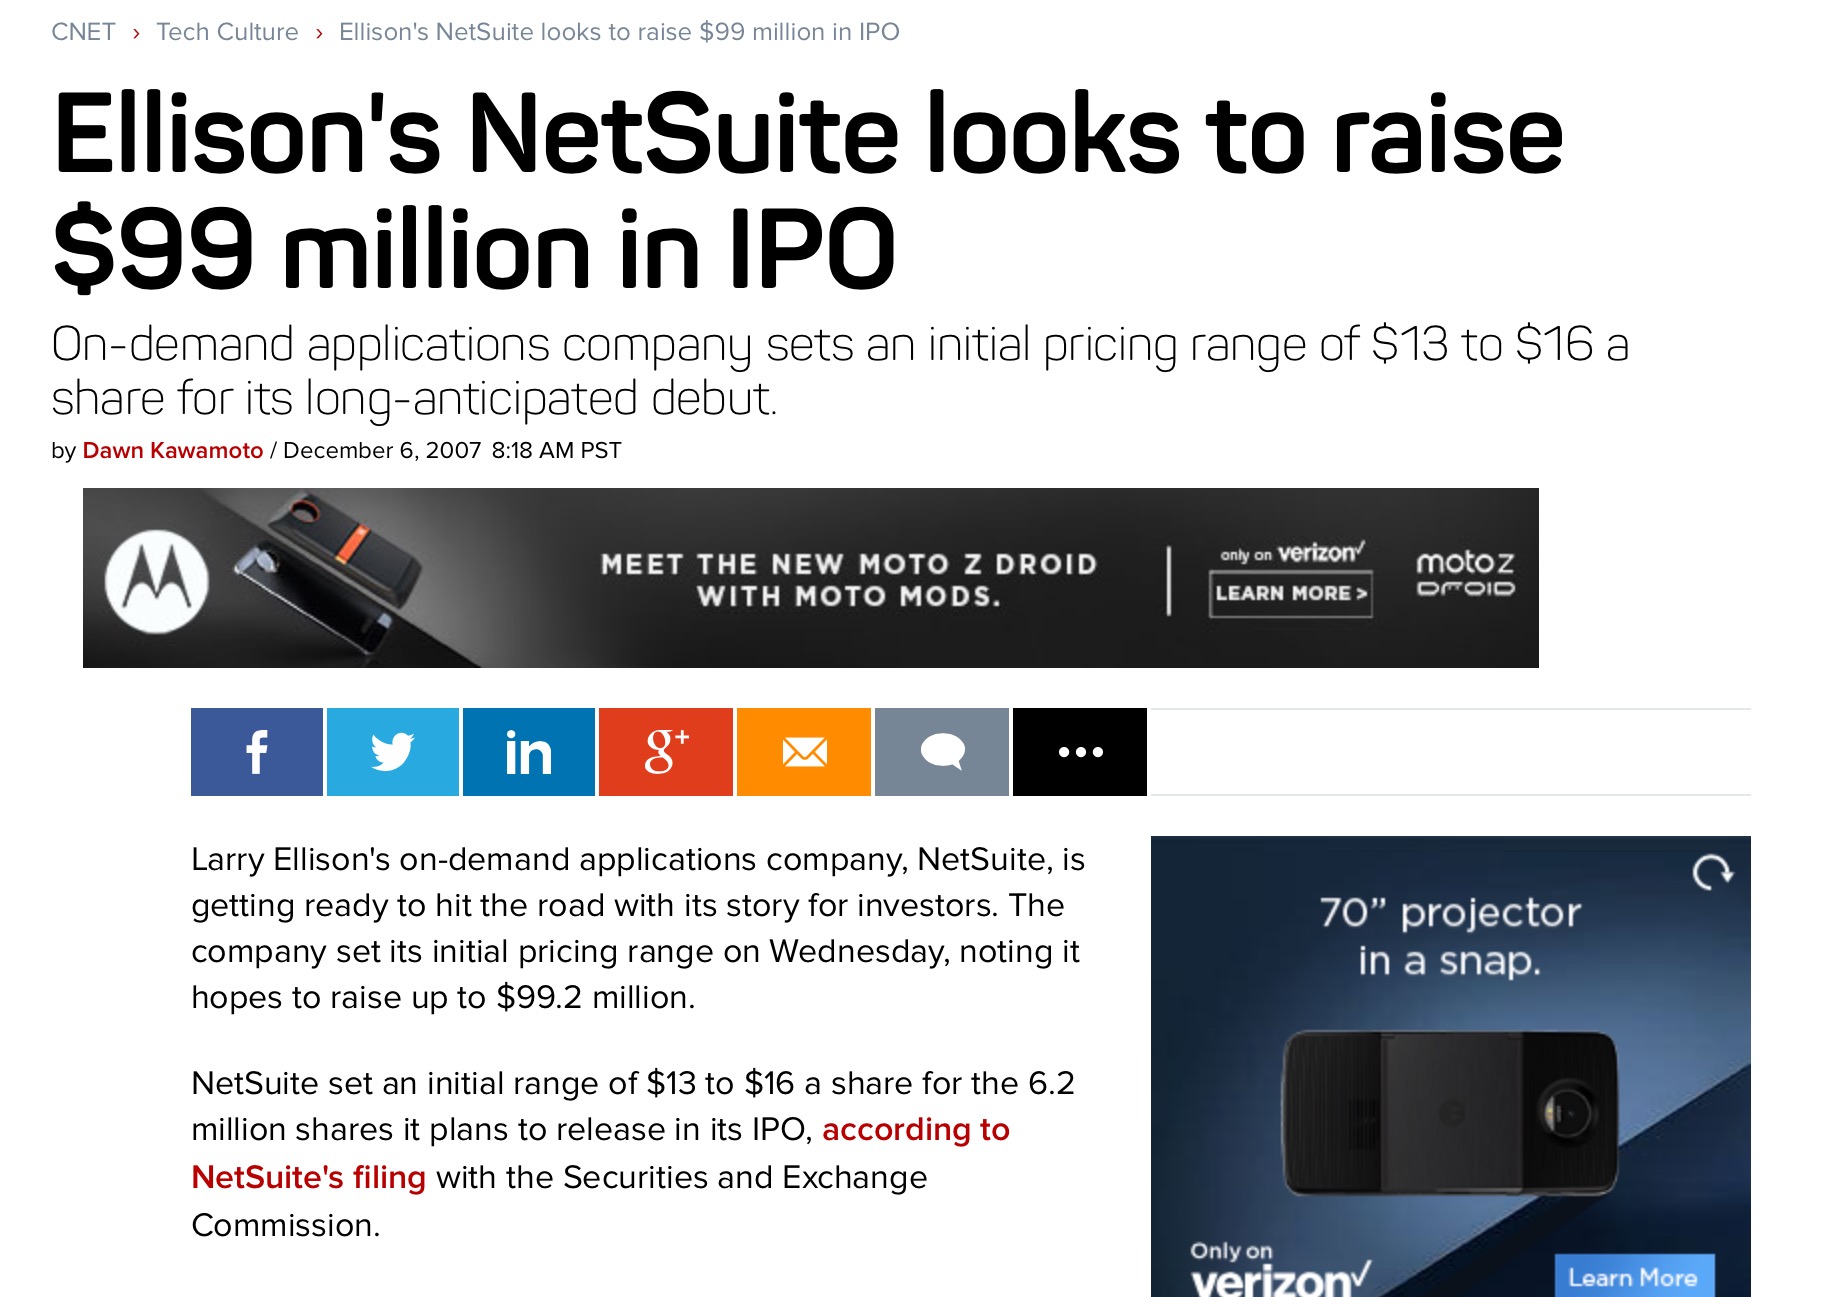
Look at this article, dated 2007.
image

It was his company from the start. Larry Ellison is merely playing parlour tricks today.

Now the big question is, who’s next? Everyone will go out and buy WDAY and SPLK today, hoping to catch a tailwind. The truth is, after dropping $10b on N, I very much doubt Oracle is going to make another big acquisition any time soon.

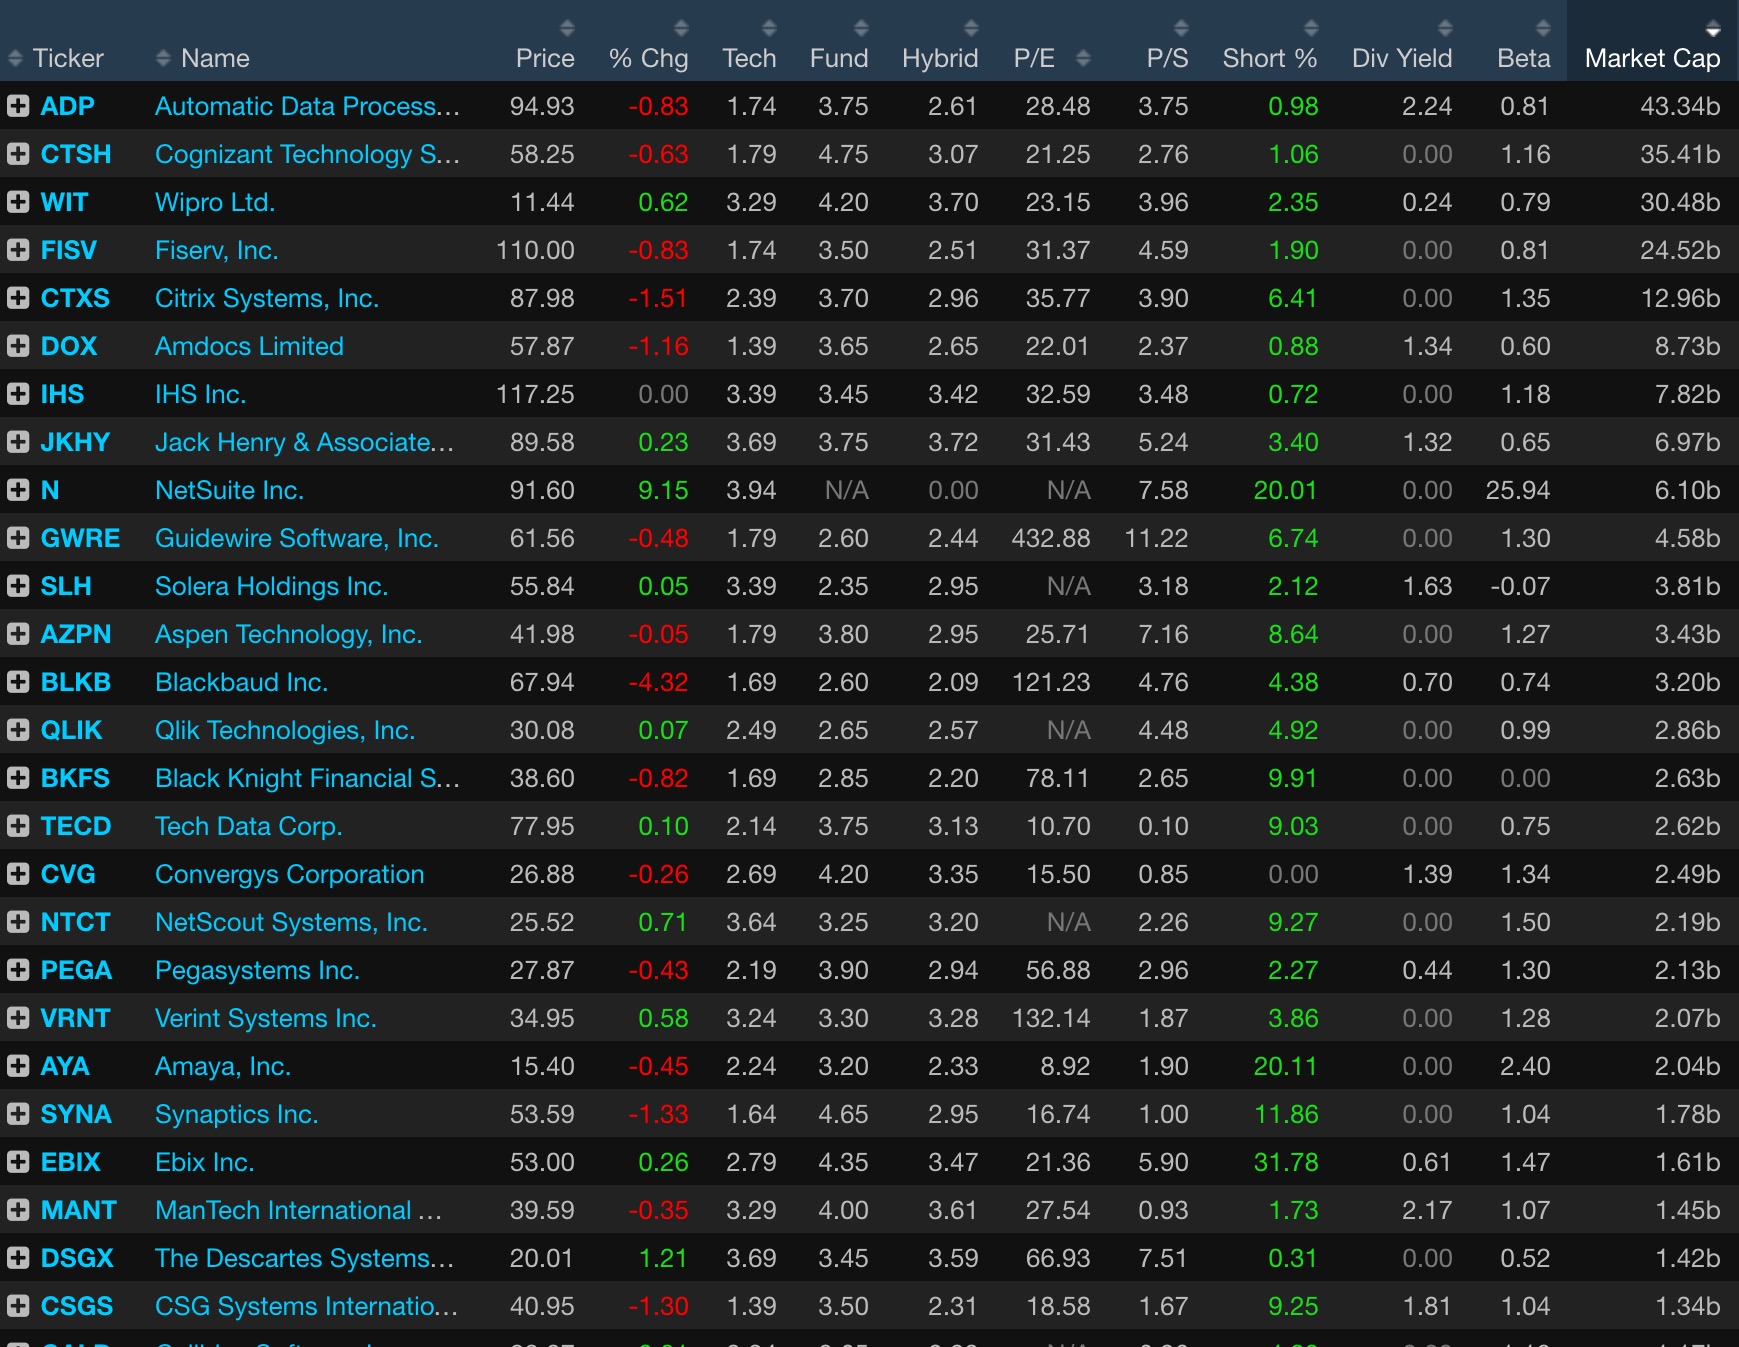
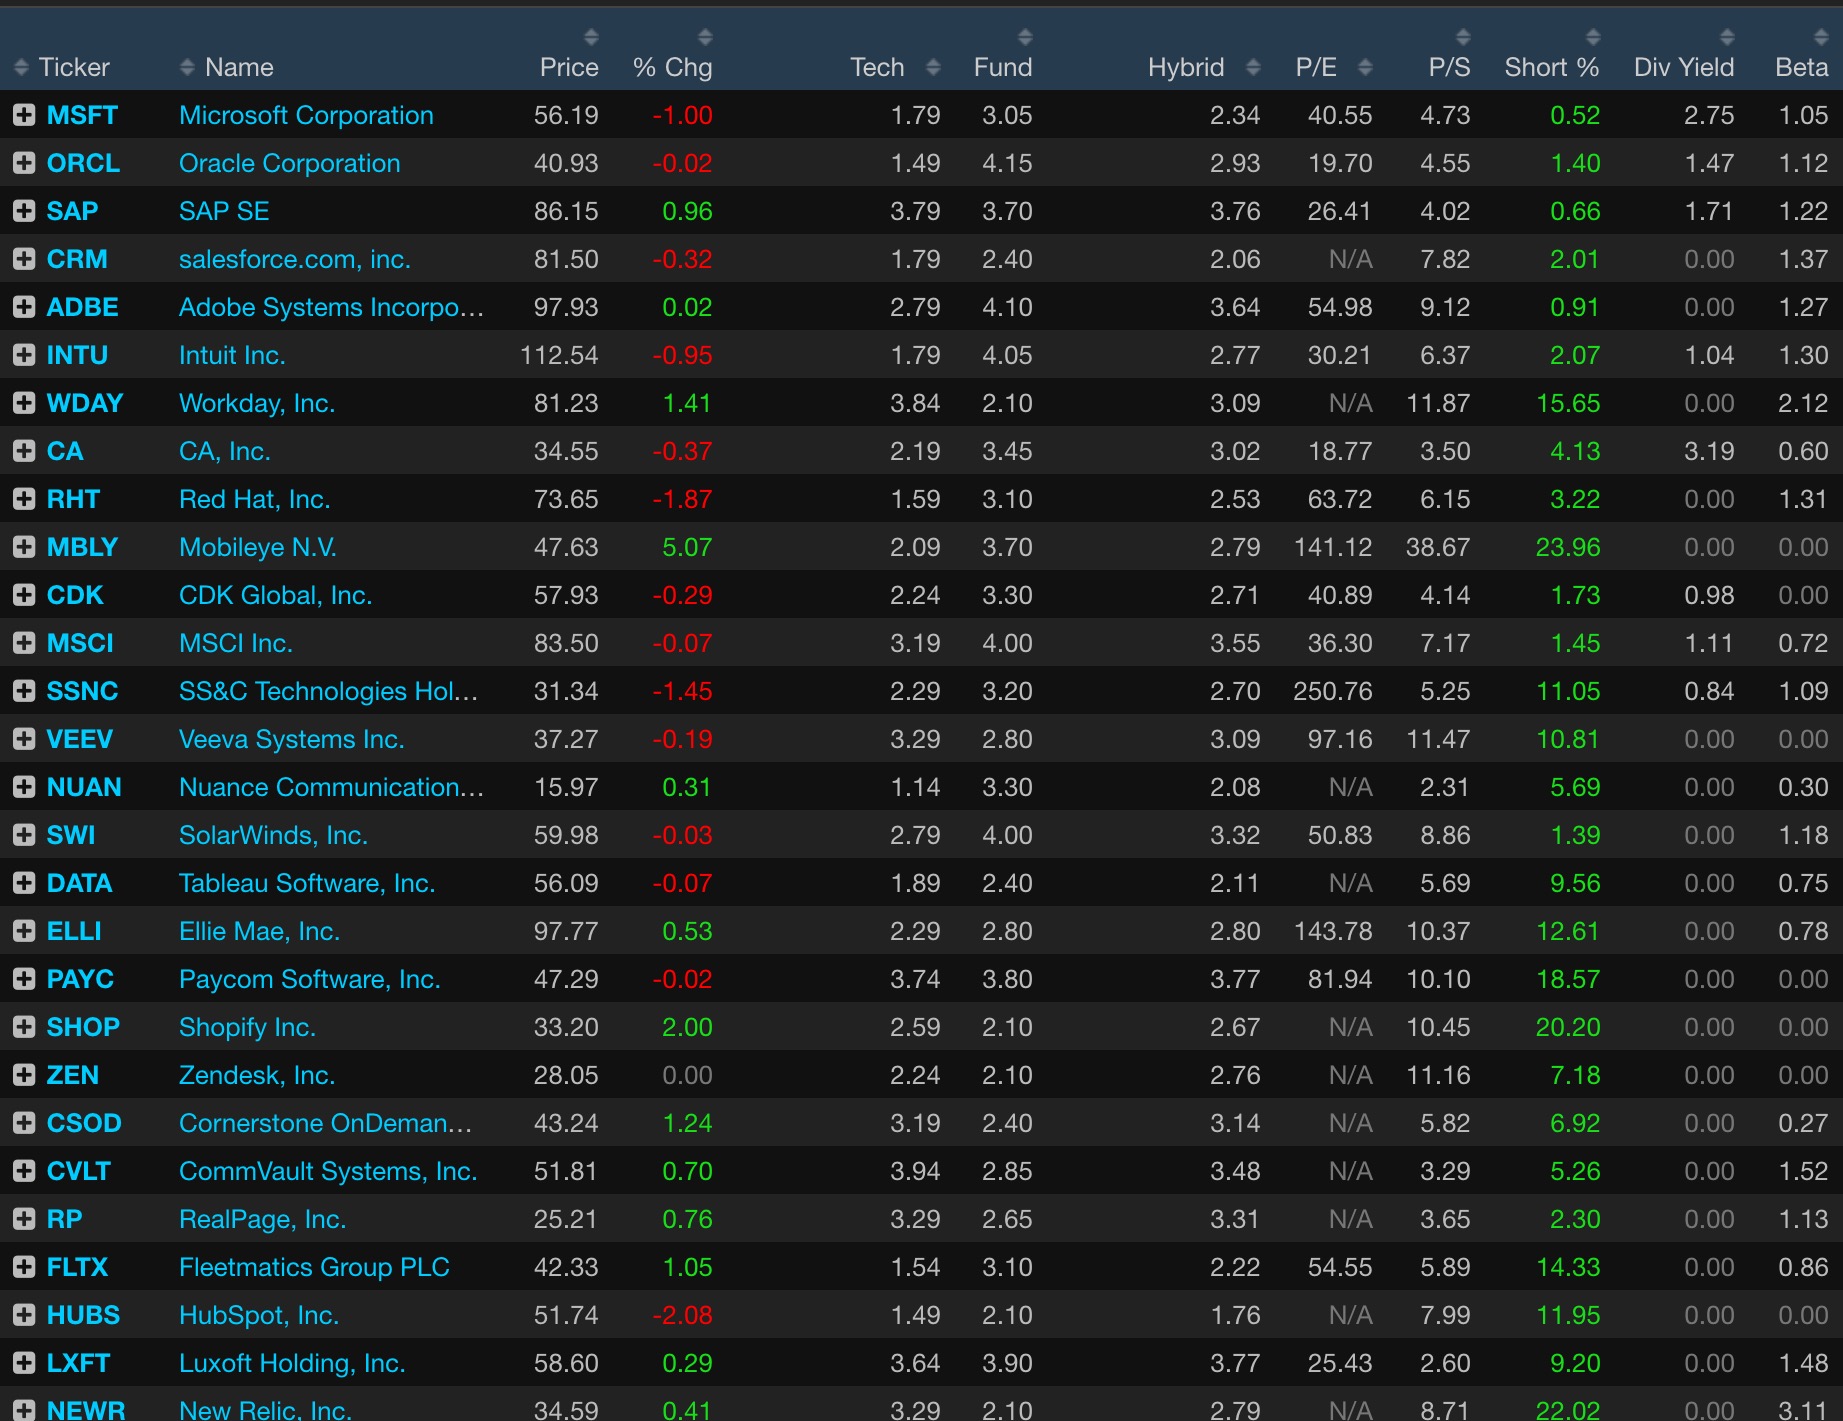
Nevertheless, here are the software stocks to watch, courtesy of Exodus.

image

image

If forced to pick two, I’d say WDAY and CSOD are next.

Comments »

Bearish BofA/Merrill Analyst Turns Bullish: ‘It’s Too Late to Be Bearish’

Ajay Kapur, Head of Asia-Pacific strategy at BofA/Merrill, blessed with a glorious mane, has declared ‘it’s too late to be bearish.’ Silly fools, the time for bearish calls on Asian equities was five years ago, said Ajay. All of the naysayers make for great philosophers, espousing a lexicon of bad news events that loom, imminently. Following several martinis, discussing policy amongst a room of pseudo-intellectuals, Ajay is more than capable of holding his own, rather matter of factly dismissing the folly of both the booze hound and morosophically demented.

Ajay Kapur has been bouncing around Wall Street like a molotov cocktail, these past few years. He’s been at Deutsche Bank, Citi and of course Morgan Stanley, just to name a few. In this very candid, and quite eloquent interview, Lord Kapur graced the Bloomberg audience with a head of hair fit for a king, black as night and long and flowing like a tumultuous Bay of Bengal high tide.

Very succinctly, as a chief representative of BofA/Merrill Asia, Mr. Ajay Kapur III chides those who believe there are any risks to equities, especially in China. A meridian of splendour and luxuriate gains await those able to remove themselves from the onion patch and into the Shanghai 50 Composite. The doom and gloomers, who Ajay claim have been wrong about Japan for many, many decades, in spite of the fact that that the NIKKEI hit a record high in 1989 and has gone down ever since then, shall commiserate with one another–cast out as the ‘family idiot’ and dispatched into the sea, indelibly, a loser. These small, yet trivial, facts are a great annoyance to Sir Kapur. His avocation and occupation is ‘to make money’, in addition to mollycoddling the masses into a sweeping stupor, just prior to a ceaseless bedevilment of the markets– an absolute and primordial desert storm that will lead to ‘his clients’ extinction from the field of play.

Henceforth, buy stocks!

Comments »

With Nonesuch Authority: It’s Time to Bet Against Dr. Copper

Fuck copper and the horse it rode in on. For the better half of the past year, the price of copper has been meandering, slivering even, like a snake. Most traders are unsure as to the immediate direction and simply chalk it up to Chinese nonsense. But the shares of FCX have risen to fantastic levels. Bear in mind, I left a whole book of clients long many shares of FCX in the single digits. But enough is enough.

Base metal shares have risen to absurd levels. Look to the price of X to understand what I am speaking of. By the way, that is a high risk pick of mine, heading into the elections.

Come hither as I divulge to you a great secret, small peasants.

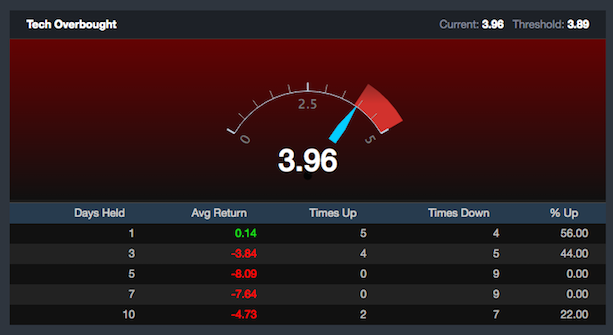
The sublime harmony of mathematical precision (SHOMP) is suggesting that you sell or sell short shares of FCX.
OB

I understand that to many of you selling short is equal to a Faustian Bargain, one wrought with sacrilege and scandal. But I beg of you to look towards the numbers. The algorithms that I’ve developed have a keen understanding of how FCX trades. Its never been wrong, in 9 previous instances, over the past year.

Nevertheless, and this was mentioned during today’s chat room session inside the new Pelican Room inside Exodus, I prefer to sell short XME. It too is flagged overbought and has incredible stats. But the timing of said short is in the details.

Such details will only be shared with the top hatted gents inside of our hallowed halls.

You can droll about the house again, pandering to your teevee box, ingesting cheese’d doodles whilst watching rotten tomatoes commit eloquent acts of unpatriotic sophistry for an otherwise beguiled and morosophical audience.

Comments »