Miraculously, the company beat on both the top and bottom lines. I have no idea how they accomplished this, with day rates down, utilization in the ground, and drilling revenues down to $918 mln, compared to $1.11 bln in Q1.
Oh yeah, that’s because THE ESTIMATES WERE MADE BY SUBMENTAL MISCREANTS WITHOUT COGNITIVE ABILITIES.
Revenues fell by 50% from last year. Crude is saddled at 3 mo lows and the EPA wants companies like RIG to fuck off.
The company had this to say, regarding their pathetic excuse for a company.
“though we continue to face market headwinds, the combination of our industry-leading backlog, exceptional operating performance, and solid financial position ensures that we will maintain our position as the industry’s leading deepwater driller.”
Listen to me. No one gives a shit about earnings anymore, especially for companies who make cars that are fueled by batteries made in a fucking giga factory. People don’t sell the stocks, that is run by a man, who wants to colonize the moon, build a hyperloop train and rid the planet of fossil fuels and replace it with one giant fucking solar panel.
Unil Musk messes up in as big way, like purchasing another one of his companies that was heading into bankruptcy, investors will give TSLA the benefit of the doubt. But it’s a bubble, no doubt about it.
Reports Q2 (Jun) loss of $1.06 per share, excluding non-recurring items, $0.41 worse than the Capital IQ Consensus of ($0.65); revenues rose 30.5% year/year to $1.56 bln vs the $1.65 bln Capital IQ Consensus.
Model S orders increased year over year. With the addition of Model X orders, total Q2 net new vehicle orders rose 67% from a year ago.
In Q2, we delivered 14,402 new vehicles consisting of 9,764 Model S and 4,638 Model X, which was slightly higher than what we stated in our July announcement. Model S remains the market share leader in North America and Europe among all comparably priced four-door sedans, and Model X is quickly gaining ground against similarly priced SUVs in all regions.
non-GAAP gross mrgin 20.8%
Outlook: Production and demand are on track to support deliveries of ~50,000 new Model S and Model X vehicles during the second half of 2016. Vehicle production efficiency is improving rapidly and we are now increasing our weekly production rate even further. Barring any further supply constraints, we plan to exit Q3 with a steady production rate of 2,200 vehicles per week, and plan to increase production to 2,400 vehicles per week in Q4. We anticipate that direct leasing will rise from 8% of deliveries in Q2 to about 15% of deliveries in Q3, as we have reached our funding limit with a banking partner. We anticipate adding new partners that will allow us to fund our planned growth in the future. We recognize revenue on directly leased deliveries as cash is received over the lease term of typically three years, on both a GAAP and non-GAAP basis. Model S and Model X cost reductions and improved vehicle manufacturing efficiency should offset the margin impact of the expected mix shift toward our 60 kWh configured vehicles and still drive additional gross margin increases throughout the year.
We expect GAAP and non-GAAP Automotive gross margins excluding ZEV credits to increase by 2-3 percentage points through Q3 and Q4 (previously called for 30% S and 25% X adj. gross margin). Total non-GAAP operating expenses should increase sequentially in Q3 and Q4, and we now expect full year 2016 total non-GAAP operating expenses to increase by about 30%. The increases come from engineering, design, and testing expenses related to Model 3 supplier contracts, and higher sales and service costs associated with expanding our geographic presence. Despite the disciplined pace of capital spending in the first half of this year, we still expect to invest about $2.25 billion in capital expenditures in 2016, in support of our accelerated production plan for Model 3.
“Some Model 3 production equipment is already on line, including initial capacity in our stamping and paint centers. Later this year, we plan to begin construction of new Model 3 body and general assembly centers. Gigafactory construction remains on target to support volume production of Model 3 in late 2017, and we recently accelerated construction to reach a rate of 35 GWh/year of cell production in 2018.”
Who said Jack Dorsey was a fascist ruler of news and information on Twitter? I certainly did not. Did you see what his other company just did? They beat earnings expectations and guided up, all the while @Jack grew his beard. In other words, the company grew faster than Jack’s beard.
For the quarter, Square lost a shit load of money, but grew the top line at a 54% clip. The company guided up, ever so slightly, also increasing EBITDA to $18-24m from $8-14m
Reports Q2 (Jun) loss of $0.08 per share, $0.04 better than the Capital IQ Consensus of ($0.12); revenues rose 54.1% year/year to $171 mln vs the $157.88 mln Capital IQ Consensus.
In 2Q16, it processed $12.5 bln in GPV, an increase of 42% from 2Q15. New-seller growth made up the majority of its GPV increase, while positive dollar-based retention from existing sellers also had a meaningful impact.
Co achieved positive EBITDA of $13 mln.
Extended $189 mln in Square Capital, up 123% year over year and 23% sequentially.
Co issues upside guidance for Q3, sees Q3 revs of $167-$171 mln vs. $164.19 mln Capital IQ Consensus Estimate. Expects Adjusted EBITDA of $5-$6 mln.
Co issues raises guidance for FY16, sees FY16 revs of $655-$670 mln, up 6% at the mid-point of its prior guidance, and vs. $641.98 mln Capital IQ Consensus Estimate. SQ expects Adjusted EBITDA to be in the range of $18-$24 million, up from its previously guided range of $8-$14 mln.
God bless Jack Vissarionovich Dorsey.
SQ is higher by 9% in the after-hours, and lower by a mere 17% over the past 3 months. Winning.
What a fucking insane sector. This stock has been beaten like an ugly toy during 2016, off by more than 25%.
The company just beat and guided up, so shorts might get kicked in the nuts in the AM.
Reports Q2 (Jun) earnings of $0.87 per share, excluding non-recurring items, $0.32 better than the Capital IQ Consensus of $0.55; revenues rose 4.2% year/year to $934 mln vs the $862.68 mln Capital IQ Consensus.
Co issues guidance for FY16, sees EPS of $4.20-4.50 (Prior $4.10-4.50), excluding non-recurring items, vs. $4.19 Capital IQ Consensus Estimate; sees FY16 revs of $3.8-4.0 bln vs. $3.86 bln Capital IQ Consensus Estimate.
Gross Margins 18.5-19.0% (Prior 18-19%)
Operating Expense $380-400 mln (Reaffirm)
Operating Cashe Flow $400-650 mln (Prior $500-700 mln)
CapEx $275-325 mln (Prior $300-400 mln)
Shipments 2.9-3.0 GW (Reaffirm)
Shares are up 2.5% in the after hours, adding to its 3% regular session gain.
When crude was going down, people said that was a good thing. Over the past 2,000 years, there has been a negative correlation between the flammable black liquid and stocks. But today’s 4% bounce also provided succor for stocks. Why does such fuckery exist in the world today?
Oxygen.
If we are to judge Hillary Clinton, Donald Trump, Islamic terrorism, right wingers gone mad, Black Lives Matter demand for more pigs to roast, the one thing they all have in common is oxygen. Everyone breathes the stuff and is the only thing that everyone has in common.
People have been doing crazy shit for exactly 6,000 years, according to the bible. If we could just figure out how to get rid of the stuff, life as we know it would be far less chaotic and quiet.
Dow erected itself into the bell, 3:30 ramp style. Get ready for some oxygen fueled earnings.
Ah, it was all an ingenious plan to root out the system of weak players, bankers in the way of wanton success and prosperity. It’s funny to see these large bracket braindead people get on teevee and try to make sense of things, without ever thinking about the obvious.
He thinks the whole negative rate idea might be sheer genius to bankrupt the weak players, since Europe is ‘over-banked.’
My theory is governments did the math and figured out they would not be able to service the interest on their debt in a decade or two. Therefore, they put plans into action to make the servicing costs for the debt, not only affordable, BUT PROFITABLE!!! By issuing new debt at negative rates, western society can continue to lavish itself in splendor, drawing blood from the young to preserve the organs of the old and the rich, and make money doing it.
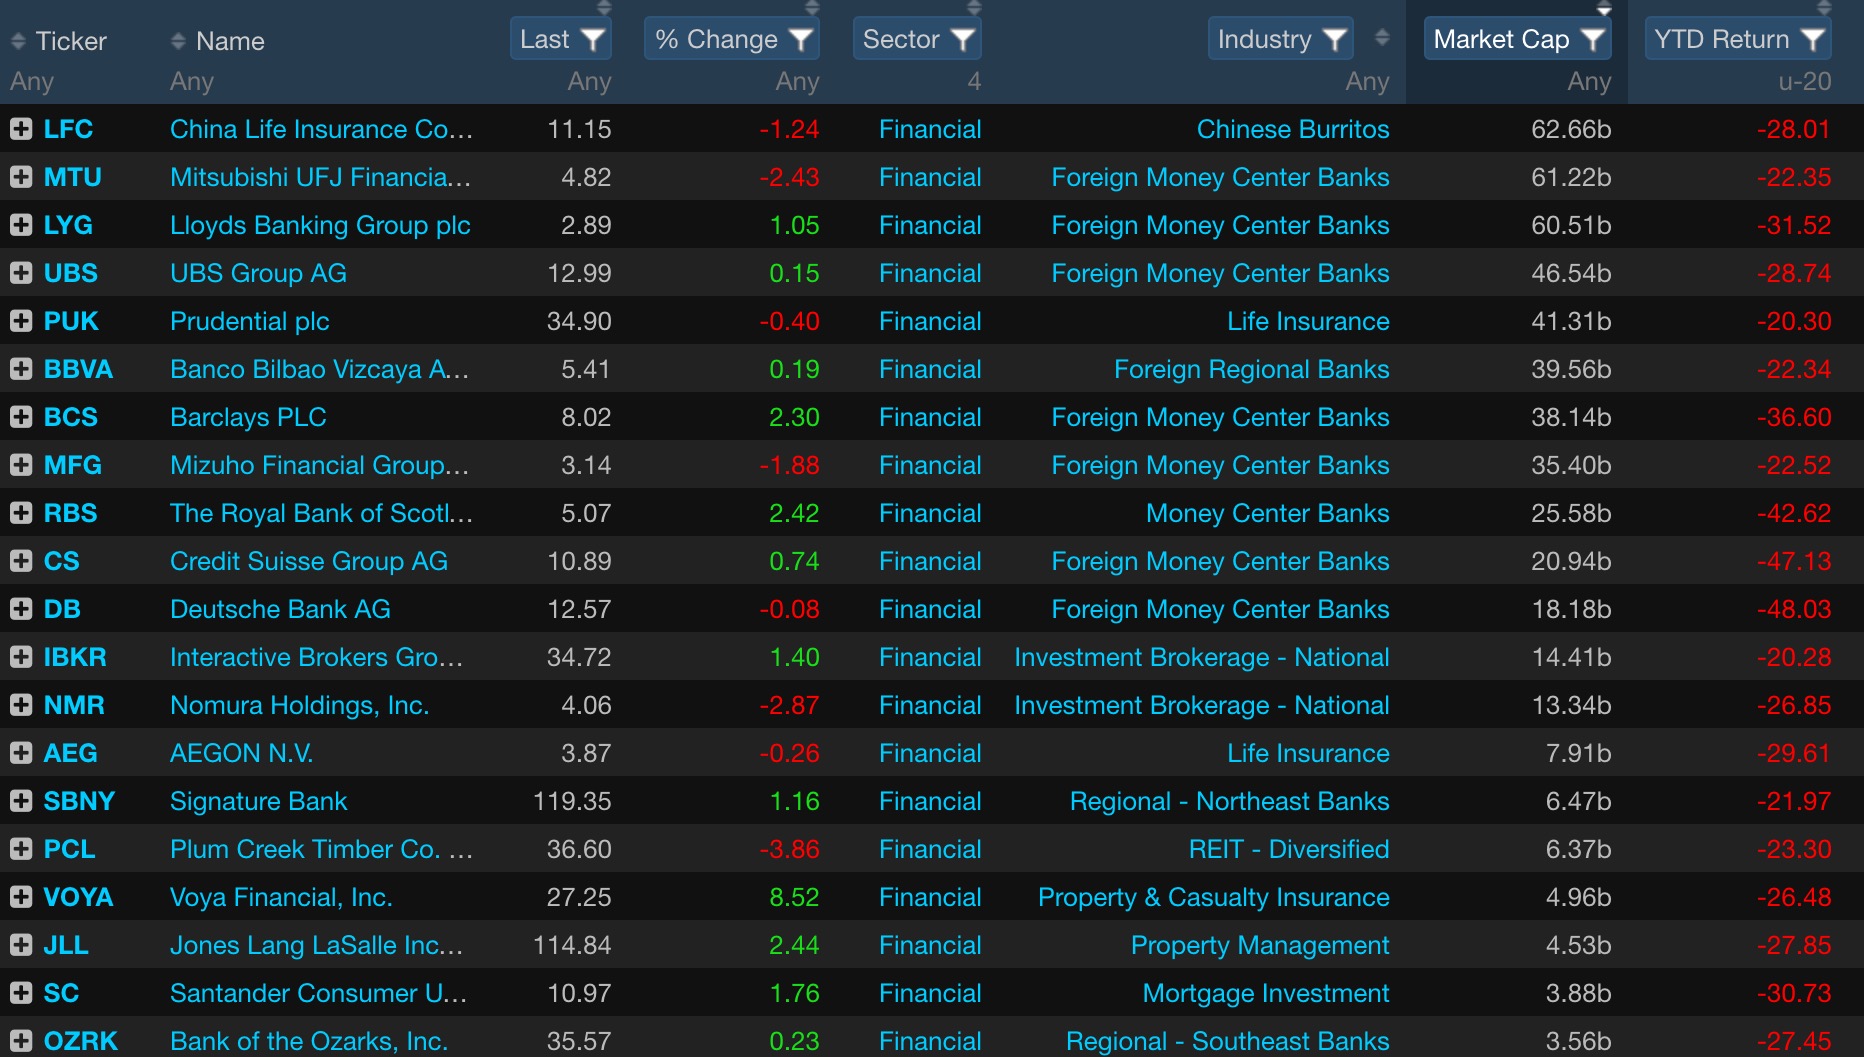
Someone get me some data on previous bull markets that not only didn’t include the banks, but also shit on them. WTI is spiking 3% this afternoon and markets are sashaying higher again. All the while, trolls from middle earth are clawing at the walls of Deutsche Bank, Credit Suisse and Barclay’s. The entire European banking system is in disarray, while ours is on permanent vacation. God willing the newly adorned Empress of America will punish them and their $3.50 ATM fees.
Naturally, if the shares of leading banks are down 20-50% for the year, credit is going to be tight. Banks cannot lend money out the door, whilst it’s being burned inside. Maybe it doesn’t matter anymore? Perhaps we’ve transcended the lucidity of balance sheets and have adapted to a world of smoke and mirrors, where share buybacks and central bank rigging is all we need?
As a megalomaniac, it’s important to control, throttle even, the flow of information and news. On this planet, there are just a handful of places where human beings converge to get information.
There is Facebook, Reddit, The Drudge Report, Google, LinkedIn, and Twitter. Since Matt Drudge merely posts links to articles, that can’t be controlled until someone figures out a way to offer him a heart attack. Conde Nast already owns Reddit. Zuckerberg and the Google or Alphabet nerds are running their news outlets like communist propaganda era arms. MSFT bought LNKD. And @Jack is trying to be Zuckerberg with Twitter, minus all of the cool profits. Plus, people think he just wants to head to Square and live out his life like a full bearded booze hound.
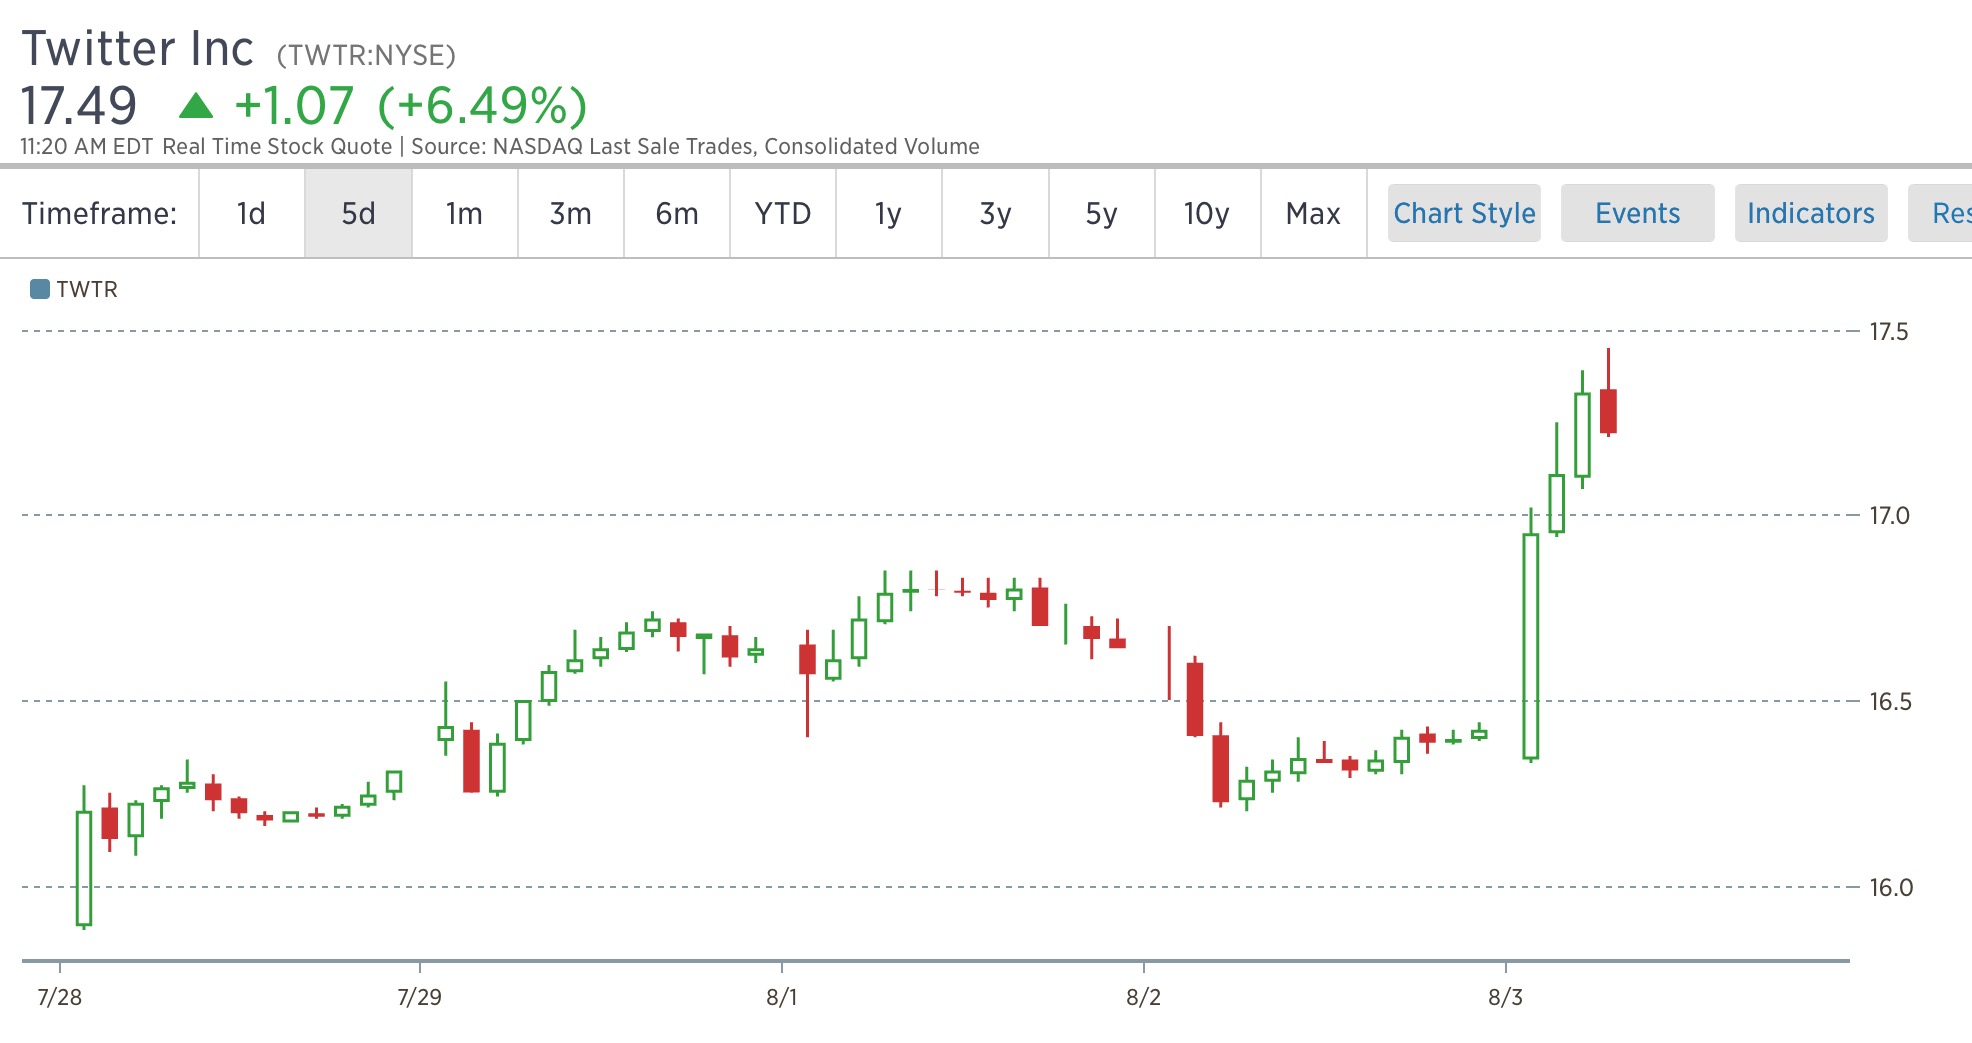
Shares of Twitter are rising on takeover rumors today. Normally I dismiss these rumors, but the climate has never been better for megalomaniacs who’d like to control things. I wouldn’t be surprised to see someone bid for this piece of shit and fold it into a larger, money making, enterprise.
If the title of this post doesn’t jibe well with reality, it’s because you’ve haven’t transcended your physical frame into the multiverse, where all of the basic laws of physics and math have different rules.
The EIA just reported a build of 1.4m barrels of crude vs the expectations of a draw from between 900k-1.9m. At first, that sent crude lower. Then traders had a look at the gasoline draw of 3.2m and decided ‘good enough.’
“Risks for oil remain skewed to the downside in the second half of 2016,” analysts at Morgan Stanley said in a report. “Supply disruptions and risk appetite were supportive April-June, but fundamental headwinds are growing, which outnumber any recent positives.”
Standard Chartered bank said there was “no fundamental justification for recent oil-price falls” and “the global oil market has rebalanced, and U.S. crude supply and inventories are expected to fall.