iBankCoin
Home / 2016 / April (page 5)

Monthly Archives: April 2016

U.S. Steel Ratchets Up Trade War with China, Files Complaint with the ITC

In what is being described as the boldest move against foreign steel interests since 1978, U.S. Steel is trying to get China from cheating and stealing its way into the American steel markets.

The petition, known as Section 337 and used to protect against intellectual property theft, listed some of China’s top producers, including Hebei Iron & Steel Group and Anshan Iron and Steel Group and Shandong Iron & Steel Group Co [SDONGG.UL].
“We have said that we will use every tool available to fight for fair trade,” said U.S. Steel Corp President and Chief Executive Officer Mario Longhi in a statement.

“With today’s filing, we continue the work we have pursued through countervailing and antidumping cases and pushing for increased enforcement of existing laws.”

It comes after U.S. officials last week warned that China should take steps to cut excess output or face possible trade action and Australia said it will impose import duties on certain types of Chinese steel to protect domestic steelmakers.
China’s Commerce Ministry called steel a “mature product” where “intellectual property rights disputes do not exist”, and said industry from both the United States and China should work together to address overcapacity caused by weak global demand.
“So-called accusations of intellectual property rights violations have no factual basis. We hope the U.S. International Trade Commission will reject these accusations,” the ministry said on Wednesday in a statement on its website.

China has been dumping subsidized steel on our shores for a long time. It’s basically a welfare state for China, with the government paying steel makers to employ thousands, enabling them to dump steel on our markets for a fraction of what American steel makers charge.

Comments »

$TWTR Clown Plunges Towards All-Time Lows; Analysts Cast Them Aside as a House of Ill Repute

Monetization is slowing. The Twitter is dying. The company is a house of ill repute.

Shares are plunging by more than 15% this morning, on much worse than expected quarterly results.

image

The analyst community are casting wide aspersions this morning.

Mizuho Securities notes, so far, 2016 is not looking rosy for the blue bird. MAUs were up only 5m sequentially, revenue came at the low end of guide and below expectations due to weakness from brand advertisers, and the 2Q revenue guide implies very modest sequential growth. Firm maintains Neutral rating given that it does not see any material near-term catalysts, but certain products/ad units could drive growth later this year or in early 2017. Firm is impressed by the product innovation at Twitter since Jack Dorsey took over, but the business model continues to lag. Remain on the sidelines for now.

Pivotal Research notes weak 1Q16 results and 2Q16 results suggest a worse-than-expected 2016 and longer-term growth trajectory. Despite firm’s own confidence in the still-favorable prospects of the business, investor confidence is unlikely to return any time soon. Continue to rate Twitter Buy, but reduce price target from $39 to $27 on a YE2016 basis. Advertising as-reported was up by +37%, constrained slightly by foreign exchange down from a +48% growth rate in 4Q15. More concerning than the deceleration was that O&O ad revenue grew by only +23%. Conservative guidance for the current quarter is sensible

RBC Capital notes Organic Rev growth is clearly decelerating; all-important MAUs are showing limited growth (though was a bit ahead of Street). Maintain Sector Perform, but lower ests and tgt to $20 from $23. Q4 Keys- 1) Better than Expected MAUs, firm remains cautious on TWTR’s ability to show meaningful user growth; 2) Continued Revenue Growth Deceleration; 3) Strong Margins; 4) Monetization Slowing.

Comments »

Goldman Passes Judgement Upon $AAPL, $BWLD; Stocks Removed From ‘Conviction Buy List’

Come hither Apple Computer corporation and the Buffalo Wild Wing entity. Your presence is no longer required in these convicted halls of Goldman, as you’ve proven to be unworthy of our grace. Heretofore, your attendance was quite popular amongst our customers and denizens of our banking interests. But now, you’re an albatross of the first magnitude.

Be gone from this place and erase it from your memories, forever, or until you come across a great deal of cash. Only then will you be welcomed here and considered to be something that we have ‘conviction’ in.

Yours everlastingly,

The Goldman Sachs Corporation


Apple target lowered to $136 from $155 at Goldman; Removed from Conviction Buy List, maintain Buy rating

Buffalo Wild Wings target lowered to $166 from $185 at Goldman; Removed from Conviction Buy List following the Q1 results

Super assholes.

Comments »

Comcast in Talks to Acquire Dreamworks

The Wall Street Journal is reporting that Comcast is in talks to acquire Dreamworks for more than $3 billion. At or around $3 billion, that would equate for a massive premium to Tuesday’s closing price of approximately 30%.

Year to date, DWA is up around 5%. Both revenues and earnings have upticked recently, thanks to big box office smashes, such as Kung Fu Panda. Truth is, DWA is a giant turd, with limited creative skills as a studio. They’d be smart to cash in now, before Comcast figures out they’re getting ripped off.

Comments »

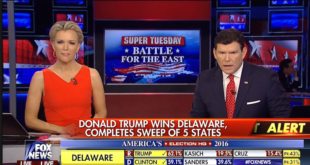
TRUMP WINS IT ALL

He laid waste to Rafael Cruz and the road slob Kasich.

It looks like a clean sweep of 5 states: MD, PA, RI, CT and DE are all his. Some might argue ‘those a liberal states.’ Fuck off. This is a republican primary, not a general election. Moreover, the state of PA is as backward and checkered pants as they come, being the #1 state in the union in terms of bearing arms.

The results weren’t even close, utterly embarrassing for the other candidates. People literally hate them.

Stay tuned for Trump’s celebratory speech.

NOTE: Trump is up by sixty points in PA.

Comments »

Chipotle Posted Catastrophic Numbers; Guidance is Even Worse

Chipotle is losing money and rapidly decelerating in terms of sales and margins. Comps are down 29% and the company has resorted to giving away burritos to increase foot traffic. The lunacy of it all lies in the decisions put forth by management. They intend to open 220-235 new restaurants in 2016, effectively leveraging a broken model.

The stock is down 4.5% in the after-hours, continuing a harrowing decline that began when the company started to poison people with their food several month’s ago.

These numbers are much worse than anyone had expected. Shareholders should expect scathing reports tomorrow morning and significant pressure on shares throughout 2016. In my opinion, CMG doesn’t deserve any premium valuation and should fall in value down to $250.

Via Briefing.com

  • Reports Q1 (Mar) loss of $0.88 per share, $0.17 better than the Capital IQ Consensus of ($1.05); revenues fell 23.4% year/year to $834.5 mln vs the $863.24 mln Capital IQ Consensus.
  • Warned on March 15: Lowered EPS to ($1.00) or worse from break even; updated comps through 2nd week of March.
    • The decrease in revenue was driven by a 29.7% decrease in comparable restaurant sales (estimates near down 28.5%), partially offset by sales from new restaurant openings. Comparable restaurant sales declined primarily as a result of a decrease in the number of transactions in our restaurants, and to a lesser extent by a decline in average check, including an impact from sales promotions.
  • Comparable restaurant sales decreased 29.7%, Comparable restaurant transactions decreased 21.1%.
  • Restaurant level operating margin was 6.8%, a decrease from 27.5%. The decrease was primarily driven by unfavorable sales leverage, and to a lesser extent by higher than usual marketing and promotional costs, and food testing and waste costs.
  • For 2016, management expects the following:
    • 220 – 235 new restaurant openings
    • An effective full year tax rate of approximately 38.4%
  • CMG says that it began to see some recovery in comps in the second half of the first quarter. In January, comps were running at about -34%. It improved to about -22% in the first few weeks of April, with Easter adding about 4%. Wet, cold weather also negatively affected comps in early April.
  • The company says the recovery has been uneven throughout the country. The west coast and northeast for example — where the health concerns were most acute — have struggled the most. In these geographies, it has only recovered about a third of visits.
  • The company believes that consumer perceptions are improving, based on in-depth research work done. That said, it still needs to see improvements in certain areas. For instance, customer admiration has slipped to 61% from 70%. Likely to revisit is at 43%. These are up from earlier, but, still not where CMG wants to see them.
  • In regards to marketing, it is implementing its largest marketing program through the end of June. Throughout the year, the company plans to be more aggressive with marketing (possible buy one, get one promo), and will launch a new limited time frequency program this summer. Also, it will add new menu items to invite customers back.
  • Its free burrito program this past winter was very successful, with a 67% redemption rate on the mobile offer. This helped provide a boost to comps.
  • In terms of expansion, the company still sees a very significant opportunity past this year.
  • CMG says it is not prepared to give EPS guidance for Q2, saying that it is really dependent on sales. At comps stay at current levels, going to be difficult to deliver a healthier EPS. CMG gives an example that if comps stay at current levels, restaurant level margins should improve to low double digits.
  • Shares of CMG are trading about 6% lower in after hours.

Comments »

$AAPL Harrowed in After-Hours on Wretched Earnings and Guidance

Let’s keep this clean and to the point. Tim Cook is still gay and actively seeking a life partner, who may or may not relieve himself inside of the ladies bathroom. Okay? Aside from that, S. Jobs is fucking rolling over in his grave, haunting Tim at night, throwing candelabras at him –because of what he’s done to his baby.

Apple reported a very bad quarter, with both earnings and revenues coming in light. Margins were less than expected and iPhone and Mac sales were disappointing.

Additionally, the company issued downside guidance, with sharply lower margin guidance, indicative of a company struggling to maintain share. The board has authorized share buybacks to the tune of $175 billion.

Why not just toss said dollars into a flaming barrel of trash?

Via briefing

  • Reports Q2 (Mar) earnings of $1.90 per share, $0.10 worse than the Capital IQ Consensus of $2.00; revenues fell 12.8% year/year to $50.56 bln vs the $51.98 bln Capital IQ Consensus; gross margins of 39.4% vs 39.6% ests vs 40.8% last year (guidance 39-40%).
  • iPhones 51.2 mln vs 51.5 mln ests vs 61.2 mln last year.
    • iPads 10.2 mln vs 9.9 mln ests vs 12.6 mln last year.
    • Macs 4.0 mln vs 4.6 mln ests vs 4.5 mln last year.
  • Co issues downside guidance for Q3, sees Q3 revs of $41-43 bln vs. $47.35 bln Capital IQ Consensus; gross margin 37.5-38.0% vs 39.2% ests vs 39.7% last year
  • The Board has increased its share repurchase authorization to $175 billion from the $140 billion level announced last year. The Company also expects to continue to net-share-settle vesting restricted stock units.
  • The Board has approved an increase of 10% to the Company’s quarterly dividend, and has declared a dividend of $0.57 per share, payable on May 12, 2016 to shareholders of record as of the close of business on May 9, 2016.
    • 2.3% dividend yield at after hours price of $99/share.


The stock is lower by 7% in the after-hours, dragging with it a sundry of tech names, such as SWKS -4.0%, QRVO -3.9%. CRUS -3.0% (also reported its own earnings), AVGO -2.2%, NXPI-2.0%, QCOM -1.1%, INVN -0.9%, TXN -0.6%,

Comments »

Peak Chicken Wings: $BWLD Culled in After Hours After Reporting Abysmal Earnings

Call me superficial. The Buffalo Wild Wing corporation just opened a store in Princeton. Upon seeing it, I had a feeling  the stock had peaked. Upon dining in it, I knew it was heading lower. The service and food are of the catastrophic varietal. They had one job to do, which was to make me some quality chicken wings. They failed. As such, the shares are inexorably lower by 12% in the after-hours blood session.

Via Briefing

  • Total revenue increased 15.4% to $508.3 million
  • Company–owned restaurant sales increased 16.6% to $483.9 million
  • Same–store sales decreased 1.7% at company–owned restaurants and 2.4% at franchised restaurants
  • Net earnings increased 12.8% to $32.8 million from $29.0 million, and earnings per diluted share increased 13.5% to $1.73 from $1.52

Sally Smith, President and Chief Executive Officer, commented, “Our total revenue in the first quarter increased 15.4%, when compared to the prior year, resulting from continued unit development and franchise acquisitions over the last 12 months. We are dissatisfied to report a same-store sales decline and we’re undertaking several sales-driving initiatives to regain momentum. We were able to manage costs and improve our restaurant-level margin, and earnings per diluted share increased 13.5% year-over-year to $1.73.”

Total revenue increased 15.4% to $508.3 million in the first quarter, compared to $440.6 million in the first quarter of 2015. Company–owned restaurant sales for the quarter increased 16.6% over the same period in 2015, to $483.9 million, driven by 100 additional Buffalo Wild Wings® restaurants at the end of the first quarter of 2016, partially offset by a same-store sales decrease of 1.7%. Franchise royalties and fees decreased 5.0% to $24.3 million for the quarter, versus $25.6 million in the first quarter of 2015. This decrease is attributed to seven fewer franchised Buffalo Wild Wings locations and a same-store sales decrease of 2.4% at franchised Buffalo Wild Wings restaurants in operation at the end of the period, compared to the same period in 2015.

Average weekly sales for company-owned Buffalo Wild Wings restaurants were $62,829 for the first quarter of 2016, compared to $64,851 for the same quarter last year, a 3.1% decrease. Franchised Buffalo Wild Wings restaurants in the United States averaged $65,636 for the period, versus $67,075 in the first quarter a year ago, a 2.1% decrease.

Other income in 2016 consisted primarily of a gain related to the valuation of contingent consideration for a franchise acquisition of $1.1 million, partially offset by interest expense of $0.9 million.

Under the previously announced share repurchase authorization, 173,892 shares were repurchased during the first quarter of 2016 for a total of $25 million.

For the first quarter, net earnings increased 12.8% to $32.8 million, versus $29.0 million in the first quarter of 2015. Earnings per diluted share were $1.73, compared to first quarter 2015 earnings per diluted share of $1.52.

2016 Outlook

Ms. Smith remarked, “We are focused on sales-driving initiatives to regain momentum in 2016. To strengthen our FastBreak™ lunch program, we’re piloting a speed of service guarantee. We’re promoting Wing Tuesdays® while evaluating different pricing and bundling options for this value day. Soccer is a growing sport in the United States and we’ll be the place to watch all the action on the pitch for the major tournaments this summer.”

Ms. Smith concluded, “The Buffalo Wild Wings brand remains strong and poised to deliver long-term earnings growth. In 2016, we’re continuing our development of new company-owned and franchised Buffalo Wild Wings restaurants in the United States and we are aggressively remodeling locations. Given our recent sales trends and an increasing outlook for the cost of traditional chicken wings, we believe earnings per diluted share in 2016 should be $5.65 to $5.85.”

For 2016, the company expects the following new unit development:

  • Approximately 40 company-owned Buffalo Wild Wings restaurants
  • 30 to 35 franchised Buffalo Wild Wings locations in the United States
  • 12 to 15 franchised Buffalo Wild Wing locations internationally
  • 6 company-owned and 4 franchised R Taco restaurants
  • Continued unit expansion by PizzaRev

For 2016, the company expects the following:

  • Improving same-store sales
  • Deflationary food costs, excluding traditional chicken wings
  • Depreciation and amortization expense of $150 to $155 million
  • Share repurchase activity of approximately $100 million
  • Earnings per diluted share of $5.65 to $5.85
  • Capital expenditures of approximately $190 million, excluding additional franchise acquisitions or emerging brand investments


Comments »

Twitter Guides Sharply Lower; Shares Menaced in After-Hours Tragedy

The company reported 310 million monthly users vs the consensus of 308 million. Both revenues and earnings, going forward, will be an abomination. As such, shares of TWTR are knifing lower in the after-hours, off by 10%.

Twitter sees Q2 revs $590-610 mln vs $677.39 mln Capital IQ Consensus Estimate; EBITDA $145-155 mln

I am ignoring what the company is saying in the after-hours, trying to stem the flow of sellers out of the stock. This company has done nothing but disappoint since coming public.

This company is being grossly mismanaged. Fire Jack now.

Via briefing
Reports Q1 (Mar) earnings of $0.15 per share, $0.05 better than the Capital IQ Consensus of $0.10; revenues rose 36.5% year/year to $595 mln vs the $607.55 mln Capital IQ Consensus.
MAUs comes in at 310 mln, street expectations were for 308 mln
Advertising revenue totaled $531 million, an increase of 37% year-over-year. Excluding the impact of year-over-year changes in foreign exchange rates, advertising revenue would have increased 39%.
Mobile advertising revenue was 88% of total advertising revenue.
Data licensing and other revenue totaled $64 million, an increase of 34% year-over-year.
U.S. revenue totaled $390 million, an increase of 35% year-over-year.
International revenue totaled $204 million, an increase of 39% year-over-year. Excluding the impact of year-over-year changes in foreign exchange rates, international revenue would have increased 46%.
Co issues downside guidance for Q2, sees Q2 revs of $590-610 mln vs. $677.39 mln Capital IQ Consensus Estimate; Adjusted EBITDA is expected to be in the range of $145-155 mln.
Co reaffirms FY16 Capital expenditures guidance to be $300 to $425 million; Adjusted EBITDA margin in the range of 25-27%.

Comments »

Recession Fears Drop as GDP Growth Forecasts Plunge

This is equal to watching a NY Mets game, seeing the opposition constantly increase their lead, and feeling increasingly better about the specter of a Mets win. ‘Tis is the case with the U.S. economy. People have gone fucking apeshit mad, sopping up secondary offerings and greasy oil stocks, amidst BILLIONS in write-downs. The Atlanta Fed is forecasting a 0.4% growth rate for Q1, yet the level of fear is virtually non-existent, judging by recent polls and the VIX tits index.

Markets don’t give a shit. Share buybacks and firings will keep this economy humming along just fine. Let’s see what Apple has to see, due to report earnings after the bell.

Comments »