iBankCoin
Home / 2016 / April (page 23)

Monthly Archives: April 2016

An Amazing Melt Up in Gold & Silver is Underway; Everything Else Flags

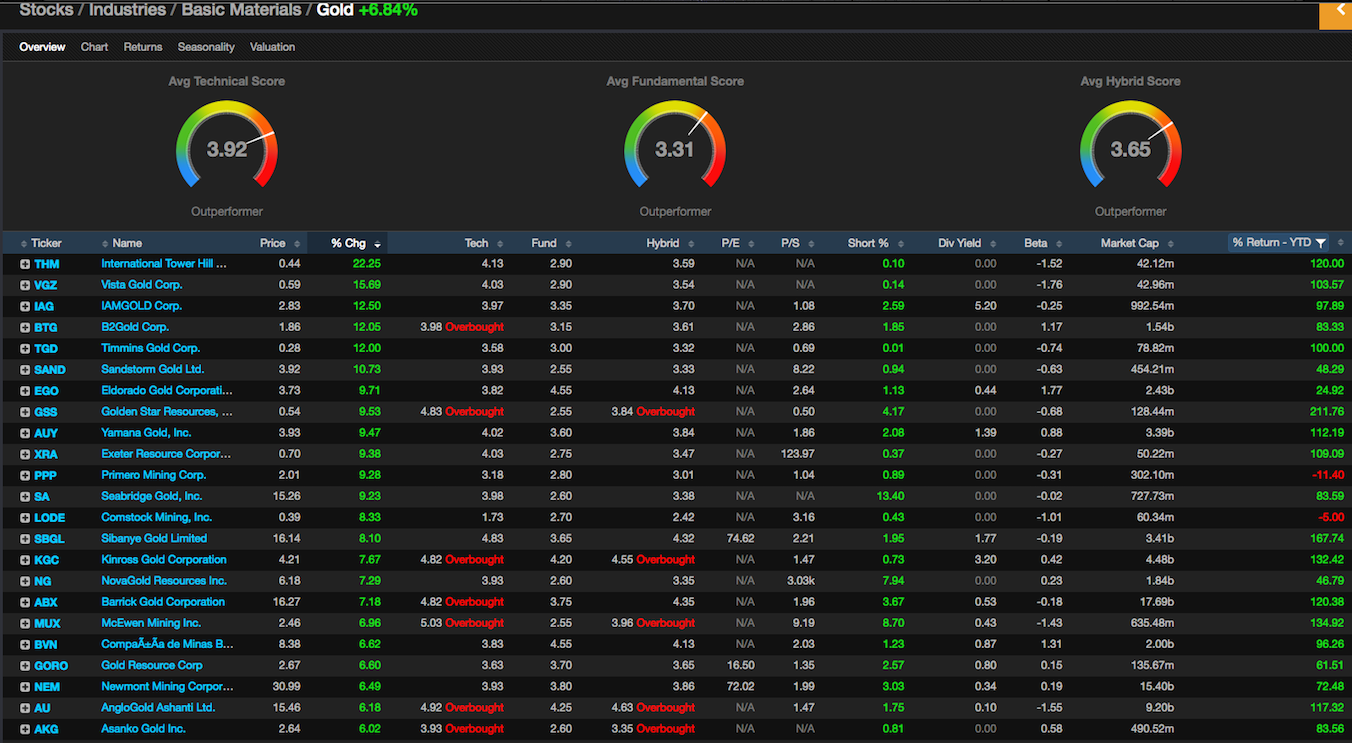
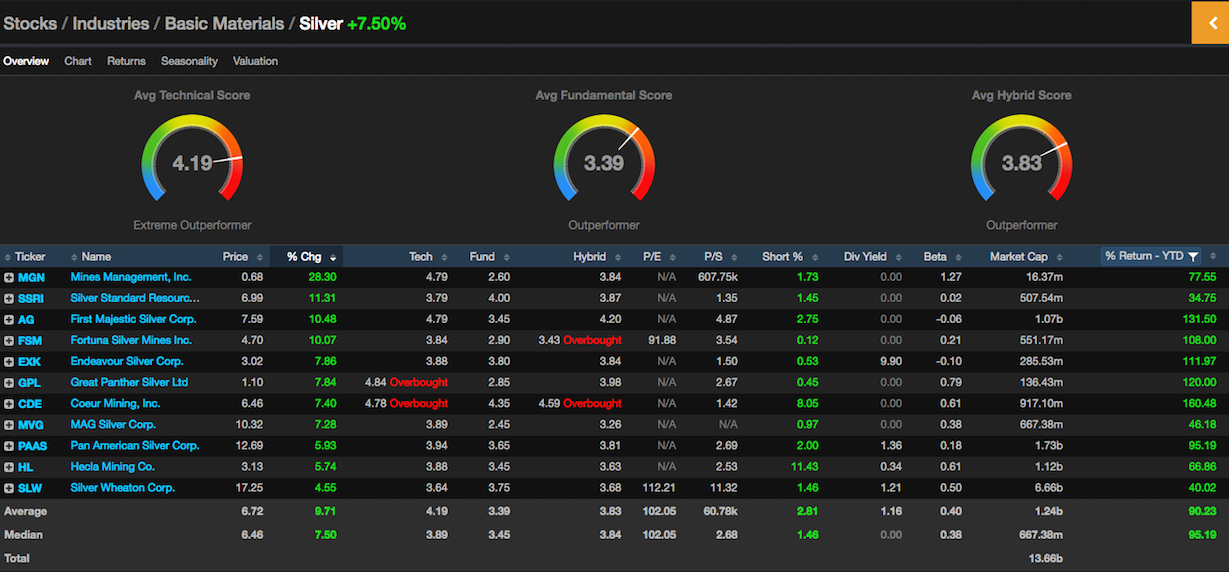
Median returns for both sectors are higher by 7%–based on a mere 1.1% return in the physical metal. Wholly and without question, these moves are of the nonsensical varietal.

gold

silver

Markets are flagging here, giving up a 150 point gain, reminiscent to what occurred on Friday. This is, without question, a very ominous development for the morale of this market. The buyers of this late stage rally are of the cheapest cloth. Their loyalties lie only with their account balances.

Offer them a hard tape, and subsequent losses, and watch them flee the field of battle, en masse, paving the way for a Kool-Aid guy breaking through to the downside.

The rally in gold is more likely due to these mercenarial traders, floundering to find new opportunities, rather than a solid fundamental reason backed by strong asset reallocation.

A storm is coming.

Comments »

Goldman: THE GLASS IS HALF EMPTY, FRIENDO

Everything is skewed to the downside, according to David Kostin–War Chief of U.S. Equity Strategy, Goldman Sachs.

These are the three principle reasons for you to fear the coming ice’d-berg.

1. Energy and banks
“Our analysts have highlighted a laundry list of headwinds including energy counter-party risk, a slowdown in capital markets activity, and a bruising quarter for asset managers,” Kostin & Co. said. “We believe financials earnings per share [EPS}could fall by as much as 25 percent.”

2. Negative guidance
“Since 2006, roughly 20 percent of firms have provided ‘next-quarter’ guidance during earnings season and 73 percent of firms typically guided below consensus,” Goldman found. “Following the depths of the global financial crisis, guidance has grown increasingly negative, and has been worse-than-average since 2012.”

3.Corporate buybacks
Kostin believes the gravy train of equity buybacks is ending: “a meaningful reduction in what is currently the only source of net demand for U.S. shares.”

In summary, the outlook for over 30% of the market is bleak and very dark, and also very dire. With regard to the financials, they’re diving–headlong–into cement pools, with earnings expected to be reduced by 25%. Moreover, this isn’t going to be a one-off event and companies are expected to guide lower, in droves, for next quarter. Lastly, corporate buybacks have run its course. They’ve been maintained at a pace that is unsustainable. The succor the markets have enjoyed with this seemingly endless support of prices has all but come to an end.

BEHOLD the earnings season to come. David Kostin believes you will enjoy it, immensely, similar to a horror movie or something much, much worse–a lifetime of Presidential campaign speeches.

Comments »

Stocks Surge, Gold Surges, Oil Surges, Palladium Surges, Cocoa Surges etc.

A new aristocracy is forming in the marketplace, as the new born investors in distressed commodities express themselves through higher prices.

These new men of industry are above all stations in society. Their milieux is one of extreme wealth and substance. Stocks like CHK and BBG are in their portfolios from the lows. They feel oil will double from here and their new Greenwich mansions will be completed by next fall, should everything go according to plan.

“Isn’t it wonderful?”, asked the wife of one of these illustrious investors.

I cannot begin to describe how wrong this rally in commodity related stocks is. I do not pretend to hold all of the answers to life and I’ve had my fair share of failures throughout the years. But this will not be one of them.

This perversion of reality, this melt up in commodity related stocks, will end. When it does, it will end very badly indeed.

In the meantime, the market is running higher again, save biotechs. I don’t expect the rug to be pulled just yet. I do expect said rug to be completely gone, however, come May.

Enjoy the rally while it lasts.

Comments »

Germany is Still Pissed Off at Draghi for “Helicopter Money” Suggestion

The ECB and the EU are gargantuan failures unraveling in real time. To think that the conservative Bundesbank gents are forced to cede power and control to some Italian lunatic, who thinks it’s ‘very interesting’ to send free money to people directly, as a method of enacting central bank policy, is fucking hilarious.

Germany is besides itself with rage, whilst eating oversized pretzels and swigging down excess quantities of swill, as Draghi makes a mockery of their Austrian school of economics.

A storm of protest erupted in thrifty Germany after Draghi last month described the idea of “helicopter money” – sending money directly to citizens – as a “very interesting” – if unexamined – concept.

Late last week, top ECB officials, including the ECB’s chief economist and its vice president, backpedalled, saying the idea was not on the table. But the damage had already been done.
“The ECB’s policy was already unpopular in Germany and the idea of helicopter money was the straw that broke the camel’s back,” said Joerg Kraemer, an economist with Commerzbank in Frankfurt. “People feel that ideas like this are dangerous.”

German analysts see the idea as an excessive ramping up of a loose money policy that is already fuelling rising property prices in their country, and also because it would undermine the euro by printing money and giving it away for free.

It marked a new low in the often fraught relations between the euro zone’s biggest country and the central bank’s Italian chief, who has recently bemoaned what he described as the “nein zu allem” (“no to everything”) approach – a swipe at Germany.

The ECB is scheduled to meet later this month. I would pay to be a fly on the wall to see the expressions on the German faces when Draghi reveals his Italian ‘bad bank’ fund scheme.

Comments »

Nigeria to Sell Yuan Denominated Bonds

Look for rebels to make miraculous strides towards toppling the government, should this tone continue.

First S. Korea, now Nigeria. The banking system is owned by Anglo-American interests. The Chinese interfering in the affairs of the King makers cannot be a good development for world peace.

The West African nation may shun the Eurobond market, opting instead for renminbi or yen bonds, according to Finance Minister Kemi Adeosun. The government wants to raise as much as $1 billion in international capital markets to finance a deficit that’s forecast to be about 2.2 trillion naira ($11.1 billion) this year, she said April 9.

“We are finding that, indicatively, the renminbi market may be cheaper than the Eurobond market,” Adeosun told reporters in Lagos, the commercial capital. “We are shopping around for the best deals.”

This is very interesting to me. I don’t know why, truth be told.

Comments »

$BBG Credit Facility Slashed by 11% in Spring Redetermination

The credit facility remains undrawn, so this isn’t a big deal. However, it does lessen the companies ability to weather very turbulent storms, should they present themselves.

Co announced that it has successfully completed the semi-annual borrowing base redetermination of its revolving credit facility maturing in April 2020.

The bank group has set a borrowing base of $335 million, an 11% reduction from the previous borrowing base of $375 million.
There were no changes to the terms or conditions of the Facility.

“We remain financially well-positioned with an undrawn credit facility, over $100 million of cash on hand, and nearly two-thirds of our 2016 oil hedged at approximately $80 per barrel.”
The next regularly scheduled borrowing base redetermination will occur on or about October 1, 2016.

image

If I owned this stock, I’d be very interested to find out when those $80 crude hedges expire. Many oil companies took these hedges when the bottom dropped out of crude. But many of said hedges are set to expire soon, FYI.

Comments »

Barclay’s to Sell the Entirety of its Italian Loan Portfolio; Refocusing On U.K., U.S. Business

Nothing to raise an eyebrow at here. The trustworthy lads at Barclay’s are merely “testing the appetite” of the market, by disposing of its ENTIRE portfolio of performing and non-performing assets.

They will be out of the Italian retail business within 1-2 years, probably sooner.

“Barclays is starting the disposal of its portfolio of performing and non-performing loans, the last step of the bank’s exit plan from the Italian retail business,” country chief Alessandra Perrazzelli said in an interview in Cernobbio, Italy on Friday. “We are selling the complete portfolio of loans and we aim at closing the disposal of the whole portfolio in one or two years, depending on market conditions. We are now testing investors’ appetite.”

Barclays is refocusing on the lender’s most profitable units in the U.K. and U.S. and selling consumer operations in continental Europe that it doesn’t consider central to its business. Britain’s second-largest bank sold its operations in Portugal to Spain’s Bankinter SA in September, while Mediobanca SpA agreed to absorb Barclays’s consumer-banking operations in Italy in December.

“Barclays has been working to simplify its business and to concentrate on those businesses where it can make sustainable returns and compete with the big American players,” said Perrazzelli. “This process is also involving Italy, where our investment and corporate banking businesses perform very well.”

First Portugal and now Italy. Perhaps the Barclay’s folks are being prescient by withdrawing from the weaker EU countries while the bids are strong.

Comments »

$CHK Pledges Additional Assets to Reaffirm Credit Facility

This is good news for the cash strapped natural gas wasteland called Chesapeake. They reaffirmed a $4 bill credit facility. However, there are hitches and triggers which may pose a problem should things get dicey.

In connection with the redetermination, Chesapeake agreed to pledge additional assets as collateral under the Credit Agreement.

As part of the amendment, the next scheduled borrowing base redetermination review has been postponed, and the lenders have agreed not to exercise their interim redetermination right, in each case until June 2017.

The amendment includes a collateral value coverage test, which may limit Chesapeake’s borrowing capacity if its collateral coverage ratio falls below 1.25x, tested as of March 31, 2017.
The amendment provides temporary covenant relief, with the facility’s senior secured leverage ratio suspended until September 2017, then reverting to 3.5x through December 2017 and decreasing to 3.0x thereafter.

In addition, the amendment reduces the interest coverage ratio to 0.65x from 1.1x through March 2017, after which it will increase to 0.70x through June 2017, then reverting to 1.2x in September 2017 and to 1.25x thereafter.

During the period in which the existing maintenance covenants are suspended, Chesapeake has agreed to maintain a minimum liquidity amount of $500 million at all times, increasing to $750 million if its collateral coverage ratio falls below 1.1x, tested as of December 31, 2016.

The amendment also gives Chesapeake the ability to incur up to $2.5 billion of first lien indebtedness secured on a pari passu basis with the existing obligations under the Credit Agreement, subject to payment priority in favor of the existing lenders and subject to the other limitations on junior lien debt set out in the Credit Agreement.

The market is viewing this as good news and the stock is rallying. Let’s hope the company can keep its collateral coverage ratio above 1.25x and maintain liquidity of $500 mill; otherwise, this credit facility will come into immediate jeopardy.

Comments »

$NOV Slashes Dividend, Guides Earnings Lower; Stock Plunges

No surprise here. I’m expecting to see this sort of thing, industry wide, as companies vie to deleverage their balance sheets. Dividends will be cut. Earnings guidance will be slashed or suspended. The strong shall survive and weather the storm.

image

Co sees Q1 revs down 20% QoQ to $2.16 bln vs $2.38 bln Capital IQ Consensus. Importantly, although the near-term outlook remains challenging, NOV remains strong financially. NOV’s total debt decreased by over $500 million during the first three months of 2016 and the decision to reduce the dividend is expected to improve future net cash flow by ~$615 million per year.

“We believe the dramatic reductions in capital spending are accelerating global production declines, setting the stage for a recovery in demand for NOV equipment and technologies. Reducing our dividend will allow us to preserve capital to invest in future growth opportunities and enhance the core capabilities our customers will need when industry activity increases.”

The smaller companies will likely sing a more optimistic tune, in a delusional effort to assuage investors. The clock is ticking. The industry cannot thrive at $40 WTI.

Comments »

U.S. Army 1: Bill Ackman 0; $CP Terminates Bid to Acquire $NSC

Just a few days ago, the United States Army voiced its opposition to the royalist scum at CP acquiring a vital portion of the U.S. railway system in NSC. Early this morning, the lads over at CP, Ackman’s largest holding, announced they’d terminated the bid to acquire said assets.

“We have long recognized that consolidation is necessary for the North American rail industry to meet the demands of a growing economy, but with no clear path to a friendly merger at this time, we will turn all of our focus and energy to serving our customers and creating long term value for CP shareholders,” said Chief Executive Hunter Harrison said in a statement.

Had the bid come from China, as sure as I’m sitting here, the lads over at NSC would be prepping to take classes to learn mandarin.

Comments »