iBankCoin
Home / 2016 / April (page 19)

Monthly Archives: April 2016

Rio Tinto CEO: The Iron Ore Rally is About to End

Good afternoon lads; did you miss me?

I came across this delightful, uplifting story, regarding iron ore and how one of the CEO from the 2nd largest producers of it said it was about to ‘fizzle out.’

Here’s what he had to say.

Iron ore prices “may well soften in the second half,” Walsh told reporters after the company’s annual shareholder meeting. “I’ve said all along that we expect the iron ore prices will be volatile. That’s what we’re seeing.”

Iron ore is up 55% since December on imaginary demand from China.

When asked about being the Saudi Arabia of iron ore, messing up markets with cheap ore,  Jan du Plessis, Chairman from RIO (what is he Dutch?),  said  it was “an absolute nonsense.”  We have no desire to squeeze anybody out of the market. We’re not flooding the market. We’re not trying to be Saudi Arabia at all.”

Obviously, he’s lying.

RIO’s share price is up 30% over the past 3 months.

Comments »

Analysts Take Seagate to Task For Sucking So Bad

I can’t believe this company is stupid enough to pay a 7.4% dividend. I mean, really, who the fuck pays a 7.4% divvy in the tech space. I’m going out on a limb here and guessing that management owns a bunch of the stock. I know, I should just go look it up; but I don’t feel like it.

Will someone go check this for me? Thanks.

If they own a bunch of stock, then they’re using the companies cash flow as their personal piggy bank–via dividends that exceed normalcy. If not, they’re simply morons.

image

Analysts are slashing STX this morning off horrendous earnings. But don’t worry, the fucking dividend is still intact.

Via briefing.com

Mizuho notes STX preannounced negatively after the close, noting weaker HDD demand (down 18% q/q) with weakness in mission-critical enterprise HDD and PC desktop products. STX now sees MarQ revenue at $2.6B (versus prior $2.7B guide) with GM at 23%, 270bps below consensus, on lower utilization. They believe increasing 3D-NAND supply could remain a structural headwind for high-margin 10K/15K HDD drives. They’re not changing estimates here and they’re maintaining their Neutral rating.
Cowen lowers tgt to $35 from $36 on lower estimates following STX’s negative pre. What’s most worrisome to them, an issue they highlighted in their recent initiation, is the apparent tradeoff between servicing the $760MM/yr div’y (w/ FCF potentially <$800MM CY16) vs. making meaningful investments to offset challenges in core HDD TAM. If any, see risk to downside for WDC/MRVL, but both should fare better.
RBC Capital Mkts stays at Outperform, $36 tgt on STX following the negative pre-announcement after market close. Pre-announcement was $2.6B revs and 23% non-GAAP gross margin, on 39M units and 40% market share. Based on the preliminary results, they think co had share loss to WDC on enterprise front. They think TAM is likely to remain in the 95-98M range for JunQ (they are modeling 97M). Positively, hyperscale demand appeared to be better than expected as co saw strength in 8TB nearline products. Going into the earnings call on April 29, they think investors will focus on enterprise demand outlook and PC demand update.
Stifel now arrives at a non-GAAP EPS of ~$0.37, vs. their prior $0.61 estimate (Street: $0.63). They lowers F2016, F2017, and F2018 revenue/EPS estimates from $11.3B/$2.69, $11.4B/$3.91, and $11.4B/$4.14, respectively, to $11.1B/$2.14, $11.0B/$2.79, and $11.0B/$3.43. They maintain their Hold rating, and expect better results out of Western Digital (WDC). With $2.9B of net debt exiting F2Q16 and ~$700M/annum of dividend payments, the expect increasing investor questions/concern over Seagate’s balance sheet and/or capital allocation strategy going forward.
Maxim cuts tgt to $36 from $39. Given negative pre-announce details, we estimate mission critical HDD units likely declined ~25% y/y vs our prior estimate down 12% y/y. Their data points indicate the mission critical miss is not an issue that will subside, reducing FY17 EPS by 15%. They still see dividend as likely safe, but risk of a cut is rising, in their view. For WDC on a pro-forma basis the potential severe declines in mission critical will be neutral, in their view.
Needham cuts tgt to $41 from $47. Weak PCs and even softer mission-critical drives are not surprising to them. Their positive stance is based on: 1) maintained dividend (we continue to expect this, and it makes the >7% yield too good to ignore); and 2) manufacturing footprint consolidation of 20-30% of capacity and mix shift to a largely enterprise high-cap focus dramatically changes the business model. They see everything else in the interim as theater and would use any opportunities to build positions in the name. Maintain Buy.

Comments »

JP Morgan Likes Ecoli; Upgrades $CMG to Overweight

It’s all over for the projectile vomiting haters, apparently. JP Morgan has issued a formal decree, announcing that the worst is thereunto behind us and for all to jump back into the muddy waters of burrito land, CMG.

Via TheFly.com

Chipotle upgraded to Overweight from Neutral at JPMorgan JPMorgan analyst John Ivankoe upgraded Chipotle Mexican Grill to Overweight from Neutral and raised his price target for the shares to $510 from $465. The stock closed yesterday down 35c to $444.27. Chipotle’s same-store-sales are set to sequentially improve from their bottom in Q1, which will allow investors to focus on earnings recoverability, Ivankoe tells investors in a research note. The analyst expects the company’s earnings in its fiscal year 2017 to be very close to its fiscal year 2014 earnings. This shows that the food safety crisis caused three full years of lost earnings despite stores over the time period rising to 2,483 from 1,785, Ivankoe points out. His upgrade centers on Chipotle being a “highly meaningful brand” that can regain customer trust with time. The analyst expects normal earnings growth to resume by fiscal year 2018 and believes 20%-plus growth can be sustained through at least fiscal year 2020.


Comments »

Kuroda: ‘I Don’t Think Negative Interest Rates Backfired’

It could’ve been worse. If Woody had gone straight to the police, this would’ve never have happened.

“I really don’t think that the introduction of the negative interest rate backfired or caused the yen to appreciate and stock markets to decline in Japan,” Kuroda said during a question and answer session at Columbia University in New York. “If anything, I can say that if we didn’t introduce the QQE with the negative interest rate, financial markets in Japan would have been even worse.”

JPY

The Yen is up to the tune of 10% since Japan adopted negative rates on January the 29th, 2016.


Comments »

BTIG: The Bank Rally is Bullshit; Fade the Banks

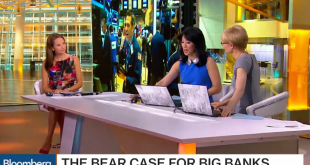
Okay, I am paraphrasing a bit here with the title. Nonetheless, BTIG tossed out their best chart chomper today to discuss bank stocks with BBG and she lit them on fire, suggesting the rally was faux, should be faded and wholly and entirely laughable.

I paraphrased again.

Comments »

Jose from the IMF: Negative Interest Rates Helps Create Jobs

George Orwell is rolling over in his fucking grave. Jose from Lima, who happens to be a director at the IMF, said with a very straight face that negative interest rates, aka the shit that mugs old people, is a net positive for the economy. He begs your pardon and asks you to see the ‘broader picture’ and to not get hamstrung by the societal muck of ‘savers’ and to BEHOLD the new world order and their grande scheme to GET PAID FOR BORROWING MONEY.

The greater good, gents. Negative rates creates jobs, builds businesses, pays for your daughter’s birth.

Seriously, what the fuck is going on here?

Comments »

KABOOM! The Bull Market Has Only Just Begun

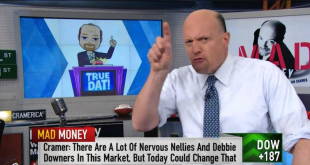
In this segment of ‘what the fuck is Jim Cramer talking about?’, Jim posits the bull market is in its beginning stages. Condescendingly, and decidedly so, he likens the ‘pin action’ in many of the tech names as being ‘obvious’ and he makes verbal translations of exploding TNT to describe the bullish nature that is about to befall you–‘KABOOM.’ The rails are back, obviously–just like the banks, industrials, and anything else that walks and talks. As a matter of fact, all of China and Europe are back, helping the useless and pathetically ‘deal-less’ (extra Trump) United States step out from its morass to enjoy the fruits being bore in Germany.


This is one of the seals from hell being lifted. The path towards a bidless stock market, rigged with exploding hand puppets, is through a Jim Cramer ‘THIS IS THE FUCKING BEGINNING OF THE BULL MARKET, KABOOM” segment.

You’ve all been warned, in the most dire of terms imaginable.

Comments »

MARKETS RAMP INTO THE CLOSE; NEW HIGHS AND JOYOUS OCCASIONS ABOUND

What wonderful splendor. Everyone made money today, from dollar bulls to bond longs. Everyone won but gold longs; but they’re not human. They’re subhuman offal, floating about the lagoon, corrupting and infecting the environment with their rhetoric. Some argue that vaccines are poisonous toxins, or how Ted Cruz is actually a tool for the Bush crime family. I posit that gold bugs are wholly responsible for global warming.

Markets crushed higher into the close, collapsing the wheeled chairs of disabled folks worldwide. I have a keen interest in only seeing the complete and thorough annihilation of the oil barrel class of investor. As far as I am concerned, the rest of you are free and welcomed to thrive and run about the prairies, eating zebra and giraffes, if you should choose to do so.

But know this. This arid weather you seem to be enjoying now will not last. Very soon, within 2 week’s time, a great thunderous storm will appear, flooding the prairie, causing great angst and carnage amongst the irresponsible zebra eaters. Giraffes will roam free and step on the heads of those caught in the floods (they have long necks and can survive the floods). Le Fly will appear, out of nowhere, manning an ark, floating free and fast, pummeling over the skulls of the zebra eaters–like small rocks on the bottom of the ocean floor.

Comments »

THE VIX ENTERS ‘THE RETARD ZONE’

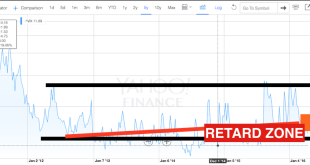
The VIX is like the loser index of the market, the fat girl at the end of the bar, the uncoordinated athlete on the football team. It has now entered the retard zone of zealotry. This is the part of the story when traders are gallivanting about the drawing room, popping champagne corks into each other’s faces–until one of them filled with c-4 explosives blows up the whole room.

VIX

The last time the VIX fell this hard was in March of 2012. Shortly thereafter, in May of 2012, the S&P 500 fell by 6%.

Comments »

Goldman: These Companies Will Get Hurt If Slavery is Abolished

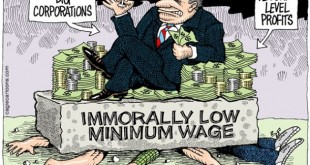
This argument about keeping the minimum wage depressed is so fucking absurd. It’s not like the asshole at WMT or TGT are reinvesting the money wisely into plants and equipment. For the most part, they’re jetsetting around the globe, lavishing themselves with ridiculous pay packages and buying back their own stock like imbeciles. Many of these C-level execs are taking far too much viagra and I think there are deleterious effects on cognitive functions associated with too many erections.

At any rate, Goldman runs down a list of names who might be hurt, mildly, by a hike in minimum wage. Could you imagine the outcry if these devils were forced to pay a normal wage and weren’t wholly reliant upon slavery abroad to produce their goods?

Why, their checkered pants might get a crease or two.

Goldman analysts led by Ben Snider and David Kostin, note that for every 1 percent rise in labor costs (above a baseline of 3 percent) there’s a 0.7 percent drag on earnings per share for the S&P 500. That headline figure disguises a big industry-level variation, however.

Names in the low labor cost basket include Netflix Inc., NIKE Inc., Exxon Mobile Corp., and Metlife Inc. Companies in the high-cost basket which are more exposed to higher pay are Whole Foods Market Inc., Yahoo! Inc., and General Mills Inc.

I don’t understand. Where is WMT, TGT and other retailers? What sort of research is this?

Comments »